



PW Consulting Forecast: Preeclampsia Diagnostic Market to Top USD 2,712.08 Million by 2032

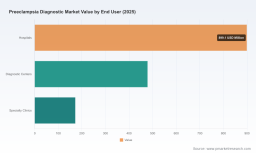
Preeclampsia Diagnostic Market — 2026 Strategic Preview
PW Consulting’s latest market study on Preeclampsia Diagnostics delivers a tactical blueprint for corporate strategy through 2026 and beyond. Our analysis synthesizes regulatory inflections, reimbursement dynamics, competitive maneuvering and technology evolution into a compact set of decision levers for life-sciences executives, commercial teams and investors. At a macro level, the market reached approximately USD 1.55 billion in 2025 and, under our base-case assumptions, is expected to expand at a compound annual growth rate (CAGR) of about 8.32% through the 2026–2032 forecast horizon. This trajectory creates both near-term commercial opportunities and longer-term structural choices for businesses positioned across biomarkers, platforms and point-of-care solutions.
Preeclampsia Diagnostic Market
Why this report matters for 2026 decision-making
-
Actionable scenarios calibrated to regulatory inflection points. The study models alternative adoption curves that reflect recent regulatory milestones and pending reimbursement shifts, enabling management teams to stress-test launch and scale plans against plausible 2026 conditions.
Preeclampsia Diagnostic Market -
Commercial levers prioritized by ROI. We convert surveillance and diagnostic use cases into revenue-efficiency matrices (sales force, reference laboratory partnerships, price points, and channel mixes), so you can quantify the marginal value of each commercialization choice without getting lost in raw segment tables.
Preeclampsia Diagnostic Market -
Go/no‑go decision support for product development. The report frames clinical-evidence thresholds, payer triggers and expected time-to-reimbursement for novel biomarker assays and integrated platforms — critical inputs when deciding whether to accelerate a development program in 2026.
-
Competitor playbooks and M&A signals. We map capabilities and recent moves of the leading incumbents and emerging specialists to reveal realistic partnership, licensing and acquisition pathways that can materially change competitive positioning in the next 12–18 months.
Market trajectory and core dynamics
The preeclampsia diagnostics market has moved from niche to mainstream surveillance during the 2020–2025 period, driven by the validation of angiogenic biomarkers (notably sFlt‑1 and PlGF), improved analytic platforms and growing clinical acceptance of biomarker‑informed risk stratification. With a market size near USD 1.55 billion in 2025 and a projected CAGR of c.8.3% through 2032, the market now supports differentiated commercial models — from central-lab reference testing to decentralized, rapid-response testing in obstetric triage.
Two structural themes will define winners and laggards in 2026: (1) the ability to convert regulatory approvals into reimbursed clinical pathways quickly, and (2) the agility to deploy hybrid lab/POC strategies that balance clinical sensitivity with unit economics. Our concentration analysis indicates moderate market aggregation: the top-three players account for a meaningful share of revenues, and the top-five capture a clear majority — a configuration that supports both continued consolidation and selective niches for specialists.
Competitive landscape — what recent moves imply for strategy
-
Large diagnostics incumbents (e.g., Roche, Thermo Fisher, Siemens, Abbott, QuidelOrtho) now control critical platform access and validated assay portfolios. Regulatory milestones in 2024–2025 (notably FDA 510(k) clearances and De Novo pathways) have shifted the basis of competition from pure assay performance to platform access, lab network partnerships and bundled maternal‑health solutions.
-
Specialist innovators (e.g., Sera Prognostics, Metabolomic Diagnostics, Diabetomics, DRG Instruments) continue to expand the biomarker toolkit with proteomic and metabolomic approaches. Their strategic value is increasingly as sources of acquisition or licensing targets for platform incumbents seeking to broaden clinical indications or improve early‑prediction capabilities.
-
Reference laboratories and service networks (e.g., ARUP Laboratories, Trinity Biotech’s New York reference offering) are acting as rapid commercialization conduits for new assays and biomarker ratios. Recent product launches and lab‑based services demonstrate an opportunistic path-to-market that sidesteps some capital-intensive distribution investments.
Recent developments underscore the commercial momentum: a leading diagnostics company received FDA clearance in early 2025 for a prognostic sFlt‑1/PlGF ratio test in hospitalized pregnant patients, while collaborations and new lab-based launches in 2025 expanded clinical availability in high-risk populations. These events materially change adoption timing assumptions in our base and upside scenarios.
Regulatory and reimbursement inflections to watch
-
Regulatory clarity on intended use matters. FDA 510(k) and De Novo decisions in the past three years have clarified acceptable labeling language for prognostic and triage uses of sFlt‑1/PlGF assays. Companies that align clinical protocols and labeling strategies with these precedents will shorten adoption cycles.
-
Reimbursement change-players. National and payer-level reimbursement policy shifts — including anticipated changes in obstetric billing frameworks — will affect economics for expanded monitoring. In particular, the transition from global OB codes to more granular antepartum billing models is scheduled to affect clinical workflows and revenue attribution beginning in the next multi‑year window.
-
Guideline endorsement accelerates adoption. Health-technology guidance from major national bodies recommending PlGF‑based testing as an adjunct to clinical assessment materially reduces the friction for system-level uptake when coupled with local pathway workstreams.
Commercial implications and tactical playbook for 2026
-
Prioritize reimbursement-first pilots. In markets with recent guideline support, run payor‑aligned pilot programs that document utilization, length-of-stay and high-risk management savings. These real-world economic dossiers de-risk coverage conversations and provide procurement counters for pricing negotiations.
-
Optimize channel strategy by customer segment. Hospitals and high-volume diagnostic centers require different value propositions than outpatient specialty clinics; invest in targeted field capabilities and evidence packages that demonstrate operational benefits to each end-user.
-
Leverage lab-as-launch partner models. Reference labs with broad payer contracts can accelerate access while lowering upfront commercialization costs. Consider tiered collaborations that begin with lab-service launches and evolve into co-marketing or licensing arrangements once utilization is proven.
-
Invest in clinical-outcomes evidence. Payers and hospital systems increasingly demand outcomes‑based data showing how biomarker-guided management reduces adverse events, unnecessary admissions or resource use. Prioritize outcome trials and health-economic modeling that map directly to system-level KPIs.
-
Prepare for mixed delivery models. Build modular offerings that can be deployed on high-throughput central platforms, mid‑lab analyzers, and point-of-care devices — this hedges adoption risk and maximizes addressable market share.
Strategic M&A and partnership signals
Given the market’s moderate concentration and the ongoing technology innovation, expect continued strategic transactions in 2026 that follow two archetypes: (1) platform players acquiring or licensing biomarker innovators to broaden indication sets and defend installed bases; and (2) specialized assay developers partnering with reference labs to commercialize quickly with minimal capital outlay. Investors and corporate development teams should watch for tuck-in opportunities that offer clear clinical-differentiation and near-term reimbursement pathways.
What PW Consulting’s report delivers — practical contents
-
Market-sizing and forecast model (2020–2032), including sensitivity scenarios tied to regulatory and reimbursement changes.
-
A practical go-to-market playbook: channel economics, unit-cost models, pricing thresholds, and sample launch roadmaps for three commercialization archetypes.
-
Regulatory and payer decision maps, including implications of recent FDA clearances and expected billing changes at national levels.
-
Clinical evidence synthesis and protocol templates that align key endpoints to payer decision criteria and hospital quality metrics.
-
Detailed competitor intelligence dossiers (strategies, product portfolios, platform access, partnership histories) and a dynamic M&A watchlist.
-
Primary interview insights from healthcare-system pharmacists, laboratorians, obstetricians, and payers to validate adoption drivers and operational barriers.
How to use this analysis in your 2026 planning cycle
-
Board-level prioritization: translate the forecast scenarios into two investment cases — “scale and defend” for platform incumbents and “clinical proof to partner” for specialists — and assign clear go/no‑go triggers.
-
Commercial planning: use our channel and payer playbooks to build a 12‑month pilot that produces payor-acceptable evidence for coverage expansion.
-
R&D sequencing: align assay-development milestones with regulatory submission timelines and targeted clinical endpoints that drive payer decisions, thereby compressing the time from approval to reimbursed adoption.
-
M&A scouting: prioritize targets that de-risk market entry (proven biomarkers, reference-lab relationships, or complementary platform tech) and prepare streamlined diligence checklists based on our templates.
Final note — the trailer strategy
This briefing is intentionally concise: it shows the strategic contours and highlights the levers that matter for decisive action in 2026 while omitting granular segmentation tables and raw regional/application numbers. Those detailed datasets, model access and the full set of proprietary recommendations are available in the comprehensive PW Consulting report and accompanying excel model. For teams preparing budgets, business cases or M&A mandates in the coming planning cycle, the full dataset is the most time‑efficient route to informed decisions.
Contact PW Consulting to request the full Preeclampsia Diagnostic Market report, gain access to the forecast workbook and schedule a strategy workshop tailored to your organization’s 2026 objectives.
For detailed analysis of this topic, please visit the official page: Preeclampsia Diagnostic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


