



PW Consulting Forecast: Turbine Discs Broaching Machines Market Poised for 6.0% CAGR, Transforming Aerospace and Power Sectors

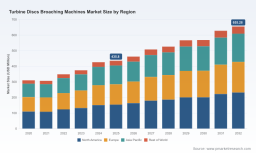
Turbine Discs Broaching Machines Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s Turbine Discs Broaching Machines Market report offers an executive-grade, decision-focused view into an industrial niche that sits at the intersection of advanced machining, aero‑engine manufacturing, and power-generation supply chains. The global market for turbine discs broaching machines reached USD 435.8 Million in the base year (2025) and, driven by steady demand for precision fir‑tree and dovetail broaching, is forecast to grow at a compound annual growth rate (CAGR) of 6.0% across the 2026–2032 forecast window. By the end of that horizon the market is expected to approach the mid‑six‑hundred million USD range.
Turbine Discs Broaching Machines Market
This briefing is designed to demonstrate the kind of actionable, evidence‑based insight the full PW Consulting report delivers to procurement executives, plant managers, OEM strategy teams, and private‑equity investors planning capital deployment in 2026. It intentionally surfaces strategy‑relevant conclusions while withholding the underlying granularity (region/application/type splits and transaction‑level datasets) to guide interested stakeholders to the full study.
Turbine Discs Broaching Machines Market
Why this matters for enterprise decisions in 2026
- Capital spending cadence: Broaching machines for turbine discs represent a long‑lived equipment class with high engineering specificity. Decisions made in 2026 on new machine purchases, factory layout, or refurbishment programs will influence manufacturing cost curves and lead times well into the next decade.
- Supply‑chain resilience: The broaching process is tightly coupled to tooling, broach manufacture, and material supply (notably high‑strength, heat‑resistant superalloys). Procurement strategies that overlook tooling lifetime, qualification cycles (e.g., NADCAP), and remanufacturing options risk production interruptions.
- Competitive differentiation: Machine design choices (vertical vs horizontal, automation, in‑process metrology) directly affect unit throughput and tolerance capability for fir‑tree/dovetail profiles. These choices translate into source‑of‑competitive‑advantage for aero OEMs and MROs.
- Investor timing: With a projected ~6% CAGR, the market exhibits steady growth rather than speculative spikes—an important consideration for investors balancing near‑term returns with long‑term industrial value.
Market dynamics: drivers, constraints, and structural change
- Demand drivers: Continued growth in commercial aviation and expansion of gas‑turbine power generation capacity are the primary demand levers. Precision slots and fir‑tree profiles remain critical failure points that mandate high‑force, specialized broaching processes.
- Material complexity: Turbine discs are commonly made from nickel‑based superalloys (e.g., Inconel and equivalents). These materials require high static forces, robust machine rigidity, and specially coated broaches—factors that increase machine and tooling cost and complicate supply chains.
- Quality and accreditation: NADCAP accreditation and equivalent aerospace quality regimes are a gating factor for any supplier or in‑house broaching operation serving aero engines. Compliance timelines and audit readiness are practical constraints on capacity expansion.
- Technology adoption: Automation (robotic loading/unloading, tool‑change automation), process monitoring, and integrated metrology are increasingly standard in new builds. Adoption rates differ by buyer type—but the quality/throughput benefits are significant for high‑mix, high‑volume programmes.
- Aftermarket & remanufacturing: Given the capital intensity of new machines, a robust market for remanufactured/used machines and services (including broach reconditioning) exists; firms that coordinate OEM support, tooling services, and MRO offerings capture a larger lifetime revenue pool.
- Concentration: The market shows moderate concentration at the top end—our analysis identifies a CR3 of approximately 58.5% and a CR5 near 76.2%—indicating that a handful of specialised suppliers account for the majority of capacity and capability.
Competitive landscape: profiles and strategic implications
The competitive map of turbine disc broaching is populated by specialist machine builders, tooling houses, and service providers. The PW Consulting report evaluates technical capability, installed base, aftersales capability, and strategic positioning. Below is a distilled view of key players assessed in the study and what they imply for 2026 strategies.
Turbine Discs Broaching Machines Market
- FORST Technologie GmbH & Co. KG (Germany) — Specialist in both horizontal and vertical platforms tailored to dovetail and fir‑tree external broaching for discs. FORST’s compact, rigid designs and emphasis on process monitoring and automation make it a natural fit for aero and power OEM lines that demand high accuracy and production traceability. Strategy implication: prime candidate for OEMs standardising on integrated monitoring and automated cell design.
- Broaching Machine Specialties (BMS) (Novi, Michigan, USA) — Known for supplying new, used, and remanufactured large horizontal machines, including legacy platforms. BMS’s role in equipment lifecycle extension makes it strategically valuable for firms seeking lower‑cost capacity expansion or rapid lead‑time alternatives to new equipment. Recent public outreach (Manufacturing Mondays hosting in Nov 2025) highlights domestic supply‑chain positioning. Strategy implication: attractive for operators prioritising CAPEX efficiency and quick ramp‑up.
- Arthur Klink GmbH (Germany) — Delivers bespoke special broaching machines and tooling with capabilities oriented to precision aerospace components. Ideal for niche, highly engineered parts and smaller series production where a tailored machine solution is preferable. Strategy implication: consider for specialised programmes with unique geometries or where in‑house development of tooling is a differentiator.
- Colonial Tool Group (USA) — Provides CNC, multi‑axis horizontal systems rooted in established designs, offering a bridge between legacy capability and modern automation. Suited for aerospace shops transitioning away from manual processes without sacrificing stroke length or part envelope. Strategy implication: good partner for phased automation upgrades.
- Nachi‑Fujikoshi Corp. / Nachi America (Japan) — Offers vertical broaching platforms and heavy‑duty surface broaching machines capable of high‑accuracy, heavy material removal. Nachi’s heritage in mechanical broaching and tooling for fir‑tree profiles positions them for high‑precision rotor disc work. Strategy implication: consider for applications with stringent dimensional and surface finish requirements.
- Pioneer Broach Company (USA) — Combines machine and broach design with NADCAP‑accredited services; useful for operations requiring integrated broach design and process certification. Strategy implication: strong option where qualification speed and auditable process controls are critical.
- Taizhou Chengchun Automation Equipment Co., Ltd. (China) — Competes on cost and serves buyers prioritising procurement price for groove‑broaching, with electrical and hydraulic system offerings. Strategy implication: source for cost‑sensitive programmes, subject to qualification and quality audits.
Recent industry activity underlines supply‑side visibility: FORST showcased solutions at a major production technology trade fair in 2025, and a U.S. specialist hosted a high‑profile manufacturing outreach event later the same year—both signal active vendor engagement with OEMs and policy stakeholders.
What the full PW Consulting report contains (practical, action‑oriented modules)
- Market sizing and validated forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario toggles for demand shocks, tooling shortages, and regulatory ramp‑ups.
- Vendor benchmarking matrix assessing technical capability, installed base, service network, lead time, and qualification support.
- Capital economics: total cost of ownership models for new vs remanufactured machines, including tooling lifecycle, downtime risk, and productivity curves.
- Supply‑chain stress tests: raw‑material exposure (nickel‑alloy availability), single‑sourcing risk, and qualification timelines for NADCAP/aerospace approvals.
- Process playbooks: best practices for broach design, machine maintenance, automation retrofits, and metrology integration specific to turbine disc geometries.
- M&A and partnership candidate list with strategic rationale for buy/build/partner decisions (confidential profiles available in the full report).
- Regulatory and quality readiness checklist—practical steps to compress NADCAP timelines and audit readiness for broaching operations.
- Go‑to‑market and procurement playbooks tailored to OEMs, Tier‑1s, machine builders, and MRO service providers.
Strategic recommendations for buyers and investors in 2026
- Prioritise qualification pipeline management: build tooling qualification and NADCAP readiness into procurement timelines—these are often the critical path for new programme launches.
- Balance CAPEX and time‑to‑capacity: consider a blended approach of selective new machine buys for high‑mix lines and remanufactured platforms where speed and cost are decisive.
- Invest in process monitoring and predictive maintenance: adding in‑process metrology and condition monitoring reduces rework risk on costly turbine discs and improves first‑pass yield.
- Lock in tooling partnerships: broach design and reconditioning partners materially affect lifecycle economics—integrated agreements can reduce TCO by extending broach life and stabilising cycle time.
- Build a modular automation roadmap: standardise interfaces and cell footprints to make future automation upgrades lower‑cost and less disruptive.
- Stress‑test sourcing strategies against alloy shortages: assess alternate material pathways and long‑lead contracts for nickel‑based superalloys to avoid late‑stage production bottlenecks.
- For investors: target service and tooling players for predictable, recurring revenue streams; consider minority investments in remanufacture specialists to capture aftermarket economics.
How PW Consulting can support your 2026 agenda
PW Consulting offers tailored advisory engagements that convert the insights in the report into executable plans: supplier selection support, request‑for‑proposal (RFP) design for machine purchases, CapEx prioritisation frameworks, NADCAP fast‑track programmes, and bespoke diligence for M&A deals. We combine benchmarking data, factory‑level engineering assessments, and procurement playbooks to shorten decision cycles and de‑risk implementations.
Next steps
This briefing intentionally highlights the report’s strategic value while withholding transaction‑level splits, region‑and‑application numerical breakouts, and certain vendor revenue detail. Those granular datasets, interactive forecast models, and confidential supplier profiles are available exclusively within the full PW Consulting Turbine Discs Broaching Machines Market report. For immediate access, licensing information, or to request a bespoke consulting engagement tailored to your 2026 planning cycle, please visit our report page or contact a PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Turbine Discs Broaching Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


