



PW Consulting: Disproportionated Rosin Market to Reach USD 567.52 Million by 2032 at a 4.19% CAGR, Led by Asia‑Pacific’s USD 215.5 Million Share

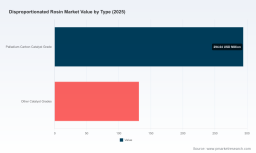
Disproportionated Rosin Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s new Disproportionated Rosin (DPR) Market report offers a pragmatic, boardroom-ready intelligence package designed to shape corporate strategy in 2026. Anchored in a rigorous data foundation and validated by primary interviews with manufacturers, formulators, and raw-material suppliers, the report explains how a modest but steady market expansion—underpinned by evolving raw-material dynamics, regulatory pressure, and application-level product innovation—translates into concrete choices for procurement, R&D, and M&A. Below is a concise executive preview of the report’s most consequential insights and the practical tools we provide to act on them. For the full segmentation datasets, regional and application breakdowns, and supplier-level scorecards, please refer to the complete report on PW Consulting’s website.
Disproportionated Rosin Market
Macro view: growth, scale and market structure
The DPR market demonstrates resilient expansion: our base-year assessment (2025) values the market at USD 425.5 Million (revenue, USD Million), and the market is projected to grow at a compound annual growth rate (CAGR) of 4.19% across the 2026–2032 forecast period. By the end of our forecast horizon the market reaches a materially larger footprint, reflecting both incremental demand in adhesives, rubber emulsions and specialty inks, and steady premiumization as formulators trade-up to performance grades.
Disproportionated Rosin Market
Market concentration is best described as mid-range: the top three and top five participants account for a meaningful but not dominant share of global revenues. That structure creates persistent opportunities for regional champions and specialized providers to capture value while preventing rapid commoditization at the global level.
Disproportionated Rosin Market
Upstream dynamics that will determine 2026 outcomes
- Feedstock composition and price pressure. Global rosin production remains large and concentrated in pine-derived streams, with gum rosin and tall oil rosin as the principal upstream feedstocks. Tall oil’s steady contribution as a by-product of pulp and paper processing provides a complementary sourcing channel and a natural hedge versus plantation-derived gum rosin. Industry reference prices indicate an average export price point that buyers and formulators should explicitly model into FY-26 procurement budgets.
- Processing technology and product differentiation. Disproportionation and subsequent catalytic stabilization materially influence a DPR product’s oxidational stability, softening profile and compatibility with polymer matrices. Suppliers that own advanced catalytic platforms or proprietary stabilization protocols command pricing power in specialty segments where heat resistance and tack retention are critical.
- Regulatory overlay. DPR sits within the broader rosin derivative space covered by REACH registrations in relevant jurisdictions. Compliance needs—particularly around stabilization and impurity profiling—are non-negotiable for exporters to regulated markets; our regulatory playbook maps registration timelines and typical mitigation levers.
Competitive landscape: what differentiates winners from followers
Our competitive analysis profiles established large-scale processors and regional specialists. Key archetypes include:
- Integrated pine-chemical majors (examples include long-established Western and European rosin specialists) — they leverage integrated feedstock platforms, broad product portfolios and global customer footprints to supply both commodity and formulated grades.
- Regional production champions (multiple manufacturers headquartered in China and India) — they are cost-competitive on standard grades, enjoy proximity to fast-growing formulators, and often lead on high-volume industrial emulsifier and tackifier demand.
- Specialty innovators — smaller players that compete on grade differentiation (e.g., high-heat resistant DPR, specific catalyst-grade fractions) and service models for adhesive and rubber formulators requiring narrow specification windows.
Representative supplier profiles included in the report provide practical vendor intelligence—headquarters and public-facing product positioning, common application strengths, and tactical considerations for engagement. We map each supplier against four decision-use criteria: feedstock access, processing capability, regulatory readiness, and commercial flexibility.
Practical report contents that drive 2026 decisions
We designed the report for hands-on use by procurement directors, product-line leaders, and corporate development teams. The deliverables include:
- Validated market-sizing and a demand-supply balance model with scenario toggles for feedstock shocks and demand elasticity.
- Supplier heatmaps and a buyer-supplier selection matrix that prioritize partners by risk-adjusted cost, technical capability, and compliance posture.
- Pricing-sensitivity and margin-protection models calibrated to current export price signals and common contract terms.
- CapEx and capacity-allocation guidance for downstream formulators considering in‑house hydrogenation/disproportionation or long-term offtake agreements.
- An M&A and partnership “hot list” built from a cross-reference of balance‑sheet indicators, strategic fit and proprietary deal-readiness scoring.
- A regulatory playbook that enumerates typical REACH considerations, recommended testing roadmaps, and practical mitigations for oxidative stability concerns.
Strategic recommendations for 2026
- Procurement: move from spot to blended contracting. Lock in a diversified mix of supply contracts—short-term volume at the spot level to capture price dips, complemented by medium-term offtakes with technical-service commitments for specialty grades.
- Formulation and R&D: prioritize stability and compatibility. Invest in formulation validation that quantifies the value of stabilized DPR grades (reduced oxidation, improved heat resistance) across your highest-margin applications. Small development wins in tackifier or emulsifier performance can translate directly into pricing power.
- Supply-chain resilience: map feedstock exposure. Create a feedstock risk register that flags high-exposure nodes (e.g., reliance on a single tall oil co‑processor or pulp mill) and identify alternative sourcing or strategic inventory buffers.
- M&A and partnerships: target bolt-ons and specialty capacity. Given the market’s mid-range concentration, acquisitive strategies should prioritize complementary technical capabilities and regional footprint rather than scale alone; small-to-midsize specialty producers often offer quicker earn‑outs and faster synergies.
- Compliance and market access: treat registration as market access infrastructure. REACH and comparable regimes are effectively infrastructure investments. Where your commercial strategy depends upon regulated markets, accelerate registration timelines and partner with suppliers who share or support registration obligations.
Case use: translating insight into a 12-month tactical plan
For procurement teams facing FY-26 budgeting cycles, our report includes a compact 12-month tactical playbook that sequences actions: immediate supplier risk assessment (Q1), contract renegotiation windows and hedging policy (Q2), technical validation of prioritized DPR grades (Q3), and a capex or partnership decision gate informed by a breakeven model (Q4). Each step is paired with the decision rule—what KPI movement would trigger escalation to executive approval.
Why PW Consulting’s DPR report matters for 2026
The DPR market is not a high-growth commodity play but a specialized materials ecosystem where incremental technical advantages, feedstock strategy, and compliance readiness determine value capture. The report translates market growth (base-year market size and a 4.19% CAGR through our forecast horizon) into operational imperatives: who to source from, what grades to prioritize, how to hedge raw-material exposure, and where to deploy capital. It bridges high-level industry analysis and execution-focused tools so that leaders can convert insight into measurable P&L outcomes in 2026.
Next steps
This preview is intended to demonstrate the strategic depth and practical utility of PW Consulting’s full Disproportionated Rosin Market report. To access the complete datasets, region/application segmentation, supplier scorecards and the downloadable tactical playbook, please visit our report page on the PW Consulting website. For bespoke briefings, scenario modeling or supplier diligence support tailored to your portfolio, our industry specialists are available for confidential engagements.
For detailed analysis of this topic, please visit the official page: Disproportionated Rosin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


