



PW Consulting: Residue Hydrodesulfurization Catalyst Market to Reach USD 5,343.01 Million by 2032, Expanding at a 4.61% CAGR (2026–2032)

Residue Hydrodesulfurization Catalyst Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting today releases an executive briefing drawn from our forthcoming Residue Hydrodesulfurization (R-HDS) Catalyst Market report, designed to equip senior refinery executives, catalyst suppliers, M&A teams, and procurement leaders with the strategic context they need to make high‑consequence decisions in 2026. Our analysis synthesizes multi-year market sizing, supply‑chain risk mapping, technology differentiation, and competitor positioning to translate market dynamics into executable options — while reserving the granular regional and product split tables for subscribers of the full report.
Residue Hydrodesulfurization Catalyst Market
Market snapshot: stability with structural upside
After a period of post‑pandemic adjustment, the R‑HDS catalyst market stabilized near USD 3.9 billion in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 4.6% across the 2026–2032 horizon. Under our baseline scenario this translates into a material expansion of installed catalyst demand and service activity through the early 2030s, driven by continued ultra‑low sulfur legislation, refinery residue conversion initiatives, and strategic upgrading of heavy feed processing capacity.
Residue Hydrodesulfurization Catalyst Market
These headline numbers mask important nuance: growth is not uniformly distributed by technology or geography, and industry participants will see differentiated margin trajectories depending on their exposure to feedstock quality, technology mix (fixed‑bed, ebullated‑bed, slurry), and access to secured raw material streams. PW Consulting’s report exposes these risk/reward asymmetries and converts them into practical decision pathways for 2026 investments.
Residue Hydrodesulfurization Catalyst Market
Why 2026 is a strategic inflection point
-
Regulatory pressure continues to be the primary demand lever. Global acceleration toward ultra‑low sulfur fuels sustains demand for high‑activity NiMo and CoMo catalysts engineered to process sour, high‑boiling residues.
-
Feedstock economics and refinery configurations are evolving. Refiners are increasingly evaluating residue conversion not only for compliance but as a route to higher‑value products and improved complex margin capture.
-
Supply‑side stresses are amplifying procurement risk. Notably, molybdenum spot markets experienced volatility in the order of 18–22% across a 12‑month window in 2025, exerting direct pressure on manufacturing margins for residue catalysts. Concentrated mine and processing footprints (notably in Chile and China) mean that upstream disruptions translate rapidly into price and availability shocks for catalyst makers and their downstream refinery customers.
Practical, decision‑ready content included in the full report
PW Consulting’s R‑HDS Catalyst Market report is organized to move readers from context to action. Key deliverables include:
-
Proprietary market sizing and multi‑scenario demand forecasts (2020–2032) that quantify the revenue and volume pathways for the market under differing regulatory, crude slate, and fuel demand assumptions.
-
Technology & performance benchmarking for fixed‑bed, ebullating‑bed, and slurry systems — including service life, catalyst replacement cadence, and feedstock tolerance matrices — presented as operational decision trees for refinery planners.
-
Supply‑chain risk analytics: heatmaps of raw material concentration, supplier capacity, and single‑point failures that translate into prioritized mitigation measures and purchasing lead‑time recommendations.
-
Commercial playbooks for procurement and contract design, covering indexation strategies (including raw material pass‑throughs), hedging structures, and long‑term offtake constructs that preserve gross margins while securing supply.
-
M&A and partnership screening tools: a scored target list and diligence templates for buyers seeking inorganic scale or technology access, and for licensors evaluating joint ventures in high‑growth regional markets.
-
Case studies and model clauses for catalytic lifecycle management, digital monitoring adoption (predictive activity decay), and retrofit sequencing to minimize downtime and optimize AR/VR desulfurization outcomes.
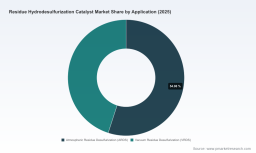
To preserve competitive value for subscribers, we deliberately exclude detailed regional and application split tables from this briefing; those granular decompositions are available in the full report and underpin the operational models and contract templates referenced above.
Competitive landscape: concentration, capabilities, and consolidation
The market is moderately concentrated: our analysis shows that the top three players account for a substantial share of revenue, and the top five control well in excess of two‑thirds of market value. This structure creates both entry barriers and strategic windows — incumbents benefit from scale and integrated licensing, while nimble challengers can carve niches via specialty formulations, service intensity, or geographic proximity to raw material sources.
Core players and strategic differentiators to watch:
-
Axens SA — A technology‑led supplier with a comprehensive fixed‑bed RDS portfolio and advanced catalyst engineering approaches aimed at maximizing HDS, HDN, and RFCC feed compatibility. Axens’ track record in fixed‑bed resid HDS positions it as a preferred partner for refineries targeting predictable service intervals and integrated licensor offerings.
-
Advanced Refining Technologies (ART) — Historically a leading specialist in both fixed and ebullated bed resid applications; the company’s capabilities now sit under the ownership of W.R. Grace & Co. following a November 2025 acquisition. This consolidation strengthens Grace’s foothold in resid hydroprocessing and creates scale synergies in R&D and commercialization.
-
Albemarle Corporation, Haldor Topsoe, Honeywell UOP, Johnson Matthey, Shell (Criterion), and BASF — Each brings differentiated strengths across R&D depth, formulation science, and co‑development with licensors. Their portfolios emphasize high‑activity CoMo and NiMo systems tailored for heavy, sulfur‑rich streams and for minimizing selective poisoning.
-
Sinopec and CNPC — State‑backed producers with vertically integrated supply chains and domestic scale. Their presence shifts competitive dynamics in regional markets where domestic sourcing, government procurement preferences, and local content rules matter.
For vendors and refinery leaders alike, the acquisition activity and concentration metrics imply two strategic plays in 2026: consolidate capability where scale and licensor alignment are critical (for example, fixed‑bed systems tied to licensed process units), and selectively partner or source locally for bespoke resid formulations and rapid response service contracts.
Cost and raw‑material dynamics: actionable risk mitigations
Price and availability for key inputs are a near‑term operational reality. In 2025, base metal hydrodesulfurization catalysts were transacted in a price band approximately between USD 28–45 per kilogram for standard grades, with specialty formulations for resid applications commanding premiums in the 40–60% range. When combined with molybdenum supply volatility, these input cost dynamics materially affect supplier margins and, unless contract structures adapt, can compress refinery economics as well.
Practical mitigations we recommend for 2026:
-
Implement a two‑tier procurement strategy: tactical spot coverage for short windows and hedged long‑term supply for critical stream continuity, with explicit passthrough mechanics for metal cost swings.
-
Pursue strategic alliances or equity partnerships with catalyst producers that include guaranteed allocation clauses and co‑funded buffer inventory to insulate operations from upstream shocks.
-
Invest in predictive catalyst health monitoring and advanced analytics to extend run length where safe, and to optimize replacement timing — this reduces total catalyst consumption and dampens exposure to input price volatility.
Actionable recommendations for 2026 decision‑makers
-
For refiners: prioritize feedstock flexibility investments and catalyst lifecycle analytics. Contracts should shift from fixed‑price, short‑term spot buys toward hybrid structures that share metal cost risk and incentivize supplier innovation in high‑durability formulations.
-
For catalyst suppliers: accelerate development of residue‑grade specialty formulations while strengthening upstream raw‑material security. Consider regional manufacturing offsets and aftermarket service bundles to lock in customers where proximity and service responsiveness matter.
-
For investors and M&A teams: target assets that offer either licensor alignment (to capture process economics) or differentiated proprietary formulations with demonstrable run‑length improvements. The market rewards scale in R&D and manufacturing but also premium margins for formulation leadership.
-
For regulators and industrial policy makers: consider how local sourcing policies and strategic stockpiles for critical minerals like molybdenum influence refinery resilience and national fuel security. Coordination between energy policy and mineral policy is now a practical necessity.
Next steps: how PW Consulting helps
PW Consulting’s full Residue Hydrodesulfurization Catalyst Market report provides the underlying datasets, interactive scenario models, supplier scorecards, contract templates, and a prioritized 18‑month execution roadmap tailored for executives ready to act in 2026. If your 2026 plan requires defensible choices around sourcing, technology selection, or inorganic growth in the R‑HDS space, our analysis converts market complexity into clear options and quantified outcomes.
For access to the full report, proprietary tables, and modelled scenarios (including the detailed regional and application splits omitted from this briefing), please visit the PW Consulting report page or contact our industry team for a briefing and tailored extract relevant to your portfolio.
PW Consulting — translating catalytic market intelligence into operational advantage for the refining sector.
For detailed analysis of this topic, please visit the official page: Residue Hydrodesulfurization Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


