



PW Consulting: Steel Idler Rollers Market Reaches USD 4,200 Million in 2025, New Report Reveals

Steel Idler Rollers Market 2026: Strategic Imperatives for C-Suites and Procurement Leaders
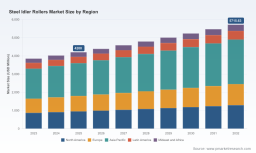
PW Consulting’s latest market brief on Steel Idler Rollers synthesizes five years of historical analysis (2020–2025) and a forward-looking forecast for 2026–2032 to equip executives with the evidence and playbooks required to make high-confidence decisions this year. At a macro level, the global steel idler rollers market reached approximately USD 4,200 Million in the base year 2025 and is projected to grow at a compound annual growth rate (CAGR) of 4.5% through 2032, reaching roughly USD 5,715 Million by the end of the forecast window. This briefing is designed as a strategic “trailer”: it surfaces the trends, risks, and levers that matter while reserving detailed subsegment tables and proprietary benchmarking for the full report.
Steel Idler Rollers Market
Why 2026 Is a Strategic Inflection Point
-
CapEx cycles and infrastructure programs are converging. Continued investment in ports, cement plants, and regional infrastructure—particularly in Southeast Asia and the Middle East—creates near-term demand pockets that suppliers and OEMs must convert into durable revenue.
Steel Idler Rollers Market -
Input-cost volatility raises margin risk. High-grade alloy steel price swings remain material—industry sources report year-over-year variability in the high teens—forcing manufacturers to revisit procurement, contract design, and product-cost engineering.
Steel Idler Rollers Market -
Regulation and safety continue to tilt purchasing decisions toward proven, durable solutions. Idler rollers’ role in worker safety, dust control, and compliance in heavy industries increases the value of lifecycle performance when clients select suppliers.
-
Operational digitization is moving from pilot to scale. Condition monitoring and predictive maintenance for conveyor components are rapidly becoming procurement priorities, changing the value proposition from parts-only to parts-plus-service.
What PW Consulting’s Report Delivers (Practical, Executable Content)
-
Validated market sizing and a 2026–2032 forecast model (USD, revenue unit: Million), including scenario runs for commodity shocks and infrastructure acceleration.
-
Segment frameworks by type, application and region with growth drivers annotated; our public summary intentionally withholds granular subsegment numbers to protect the competitive intelligence contained in the full dataset.
-
Supplier benchmarking: manufacturing footprints, lead-time mapping, quality-cost trade-offs, and spare-parts logistics analysis to support make-or-buy decisions.
-
Cost and margin playbook: bill-of-materials sensitivity, hedging templates for steel exposure, and price pass-through strategies for OEMs and distributors.
-
Technology and innovation roadmap: practical assessment of self-lubricating bearings, corrosion-resistant coatings, and smart idler integrations—what moves the needle on TCO and what remains experimental.
-
Aftermarket commercialization guide: warranty design, service-pack pricing, spare-part fulfilment, and commercial KPIs to drive recurring revenue.
-
M&A and partnership heatmaps: target archetypes, valuation sensitivity to raw-material volatility, and integration playbooks focused on aftermarket capture and sensor/analytics capabilities.
Key Strategic Recommendations for 2026
-
Hedge raw-material exposure proactively. Given the documented swings in alloy steel pricing, organizations should combine medium-term purchase agreements with indexed shorter-term buys and component-level cost reduction initiatives.
-
Prioritize service-led differentiation. Deploy pilot programs that bundle condition monitoring with spare-part fulfilment and SLAs; convert uptime improvements into premium pricing and longer contracts.
-
Modularize product design. Standardized shafts, bearings, and seals reduce SKU complexity, enable faster aftermarket fulfillment, and increase cross-sell potential across customer sites.
-
Invest selectively in digital sensors and edge analytics. Smart idler deployments (recent entrants are now moving from prototype to field trials) yield measurable reductions in unplanned downtime when paired with disciplined maintenance processes.
-
Reassess footprint and supplier strategies. Combine near-shore production for fast-moving SKUs with strategic low-cost sourcing for commoditized parts—while protecting quality through inspection regimes and supplier scorecards.
-
Price contracts for volatility. Introduce indexed clauses and passthrough terms in multi-year supply agreements to protect margins without sacrificing competitiveness.
Competitive Landscape — Who to Watch
The steel idler rollers market remains structurally fragmented: the three-largest players account for under a quarter of global revenue, while the top five capture roughly a third of market value. This dispersion creates opportunity for both scale players and agile regional manufacturers.
-
Rulmeca (Italy) — Global engineering-led supplier known for heavy-duty rollers and conveyor modules. Strengths: engineering brand, OEM-level relationships, and presence in ports and mining projects. Strategic implication: premium positioning in engineered installations.
-
Metso Outotec (Finland) — Mining-focused solutions provider emphasizing durability and low-maintenance designs. Strengths: deep mining domain expertise and aftermarket integration. Strategic implication: target for partnerships where value accrues to life-of-asset performance.
-
Continental (Germany) — Broad conveyor-systems footprint with integration across belts and rollers. Strengths: systems-level procurement advantages and cross-sell into industrial processing. Strategic implication: compete on systems economics, not parts alone.
-
ASGCO, Douglas Manufacturing, PPI, Martin Engineering, Superior Industries, Fenner Dunlop (USA / Australia / Netherlands) — These firms compete across heavy-industry applications with strong aftermarket channels and CEMA-aligned product lines. Strategic implication: aftermarket capabilities are a key differentiator.
-
HIC Universal (India), Melco (South Africa), GCS Conveyor (China) — Regional and cost-competitive manufacturers expanding export footprints. Strengths: price competitiveness and local-service models in emerging markets. Strategic implication: pressure on global players in price-sensitive segments.
Recent industry developments underscore two converging themes. First, materials and coatings innovations—self-lubricating bearings and corrosion-resistant finishes—are becoming commercially relevant for high-abrasion environments (industry reports, early 2026). Second, digitalization is accelerating: new smart idler products embedding real-time monitoring are moving from vendor press releases to customer pilots, signaling a shift in procurement criteria toward integrated condition-based maintenance.
Investment and M&A Signals to Monitor
-
Acquire niche aftermarket service providers with field networks and spare-part operations to accelerate cross-sell and shorten payback on CapEx.
-
Target sensor and analytics companies to capture data monetization opportunities and to lock in customers through predictive maintenance platforms.
-
Consider bolt-on acquisitions in low-cost production geographies to protect margin or to serve regional infrastructure programs more competitively.
How Strategic Leaders Should Use This Report in 2026
-
Procurement: use the cost-sensitivity models and hedging templates to redesign supplier contracts and to set KPIs that incorporate raw-material pass-throughs.
-
Operations: apply the manufacturing footprint analysis and SKU rationalization playbook to reduce lead times and working capital.
-
Commercial: pilot service bundles that combine condition monitoring, fast spares logistics, and performance-based pricing to increase wallet share.
-
Corporate Development: screen acquisition targets using the M&A heatmaps and integration checklists in the report to prioritize deals that accelerate aftermarket or digital capabilities.
-
Risk & Finance: run scenario models included in the report—covering commodity spikes, demand shocks, and accelerated infrastructure spending—to refine capital allocation and working-capital cushions.
Conclusion — The Strategic Edge in 2026
For executives deciding where to allocate capital, talent, and time in 2026, the Steel Idler Rollers market offers a classic combination of steady demand growth (4.5% CAGR) and structural change. Winners will be those that convert engineering credibility into service-led commercial models, shield margins from raw-material volatility, and deploy digital capabilities that demonstrably reduce customers’ total cost of ownership.
PW Consulting’s full Steel Idler Rollers Market report contains the granular regional and application breakdowns, company market shares, downloadable financial models, and operational playbooks referenced here. For procurement teams, product leaders, and corporate development executives seeking to turn the high-level strategic imperatives above into a 90- to 180-day operational plan, the complete dataset and tools are available on our report page.
For detailed analysis of this topic, please visit the official page: Steel Idler Rollers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


