



PW Consulting: Electrical Measurement System Market to Expand at 6.03% CAGR Through 2032, Propelled by Asia‑Pacific Demand

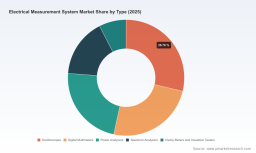
Electrical Measurement System Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
As organisations recalibrate capital allocation and product roadmaps for 2026, the electrical measurement system market presents a balanced mix of steady demand and structural disruption. PW Consulting’s latest market study shows the global market expanded through 2020–2025 and is forecast to continue growing at a compound annual growth rate (CAGR) of approximately 6.03% across 2026–2032, with the market size rising from the mid‑teens billion USD range in 2025 to an expected figure in the mid‑twenty billions by 2032. This briefing highlights the strategic implications of that trajectory, synthesises near‑term risks and opportunities, and summarises the practical, decision‑ready tools contained in the full report.
Electrical Measurement System Market
Why this matters for 2026 planning
Measurement equipment is both a bellwether and an enabler for capital‑intensive industries: test and measurement demand is driven by semiconductor cycles, automotive electrification, wireless infrastructure rollouts, and energy grid modernisation. In 2026 these drivers interact with non‑cyclical forces — supply‑chain fragility, regulatory intervention, and component scarcity — creating environments in which procurement timing, supplier selection, and product feature prioritisation materially affect P&L and time‑to‑market. For boards and executive teams, the key decision levers are:
Electrical Measurement System Market
- Aligning procurement cadence to product and test needs to avoid overstocks during a soft patch or shortages during surges;
- Investing selectively in modular, software‑defined test equipment that extends lifetime value and reduces upgrade cost; and
- Positioning partnerships and M&A to secure upstream criticality (components, firmware/IP) rather than only downstream distribution.
Market trajectory and what the headline numbers mean
PW Consulting’s forecast captures a resilient market: measured in USD, the industry demonstrates consistent expansion through the 2026–2032 forecast window. The mid‑single digit CAGR masks heterogeneity — pockets of rapid growth tied to next‑generation telecom test, EV powertrain validation, and grid‑edge monitoring coexist with slower volumes in legacy benchtop instruments. For strategic planning this means organisations should treat the market as structurally growing, but episodically volatile. Capital allocation that presumes steady linear growth risks either missed upside or inventory inefficiencies.
Electrical Measurement System Market
Key growth drivers (practical lens)
- Electrification of transportation and industrial processes — driving demand for power analyzers, high‑precision current/voltage measurement and automated test sequences for inverter and battery validation.
- Wireless and high‑speed digital ecosystems — necessitating RF, microwave and signal integrity instrumentation for design, certification and field troubleshooting.
- Energy transition and grid modernisation — creating long‑duration demand for deployed monitoring, power quality analysis, and preventive maintenance tools.
- Software and data monetisation — measurement platforms are increasingly sold as a bundle of hardware, analytics firmware and cloud services; lifecycle revenue models matter.
Supply chain, raw materials and regulatory dynamics to watch
2026 presents a markedly different upstream environment than 2020. Concentration of rare‑earth refining capacity, shifts in semiconductor export controls, and AI‑driven memory shortages have real, tangible impact on instrument makers. Practical takeaways for procurement and product teams:
- Expect episodic lead‑time extensions for analog ICs and passives; design teams should qualify alternate BOMs and increase modularity to decouple long‑lead subassemblies.
- Where magnets, precision components or bespoke RF modules depend on refined materials, scenario‑planning should assume periodic supply tightness tied to geopolitical actions.
- Regulatory changes in export controls can affect sourcing and aftermarket services — legal and trade teams should be engaged early in supplier selection and contract clauses.
Technology and product strategy implications
For R&D and product management leaders, the report emphasises three actionable shifts:
- Architect for software upgradability — instrumentation that decouples hardware refresh from feature updates preserves customer relationships and enables subscription revenues.
- Prioritise modularity and calibration ecosystems — field maintainability and traceable calibration remain differentiators for industrial and utility customers.
- Invest in automation and higher throughput test platforms — as semiconductor and EV testing needs scale, customers trade lower per‑unit speed for integrated automation and data‑centric validation.
Competitive landscape — what the major players are doing (and what it means)
The market displays moderate concentration: a group of well‑capitalised incumbents lead on technology breadth, brand and global service networks while a diverse set of regional and value players compete on price, niche features and fast local support. The practical competitive moves we observe and their implications are:
- Large instrumentation firms are leveraging their R&D budgets to integrate digital services and higher bandwidth capabilities, focusing on end‑to‑end validation stacks suitable for semiconductor and telecom OEMs. Expect premium pricing for end‑to‑end, software‑enhanced solutions.
- Established field‑tool specialists concentrate on ruggedisation, portability and broad distribution channels for industrial and utility customers — these capabilities sustain service revenue and aftermarket stickiness.
- Low‑cost entrants continue to pressure price‑sensitive segments, particularly in education and entry‑level industrial applications; incumbents respond by emphasising calibration, warranties and integrated service offerings.
- Scale plays and consolidation are visible in suites that bundle automated test platforms with software and data capture — vertical integration into semiconductor test systems remains an active strategic frontier.
Specific firm examples illuminate strategy archetypes: one segment leader focuses on high‑bandwidth R&D instruments and protocol‑centric solutions; other legacy handheld specialists double down on rugged field diagnostics and distribution partnerships; mid‑market companies compete with modular automated test systems and tailored power‑electronics rigs. For buyers, supplier selection should now be a multidimensional decision — balancing technical fit, software roadmap, supply reliability and service footprint rather than one‑dimensional price comparison.
Recent signals and near‑term events
Market participants should monitor product introductions and catalog refreshes that reveal supplier priorities. A February 2026 catalog release from a specialist highlighted ultra‑high sensitivity insulation testers targeting safety‑critical applications — a sign that precision and niche differentiation remain meaningful revenue drivers even as broader platforms evolve. Such product moves often presage follow‑on investments in calibration services and vertical‑market partnerships.
What PW Consulting’s report provides — practical contents for executives
The full Electrical Measurement System Market report is designed as an operational playbook for 2026. Key elements include:
- An integrated market model (2020–2032) with scenario sensitivity for component costs, lead times and regulatory regimes — enabling “what‑if” budgeting for procurement and capex committees.
- A supplier due‑diligence toolkit with templates for assessing manufacturing resilience, IP exposure, calibration service capacity and software roadmap maturity.
- Product‑level decision matrices that map instrument classes to buyer objectives: R&D speed, field robustness, total cost of ownership and recurring revenue potential.
- Deal playbooks for partnerships and M&A that identify value levers (access to channels, IP consolidation, vertical integration) and common valuation pitfalls in the sector.
- Actionable risk mitigation checklists covering alternative sourcing, inventory hedging and contractual clauses to address export controls and raw material shocks.
Recommendations for 2026 strategic moves
Based on the market outlook and practical constraints, we recommend executives focus on five priorities this year:
- Rebase supplier scorecards to include geopolitical and component‑specific risk metrics; require dual‑sourcing for critical subassemblies where feasible.
- Accelerate software enablement on existing installed bases to monetise lifecycle services and reduce sensitivity to hardware replacement cycles.
- Target partnerships for upstream control — whether through minority investments in niche component makers or long‑term supply agreements tied to joint roadmaps.
- Segment inventory strategy by instrument class: maintain buffer stock for long‑lead PCB assemblies while adopting just‑in‑time for commoditised mechanical parts.
- Evaluate selective M&A in automation and analytics capabilities — buyers can capture immediate synergies by bundling test hardware with data‑centric services.
How to use the report in boardroom and procurement cycles
Boards and executive teams should use the report as a rehearsal tool for 2026 decisions: run the scenario model in quarterly strategy reviews, require procurement to incorporate the supplier due‑diligence checklist before new contracts, and task product teams with a 90‑day plan to demonstrate at least one software‑driven upgrade path for a flagship instrument. For private equity and corporate development teams, the report’s deal playbooks and valuation caveats provide a faster pathway to identify and stress‑test targets.
Conclusion — the strategic posture for 2026
The electrical measurement system market in 2026 is not a binary bet on growth or decline; it is a portfolio of risks and opportunities. Companies that combine disciplined supply‑chain management, modular product design and a services‑centric commercial model will capture disproportionate value as the market expands at a mid‑single digit CAGR through 2032. The PW Consulting report gives decision‑makers the models, checklists and scenarios required to translate headline growth into defensible strategic moves — while deliberately withholding the granular segmentation tables and raw data that underpin those models until you access the full intelligence package.
Next steps
To access the detailed segmentation, regional and application breakouts, vendor benchmarking tables and the interactive forecast model, visit the PW Consulting report page. The full dataset and downloadable templates are available to subscribers and provide the operational detail necessary to execute on the recommendations outlined here.
For detailed analysis of this topic, please visit the official page: Electrical Measurement System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


