



PW Consulting: Ethyl Phenyl Acetate Market to Grow from USD 54.5 Million (Base Year 2025) to USD 76.43 Million by 2032 at a 4.95% CAGR — Asia Pacific Leads with USD 21.67M

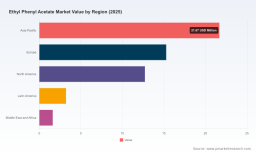
Ethyl Phenyl Acetate Market — 2026 Strategic Brief
PW Consulting’s latest market research release on Ethyl Phenyl Acetate (EPA) frames a precise, execution-oriented perspective for corporate decision-makers planning for 2026 and beyond. Our base-year analysis shows a global market that reached approximately USD 54.5 Million in 2025 and, under our central scenario, will expand at a compound annual growth rate (CAGR) of 4.95% through the 2026–2032 forecast window. By 2032 the market is projected to approach the mid-to-high seventies in million-dollar scale—evidence of steady, structurally supported growth rather than a short-term spike.
Ethyl Phenyl Acetate Market
Why this report is strategically valuable for 2026 decisions
- Translates macro trends into board-level choices: capital allocation, M&A screening, and product roadmap prioritization for fragrance, flavor, cosmetics, and pharmaceutical-intermediate portfolios.
- Delivers executable supply‑chain playbooks that reconcile raw-material risk with quality and regulatory requirements important to global customers and retail brands.
- Provides a decision-support toolkit: scenario-ready financial models, plant economics, supplier scorecards, and a regulatory compliance checklist tailored to ethyl phenyl acetate value chains.
Market dynamics — what executives must internalize
Three structural forces define the EPA landscape in 2026:
Ethyl Phenyl Acetate Market
- Feedstock intensity. Production economics are steeply dependent on phenylacetic acid and ethanol. Our cost-model benchmarking shows raw materials account for the lion’s share of operating expense in EPA manufacture—typically a large majority of direct production cost—making feedstock procurement the primary lever for margin management.
- Regulatory overlay. Phenylacetic acid is regulated in several jurisdictions as a controlled precursor because of diversion risks. In the United States, for example, it is listed under regulatory frameworks that demand enhanced customer vetting, record-keeping and, in some cases, licensing for handling and shipment. That compliance burden raises both direct costs and operational friction for manufacturers and distributors.
- Market concentration and supplier footprints. The EPA supply base blends multinational aroma and flavor houses, regional producers in Asia and India, and specialty natural‑ingredient suppliers. Market concentration metrics indicate a mid‑level aggregation—enough to create strategic corridors for price and quality leadership, yet sufficiently fragmented to enable agile entrants and contract manufacturers to capture niches.
What the report contains — practical outputs, not just insight
This is intentionally a practitioner’s dossier. Highlights include:
Ethyl Phenyl Acetate Market
- A calibrated market model (2020–2032) with scenario toggles for faster/slower demand, feedstock shocks, and regulatory tightening—designed to be used directly in financial planning sessions.
- End-to-end cost build-ups and a plant economics module based on industry-grade outputs. The model supports sizing runs from small-scale tolling to multi-thousand-tonne annual facilities and includes sensitivity to phenylacetic acid pricing, yield variation, and utility cost assumptions.
- Supplier mapping and an actionable due-diligence checklist that captures technical capabilities, certification footprints (e.g., Kosher/Halal, FCC/Food Grade, GC purity), and logistics resiliency scores.
- A compliance & controls playbook for handling regulated feedstocks—covering customer screening, record retention, audit triggers and international transport considerations.
- A go-to-market and procurement playbook for both buyers and sellers: contract structures (pricing collars, indexation clauses), specification hedges, and co-development frameworks for natural vs. synthetic variants.
- An M&A screening matrix and a prioritized short-list of acquisition/joint-venture archetypes that deliver vertical capture, geographic access, or specialty-grade differentiation.
Competitive landscape — how to read supplier intent and capability
The supplier universe for EPA can be segmented by strategic position rather than by raw market share alone:
- Global aroma and flavors majors — firms with broad formulation portfolios and integrated regulatory/commercial teams. These players compete on specification breadth, global logistics, and integrated customer service for fragrance and flavor houses.
- Regional manufacturers and distributors — lower-cost producers and worldwide distributors that supply technical and industrial grades, often serving regional blends, contract manufacturing, and local flavor houses.
- Specialty natural and isolate suppliers — firms that offer natural-label variants, Kosher-certified natural isolates, and niche cosmetic-grade materials that command a price premium in premium personal-care and natural-food markets.
Representative vendors profiled in our study include a mixture of each archetype: global specialty-chemicals houses and aroma majors that provide high-purity and branded aroma molecules; regional and contract producers with scale in Asia and India; and small-to-midsize specialists focused on natural isolates and cosmetic-grade material supply. Our benchmarking assesses each firm on production capability, certification & compliance posture, quality control, and customer-service KPIs—enabling buyers to craft dual-source and strategic-supplier relationships aligned to their risk appetite.
Recent developments that alter the 2026 playing field
- Plant-scale feasibility content has become more operationally tangible: a recent plant project report (March 2026) provides a template for 1,000–3,000 MT/yr setups, with capex and opex reference models. That work is directly integrated into our plant economics module to help firms evaluate near-term backward integration versus long-term off-take agreements.
- Phenylacetic acid supply and pricing: global production and pricing dynamics in 2025 crystallize the feedstock base. Firms that misjudge feedstock sourcing risk sudden margin compression; those that lock-in diversified sources and hedging strategies preserve negotiating flexibility.
- Heightened control measures for precursor chemicals are driving demand for enhanced compliance automation—buyers are increasingly favoring suppliers that demonstrate institutionalized customer-vetting, traceability, and audited logistics partners.
Opportunities and principal risks to weigh in 2026
- Opportunities:
- Premiumization and naturalization trends in fragrances and flavors create demand for high-purity and natural-label EPA variants.
- Contract manufacturing and tolling models present attractive near-term routes to secure supply without full-capex exposure.
- Targeted backward integration can be accretive where feedstock access and regulatory compliance can be internalized at scale.
- Risks:
- Regulatory tightening around precursor chemicals increases compliance cost and can slow time-to-market for new contracts.
- Feedstock price volatility—given its dominant share of production cost—can swiftly erode realized margins absent indexation or hedging clauses in contracts.
- Geo‑logistical and trade disruptions in major producing regions can exacerbate short-term supply tightness.
90‑day executive action plan
- Run the report’s sensitivity module against your current procurement book to quantify EBITDA exposure to a range of phenylacetic acid price scenarios; decide whether to adopt collars, forwards, or strategic storage.
- Complete a supplier audit focused on compliance credentials for regulated feedstocks—prioritize counterparty upgrades where KYC or recordkeeping gaps exist.
- Initiate a cost‑to‑build quick scan using the embedded plant economics module if vertical integration is on the strategic table; use the 1,000–3,000 MT/yr template as a reference starting point.
- Establish dual-sourcing agreements split by grade and certification (industrial vs. food/fragrance/cosmetic) to mitigate single-point-of-failure risks without sacrificing quality alignment.
- Prioritize M&A or JV targets from the report’s screening matrix for near-term bolt-on acquisitions that deliver feedstock security, regional access, or specialty-grade capabilities.
PW Consulting’s Ethyl Phenyl Acetate Market report is designed as a strategic instrument—combining market sizing, regulatory intelligence, supplier benchmarking, and hands-on financial tools—to move teams from diagnosis to decisive action in 2026. For practitioners seeking the granular segmentation, proprietary scenario outputs, and downloadable models referenced here, the full dossier and interactive workbooks are available through our report portal. PW Consulting stands ready to support tailored workshops, integration due diligence, and bespoke cost-model customization to convert this intelligence into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Ethyl Phenyl Acetate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


