



PW Consulting: Mango Kernel Fat Market Set to Expand at 7.89% CAGR During 2026–2032

Mango Kernel Fat Market 2026: Strategic Intelligence for Executive Decision‑Making
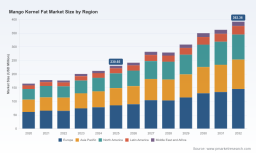
PW Consulting today releases a strategic preview of our in‑depth Mango Kernel Fat Market research, framed to inform capital allocation, sourcing strategies, product innovation, and regulatory compliance decisions for 2026 and beyond. Our model shows the global mango kernel fat market expanding from an estimated USD 230.65 Million in the 2025 base year to roughly USD 392.36 Million by 2032, representing a compound annual growth rate (CAGR) of 7.89% across the 2026–2032 forecast window. This acceleration reflects converging demand drivers in cosmetics, specialty food, and nutraceutical segments, paired with structural supply adjustments in key producing geographies.
Mango Kernel Fat Market
Why this matters for 2026 planning
-
Timing and scale: With a near‑term uptick projected in 2026, buyers and investors must decide now whether to move from opportunistic purchasing to contractual sourcing or capacity investment.
Mango Kernel Fat Market -
Product adjacency: Mango kernel fat’s positioning as a cocoa butter alternative and its favorable emollient profile amplify its strategic value for formulators seeking ingredient differentiation and cost optimization.
Mango Kernel Fat Market -
Supply‑chain transformation: Traceability and sustainability credentials are shifting from ‘nice‑to‑have’ to procurement prerequisites, materially affecting supplier selection and margin management.
What the full report delivers (practical, operational outputs)
-
Market sizing and validated forecast model (base year 2025; historical window 2020–2025; forecast 2026–2032) with scenario analysis that isolates demand shocks, feedstock variability, and substitution dynamics.
-
End‑to‑end supplier mapping and capability profiles—including processing technologies, grade portfolios (refined, semi‑refined, unrefined, organic), and commercial readiness—ranked by fit for cosmetics, food, and pharmaceutical applications.
-
Procurement playbook: contract structures, indexation and hedging approaches for fat‑based commodities, recommended quality and traceability clauses, and sample RFP language for supplier selection.
-
Technical appendix: fractionation and solvent processing economics, CAPEX/OPEX benchmarks for greenfield units, and integration pathways for processors considering verticalization.
-
Regulatory & compliance dossier: international HS code treatment, certification pathways (organic, fair trade, and specialty cosmetic grades), and practical steps to secure market access in regulated food and personal care industries.
-
Investment and M&A playbook: target screens, valuation sensitivities tied to capacity utilization and traceability credentials, plus post‑deal integration checklists.
Note: this preview intentionally omits proprietary sub‑segment datapoints (regional and application splits, and specific supplier revenue shares) to preserve the curated value of the full dataset available in the complete report.
Competitive landscape — strategic lens
-
Manorama Industries Limited (India): A vertically networked specialist with deep village‑level sourcing and traceability programs. Recent capacity expansions—including new fractionation capability and a strategic subsidiary to process kernels in West Africa—signal an intent to secure feedstock and move up the value chain. For buyers, Manorama’s integration model illustrates a supplier archetype that reduces provenance risk but requires rigorous commercial diligence on exclusivity and offtake terms.
-
European processors (examples: Gustav Heess, Henry Lamotte): These players emphasize consistency, certification capability, and customer service for B2B formulators. Their competitive edge rests on quality assurance systems and logistical reach into EMEA cosmetic and food manufacturers.
-
U.S. specialty ingredient firms (examples: Hallstar Biochemica, Jarchem, Alzo): These firms package mango kernel fat into formulation‑ready grades and co‑develop with personal care brands, focusing on high‑margin cosmetic applications and technical support for product developers.
-
Organic and cold‑press specialists (examples: All Organic Treasures, Ekologie Forte): Niche players that capture the premium natural and organic segments. Their product premium is attractive to natural personal care brands but requires a supply base that withstands seasonal variability.
-
Network suppliers and regional traders: A cohort of smaller suppliers and aggregators operate near production hubs, enabling just‑in‑time deliveries but often lacking the certification and processing depth demanded by large formulators.
Across the competitive set, market concentration is moderate: the top three and top five firm groups collectively represent meaningful but not prohibitive shares of global revenue, creating both consolidation opportunities and room for new entrants with targeted product or geographic strategies.
Supply dynamics and raw‑material realities
-
Mango kernels are a byproduct of the global fruit processing industry—feedstock availability is strongly seasonal and geographically concentrated in tropical producing regions. Kernel oil content commonly ranges in the mid‑single digit to high‑teens percentage of kernel mass, which has implications for raw material throughput planning and logistics economics.
-
Processing pathways vary from cold‑pressed, solvent extraction, to post‑extraction fractionation; each route yields different grades, cost bases, and suitability for industries with divergent purity requirements (e.g., food vs. cosmetics vs. pharmaceuticals).
-
Regulatory framing matters: international trade uses specific HS codes for fixed vegetable fats and oils, and buyers increasingly require documented chain‑of‑custody and relevant organic or sustainability certifications before qualifying suppliers for strategic contracts.
-
Functional adjacency: mango kernel fat’s fatty‑acid profile makes it a viable cocoa butter alternative in certain formulations—this creates both demand upside from confectionery formulators and substitution risk dynamics tied to cocoa pricing and food‑grade regulatory approvals.
Risk profile & strategic mitigations for 2026
-
Feedstock volatility: harvest variability and processing seasonality can produce price spikes. Buyers should evaluate blended procurement strategies combining long‑term offtake with spot purchases and invest in inventory buffers for peak seasons.
-
Concentration and supplier dependence: a moderate share of supply sits with a limited supplier set. Mitigation options include dual‑sourcing, supplier development programs, and targeted investments in partner facilities to secure capacity.
-
Quality and specification risk: differences among refined, semi‑refined, and cold‑pressed grades mean that technical acceptance protocols and in‑market testing must be contractual prerequisites.
-
ESG and reputational risk: traceability, labour practices, and community impacts are now material procurement criteria. Programs that invest in supplier training, local value creation (e.g., women self‑help groups), and independent auditability reduce compliance and brand risks.
-
Regulatory shifts: food and cosmetic regulatory regimes can change labeling or allowable ingredient lists. An agile compliance capability—covered in our report—is essential for timely market access.
Immediate strategic moves for executives
-
Procurement leaders: initiate supplier qualification pilots with at least two differentiated suppliers (one integrated processor and one certified organic/cold‑press specialist) to stress test cost, quality, and traceability assumptions.
-
R&D and formulation teams: prioritize application testing for mango kernel fat as a performance and cost lever—focus on sensory outcomes, oxidative stability, and regulatory labeling implications.
-
Corporate development: scan for acquisition targets among processors with under‑utilized fractionation capacity or advantaged feedstock access; such assets can compress time‑to‑market for forward‑integrated strategies.
-
Sustainability officers: embed supplier development metrics into ESG reporting and build partnerships with source communities to harden supply chains against reputational shocks.
How PW Consulting supports 2026 execution
-
Custom market entry and supplier selection engagements backed by our quantitative forecast and supplier capability databases.
-
Commercial due diligence and integration playbooks for strategic M&A or JV structures, including valuation sensitivity to capacity and certification premiums.
-
Procurement transformation projects that implement contracting templates, hedging strategies, and traceability clauses tailored to fixed‑fat commodities.
-
Operational advisory for processing investments—technical benchmarking, CAPEX/OPEX modelling, and phased commissioning plans to optimize utilization and margin.
Our full Mango Kernel Fat Market report contains the complete datasets, supplier scorecards, and a downloadable procurement checklist designed for rapid deployment. This preview is intended to surface the principal strategic imperatives and operational levers that will define competitive advantage in 2026. To access the complete dataset, segmented analytics, and the actionable supplier shortlists that power execution, please visit PW Consulting’s research portal and download the full report.
For detailed analysis of this topic, please visit the official page: Mango Kernel Fat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


