



Sweet Surge: PW Consulting Forecasts New Chinese Pastries Market to Reach USD 14.21 Billion by 2025

New Chinese Pastries Market 2026: Strategic Outlook and Decision-Ready Intelligence
Executive snapshot
PW Consulting’s New Chinese Pastries Market report frames 2026 as an inflection year for producers, retailers, ingredient suppliers, and investors targeting a resilient, fast-evolving category at the intersection of heritage and convenience. After robust expansion in the first half of the decade, the market size grew from roughly USD 8.6 billion in 2020 to about USD 14.2 billion in 2025. Our forecast model shows continued momentum: the market is set to reach roughly USD 15.6 billion in 2026 and to approach USD 25.9 billion by 2032, reflecting a 2026–2032 compound annual growth rate (CAGR) of 8.42%. Yet beneath headline growth lies a highly fragmented competitive structure and a changing regulatory and cost environment that will materially reshape winners and losers in the coming 18–36 months.
New Chinese Pastries Market
Why 2026 is a decisive planning horizon
Three linked dynamics make 2026 the year to convert strategic hypotheses into executable plans. First, regulatory updates (notably expanded nutrition labeling and mandatory allergen/warning requirements) create immediate product-compliance workstreams for any firm selling prepackaged pastries. Second, raw-material cost volatility and trade policy distortions are already altering sourcing economics for flour- and rice-based formats. Third, shifts in consumption contexts and channel economics — from specialty batters and frozen convenience to premium gifting — are driving SKU rationalization and new-format innovation. For C-suite teams and category leaders, delaying structural decisions until 2027 increases the risk of forced adaptation (and margin erosion) as new compliance dates and trade measures come into force.
New Chinese Pastries Market
Market trajectory and macro drivers
Our analysis synthesizes macro demand drivers and micro-level dynamics to explain both the pace and pattern of growth. Consumption is being lifted by continued urbanization and rising at-home indulgence, while foodservice recovery and premium gifting occasions drive high-value seasonal spikes. On the supply side, manufacturing automation, frozen-chain distribution, and ingredient innovations (stable rice fillings, tailored shortening blends, preservative-reduction technologies) are reducing time-to-market for new SKUs and enabling retail-ready frozen solutions for national roll-outs.
New Chinese Pastries Market
At the same time, the category is being re-priced by input-side realities: domestic wheat prices and import tariffs, updated customs and cold-chain documentation requirements for imports, and heightened public scrutiny of sugars, salts, and oils. Collectively these forces change the calculus for SKU economics, trade-offs between localization and centralized production, and packaging investments to protect freshness and demonstrate compliance.
Competitive landscape: fragmentation, incumbents, and capability gaps
The New Chinese Pastries market remains structurally fragmented. Market-concentration metrics indicate that the three largest firms account for under one-fifth of industry revenues, and the top five together capture roughly a quarter — an environment that supports both continued private-label penetration and roll-up strategies for strategic acquirers.
- Dali Foods Group : A broad-based bakery leader with scale advantages in distribution and export channels. Dali’s strength is in portfolio breadth and channel reach; its strategic choices around premiumization and health-forward reformulations will be a bellwether for large-scale players.
- Shenyang Toly Bread : Known for convenience-oriented baked goods, Toly’s competitive advantage lies in rapid product iteration and cost-efficient bread lines. Its next moves — automation investments, frozen-format expansion, or co-packing partnerships — will signal how mid-tier manufacturers defend margin in a higher-cost environment.
- Foshan Xinfengbei (Fengbeibaking) & Shanghai Mingxiang : Specialists in frozen and classic pastry formats, both firms typify the growing niche of frozen CPG solutions that enable national retail distribution with lower logistics risk. Their playbooks will matter for retailers seeking consistent seasonal supply.
- Jiangsu Xinxin & Sichuan Chuanxiang : These firms illustrate two profitable routes: snack-driven product extensions and strong regional taste profiles (including spicy and savory innovations). Expect strategic licensing or co-branding with larger distribution partners.
- Fujian producers & Imperial Patisserie : Regional specialists and premium artisans continue to capture gifting and seasonal demand with differentiated recipes and branding. Imperial Patisserie’s award-winning premium positioning is a useful case study in pricing power and export potential.
- Yamazaki Baking : As an international operator adapting Western-style buns to local tastes, Yamazaki exemplifies how foreign incumbents can leverage supply-chain sophistication and R&D muscle to capture hybrid-format segments.
Recent industry inflection points to watch
- Trade shows such as Bakery China (2025 and the 2026 edition) are accelerating ingredient and equipment dissemination — expect a wave of processing and packaging innovations introduced at scale after these events.
- Wheat and flour economics: with wholesale flour prices and protectionist tariffs influencing source decisions, manufacturers face a binary choice between local sourcing and higher landed costs for imports, each with distinct margin implications.
- Regulatory timing: new labeling standards and mandatory allergen and warning declarations require roadmap investments across product development, packaging, and marketing functions, with full enforcement timelines accelerating change management needs.
What the PW Consulting report contains: operational, commercial, and financial tools
Our report is built as a decision-support toolkit for 2026 planning cycles. It combines category-level forecasts and scenario models with hands-on, implementable modules, including:
- Market sizing and scenario-based forecasts (base, upside, and stress cases) to align corporate planning with realistic demand curves and margin pressure scenarios.
- Regulatory-impact playbooks: compliance checklists, label re-design templates, and a phased implementation calendar tied to enforcement milestones.
- Supply-chain stress tests: sourcing heat maps, tariff sensitivity analyses, and cold-chain investment calculators to quantify trade-offs between local production and centralized manufacturing.
- SKU rationalization frameworks and SKU-pricing elasticity models designed to guide SKU pruning, limited-edition launches, and premium-lane expansions without eroding core sales.
- Channel acceleration blueprints for specialty stores, frozen retail formats, and digital grocery, including partnership negotiation principles and pilot metrics for e-commerce scale-up.
- An M&A and partnership playbook: target profiling, value-capture levers, and integration checkpoints for buyers seeking geographic or capabilities scale.
Strategic imperatives for 2026 decision-makers
For senior leaders, the report translates macro trends into concrete strategic imperatives:
- Prioritize compliance-first reformulation and label redesign now to avoid last-minute cost shock when enforcement dates arrive. Regulatory delays are unlikely; planning windows are short.
- Reassess sourcing strategies under multiple flour-price and tariff scenarios. Where feasible, secure multi-year contracts and diversify grain suppliers to reduce single-point exposure.
- Invest selectively in frozen production and cold-chain competencies to unlock national retail distribution and foodservice channels with predictable quality and lower shrink.
- Allocate R&D toward sugar/salt reduction technologies and clean-label ingredient systems that preserve texture and shelf-life; this will be a competitive differentiator in a health-conscious market.
- Adopt a portfolio approach to channel growth: use specialty stores and premium gifting to protect margin while scaling repeatable frozen SKUs through e-commerce and supermarket partnerships.
- Explore consolidation plays: with low top-five concentration, savvy consolidators can build scale quickly by aggregating regional champions with complementary capabilities.
How to use this intelligence in budgeting and board cycles
Translate the report’s scenarios into a short list of board-ready options: a “protect and defend” capital plan focused on compliance and cold-chain; a “scale and premiumize” plan that reallocates marketing and capex toward premium SKUs and gifting; and a “consolidate and integrate” plan for acquisitive growth. Each option includes a set of trigger events and KPIs — for example, regulatory enforcement milestones, input-cost thresholds, and pilot conversion rates — that should be embedded in quarterly reviews to avoid reactive decision-making.
Where the report adds unique value — and what you’ll find on our site
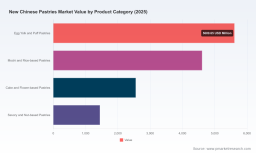
PW Consulting’s report offers more than narrative direction: it provides executable workstreams, reproducible financial models, and a private benchmarking dataset. To respect the “trailer” approach of this release, we have deliberately withheld granular regional and product-split tables from this summary. The full report and interactive dashboards available on our site include detailed segment-level breakdowns, SKU-level demand curves, retailer win-rate matrices, and downloadable compliance templates that are essential for operational planning.
Next steps
For executives preparing 2026 budgets or revising multi-year roadmaps, the immediate actions are clear: download the full report to access segment-specific forecasts and models; run the report’s tariff and raw-material scenarios against your P&L; and queue regulatory-compliance upgrades into your product-development timeline. PW Consulting is available to run a focused, 6-week strategic sprint to translate findings into an executable 2026 operational plan, complete with costed initiatives and KPI dashboards.
Contact and access
Access to the full New Chinese Pastries Market report, detailed appendices, and scenario models is available through PW Consulting’s report portal. For bespoke advisory support — including scenario workshops, procurement renegotiation playbooks, or M&A target screening — our industry team is ready to partner with your executive and operational leads to accelerate value capture in 2026.
For detailed analysis of this topic, please visit the official page: New Chinese Pastries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


