



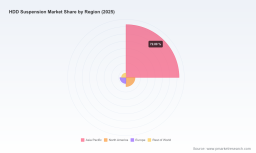
PW Consulting: HDD Suspension Market to Expand at 4.15% CAGR, Reach USD 638.1M by 2032 as Asia‑Pacific Dominates with USD 349.9M

Hdd Suspension Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
As enterprises and OEMs reassess storage supply chains and product roadmaps for 2026, the HDD suspension market is reasserting its strategic significance. PW Consulting’s latest market research—grounded in a 2020–2025 historical analysis and a 2026–2032 forecast horizon—provides an actionable, executive-grade view of where the market stands, where it is headed, and how procurement, product, and M&A leaders should respond.
Hdd Suspension Market
Headline macro view
-
The global HDD suspension market registered measured growth through the 2020–2025 historical window, arriving at a base-year size of USD 480.0 Million (base year 2025).
Hdd Suspension Market -
Our forecast pathway anticipates steady expansion across 2026–2032, underpinned by continued demand for high-capacity enterprise drives and incremental innovations in micro-actuator integration. The modeled CAGR for the forecast period is 4.15%.
Hdd Suspension Market -
By 2026 the market is projected to cross the ~USD 510 Million mark, and by the end of the forecast horizon it approaches roughly USD 640 Million—reflecting both product up-tiering and constrained component supply cycles.
-
Market structure is highly concentrated: the leading three suppliers command a dominant share of industry revenues, and the top five are close to capturing the vast majority of the market. This concentration amplifies supplier risk but also creates clear strategic counter-parties for partnerships and capacity agreements.
Why this report matters for 2026 decision-making
-
Strategic procurement: Suppliers with integrated micro-actuator capabilities and cleanroom-certified manufacturing are becoming non-negotiable for enterprise-class HDD programs. Delays or missteps in qualifying these suppliers will create multi-quarter lead-time exposures.
-
Product roadmaps: As platter densities and PMR/advanced write methods evolve, suspension designs must balance stiffness, signal integrity, and micro-actuator placement. Procurement and product leaders need scenario-based cost and qualification models to avoid last-minute redesigns.
-
Geopolitical resilience: Export controls and equipment restrictions have real operational impacts on production footprints. Strategic decisions in 2026 on localization, dual-sourcing, and tooling choices will materially affect unit economics and time-to-market through 2028.
What the PW Consulting report contains — practical, executable outputs
-
Concise market sizing and revenue trajectory (2020–2025 history; 2026–2032 forecast) with scenario bands that stress-test volume, pricing, and raw-material shocks.
-
Supplier scorecards: manufacturing readiness, technology IP footprint, qualification timelines, geographic risk, and a commercial benchmark matrix to support RFP/RFQ shortlists.
-
Technology readiness and disruption maps covering micro-actuators (PZT and alternatives), flex-circuit evolution, and advanced gimbal architectures—each mapped to time-to-production and cost delta.
-
Procurement playbooks: hedging templates for stainless steel strip exposure, inventory and safety-stock models calibrated to extended lead-times for key components, and negotiation levers for captive versus outsourced tooling.
-
Manufacturing footprint decision support: site-selection model incorporating labor-cost curves, cleanroom compliance (ISO 14644-1), capital equipment accessibility, and export-control overlays.
-
M&A and partnership screening tools: value-creation templates that quantify synergies from vertical integration (actuator suppliers, flex-circuit houses) and bolt-on targets in precision metal and assembly.
-
Executive dashboards and board-ready slide packs designed to accelerate informed decisions within 30–60 days.
Competitive landscape — who matters and why
-
NHK Spring Co., Ltd. (Yokohama, Japan) — A leading global supplier of HDD suspensions with advanced gimbal assemblies and flex suspensions tailored to enterprise platforms. NHK’s recent product introduction targeting 30TB+ PMR HDDs demonstrates an aggressive move to secure high-density enterprise supply chains through tighter micro-actuator integration.
-
Hutchinson Technology Incorporated (HTI) (Hutchinson, MN, USA) — Specializes in suspension assemblies and has been extending capabilities into PZT-enabled and wire-suspension designs. The company’s recent qualification wins for major enterprise HDD platforms underscore its strategic relevance for data-center OEMs seeking validated supply continuity.
-
Tatsuta Electric Wire & Cable Co., Ltd. (Osaka, Japan) — A prominent flex-circuit and lead-wire suspension supplier actively upgrading designs to support higher per-platter densities. Its recent technology update signals readiness to support both client and near-enterprise HDD programs.
-
Suzhou Jinfu Precision Industry Co., Ltd. (Suzhou, China) — A regional manufacturer producing load beams and base plates for OEMs. Localized capacity providers like Jinfu remain critical partners for cost-sensitive client drive segments and as contingency sources for global supply strategies.
-
Nippon Micro Metal Co., Ltd. (Osaka, Japan) — Supplies precision metal parts—including swagers and limiter components—forming the microscopic tolerances that distinguish high-yield suspension lines from commodity alternatives.
Recent vendor moves and what they signal
-
October 2025 — NHK Spring launched a next-generation suspension for 30TB+ PMR HDDs with enhanced micro-actuator integration, pointing to supplier-led product leadership and a push to capture premium enterprise program share.
-
June 2025 — Hutchinson secured qualification for suspension assemblies in large enterprise HDD platforms, validating its technology roadmap and strengthening its bargaining position in multi-year supply negotiations.
-
November 2024 — Tatsuta announced flex suspension upgrades for higher per-platter densities, signaling client HDD suppliers are continuing incremental density upgrades that sustain a sizable addressable market for several years.
Market dynamics and risk signals to monitor
-
Raw material pressure: Stainless steel strip pricing has experienced meaningful upward pressure due to supply-chain disruptions. Procurement teams should model a scenario of sustained premium on strip pricing and incorporate index-linked clauses where feasible.
-
Regulatory compliance: ISO 14644-1 cleanroom standards are mandatory for suspension manufacturing. Compliance is not optional—capital investments and audit-readiness will determine qualification timelines and cost per qualified lot.
-
Geopolitical constraints: Export controls on advanced manufacturing equipment have already affected production lines in some jurisdictions. Firms should assess the real-world impact on tool availability, retrofitting timelines, and potential need for backup lines in alternative jurisdictions.
-
Labor market tightness: Precision assembly labor costs in certain Southeast Asian hubs have risen, driven by skilled-worker shortages. This changes the calculus on automation versus manual assembly investments, especially for mid-volume programs.
-
Component lead-time risk: Lead times for PZT micro-actuators widened materially amid global semiconductor constraints. The prudent operator assumes extended cycle-times and embeds dual-sourcing for critical actuator elements.
Strategic playbook for 2026 — concrete moves
-
Prioritize supplier qualification timelines: Identify one tier-1 and one tier-2 qualified supplier for every enterprise-grade platform. Use short-cycle qualification pilots to reduce time-to-live for new suspension architectures.
-
Hedge raw-material exposure: Negotiate index-linked contracts for stainless steel strip, and evaluate limited forward-purchase programs for firms with sufficient working-capital flexibility.
-
Mitigate actuator scarcity: Rebalance inventory policies for PZT-based parts, increase safety stocks where economically justified, and accelerate development of alternative micro-actuator sources or design variants tolerating longer lead times.
-
Re-evaluate footprint and tooling strategies: Where export controls or equipment access constrain production, run a parallel-case site selection exercise emphasizing equipment availability, certification timelines, and cross-border logistics.
-
Leverage vendor concentration: Given the high market concentration, pursue multi-year collaboration frameworks (volume commitments, joint tooling investments, co-development agreements) with leading suppliers to secure preferential allocation.
-
Embed compliance and quality guardrails: Invest in cleanroom modernization and audit-readiness to compress qualification gates and reduce time-to-volume for new designs.
How PW Consulting supports 2026 execution
-
We provide stackable engagement modules: from a focused 30-day supplier risk-and-opportunity sprint, to a full-scale 12-month implementation program that includes tooling negotiations, workforce upskilling, and joint development governance.
-
Clients receive: supplier negotiation playbooks, validated cost models, live supplier scorecards, and portfolio-level scenario dashboards aligned to quarterly procurement cycles.
-
Our team pairs industry practitioners (ex-OEM procurement and process-engineering leads) with data scientists to translate market signals into procurement levers and P&L impacts.
Trailer note — what the public brief omits
-
This executive brief intentionally surfaces high-confidence market trajectories, supplier dynamics, and tactical recommendations while withholding the granular subsegment revenue schedules, regional and application breakdowns, and supplier-by-supplier contractual leverage matrices that form the core of our paid offering.
-
For procurement teams and corporate strategists who need the detailed sub-segment curves, full regional and application splits, and the proprietary supplier-risk scoring model that drive ROI-calibrated decisions in 2026, the comprehensive report and supporting data package are available through PW Consulting’s report portal.
Decision windows in 2026 will be defined by the speed at which organizations act on supplier qualification, component risk mitigation, and footprint resilience. PW Consulting’s HDD Suspension Market report is designed to convert those strategic imperatives into executable programs. To access the full dataset, supplier matrices, and a tailored briefing for your leadership team, visit PW Consulting’s market report page or contact our industry practice leads for a private briefing.
For detailed analysis of this topic, please visit the official page: Hdd Suspension Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


