



PW Consulting: Handheld Microphones Market Poised for 5.42% CAGR During 2026–2032, New Report Reveals

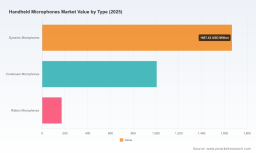
Handheld Microphones Market — PW Consulting Strategic Brief for 2026 Decisions
PW Consulting’s latest market study on handheld microphones delivers a high-impact, decision-ready briefing for executives planning product, supply chain, and M&A moves in 2026. The global market reached USD 2,845.5 Million in 2025 and, under our base forecasting assumptions, is expected to expand at a 5.42% CAGR through the 2026–2032 horizon, reaching approximately USD 4,117.36 Million by 2032. These headline numbers frame a market that is large enough to matter to audio incumbents and newcomers alike, yet sufficiently fragmented to reward targeted strategic plays.
Handheld Microphones Market
Why this brief matters for 2026
- Rapid technology migration (wireless systems, digital RF, integrated IEM compatibility) is reshaping product roadmaps and aftermarket value streams.
- Supply-side shocks and regulatory inflection points in 2024–2026 are forcing manufacturing, sourcing and compliance choices that will lock cost positions for years.
- Market concentration is moderate: the top three vendors do not dominate the landscape, leaving room for acquisition-driven scale or product-led disruption.
- Our report is designed as a practical playbook — not just a forecast — so leaders can convert insight into near-term actions with quantified risk/reward trade-offs.
Headline, data-driven takeaways
After recovering from pandemic-era distortions, handheld microphone demand shows steady, mid-single-digit growth driven by the convergence of three durable trends: continued professional live-audio recovery, accelerated adoption among content creators and broadcasters for wireless digital solutions, and a premiumization trend in higher-fidelity condenser and modular handhelds. PW Consulting’s base model projects the market to grow from USD 2,845.5 Million in 2025 to roughly USD 4,117.36 Million by 2032 at a 5.42% CAGR (forecast period 2026–2032). Market concentration metrics indicate opportunity: the three largest firms control around 42% of value, and the top five just under 60% — signaling a competitive arena with meaningful room for bolt-on consolidation, brand differentiation, and channel innovation.
Handheld Microphones Market
What the PW Consulting report contains — practical, executable deliverables
- Market sizing & forecast model (interactive): top-line scenario runs, sensitivity to input-cost inflation and wireless spectrum dynamics.
- Go-to-market playbooks: product positioning templates for premium, mid-tier and value handhelds; channel & pricing tactics for distributors vs. direct-to-creator approaches.
- Competitive scorecards: strategy, product roadmap signals, strengths/weaknesses, and likely strategic moves for every major vendor in the space.
- Supply chain & procurement playbook: dual-sourcing matrices, long-lead component hedging templates, and a supplier risk heat map linked to real-world contract clauses.
- Regulatory & compliance checklist: practical steps to meet imminent directives and export-control constraints, including engineering workarounds and certification timelines.
- M&A screening toolset: proprietary target-filter that combines technical differentiation with accretive revenue and cost-synergy estimates.
- Implementation timelines and KPIs: 90/180/360 day action plans with measurable milestones for product launches, factory retooling and channel rollout.
Note: the full report contains the detailed segment and regional splits, model spreadsheets, and the granular company financial proxies that underpin our recommendations; those are intentionally reserved for report subscribers and clients.
Handheld Microphones Market
Competitive landscape — who matters and why
The handheld microphone arena is served by a mix of heritage audio brands and agile challenger firms. PW Consulting’s qualitative and quantitative assessment highlights the following strategic positions:
- Shure Incorporated (Niles, Illinois) — A market leader in professional handhelds and wireless transmitters. Recent product activity signals continued focus on wireless interoperability and transmitter ecosystems. Shure’s legacy models remain strong anchors for live-sound customers, but component scarcity has prompted limited production runs on some wired classics, underscoring supply vulnerabilities.
- Sennheiser (Wedemark, Germany) — Strong in high-end stage and broadcast applications, with an evident push into fully digital wireless systems and integrated monitoring. Their trade-show and product update cadence suggests a platform approach—bundling mics with wireless and monitoring solutions.
- Audio‑Technica (Stow, Ohio) — Demonstrating iterative expansion in digital wireless SKUs. Their strategy mixes cost-conscious options for events and higher-margin digital handheld systems for broadcasters.
- AKG (Harman) & other legacy audio OEMs — Lean on brand recognition for stage and studio, while integrating product roadmaps into broader audio ecosystems (mixers, IEMs, processing).
- Neumann, DPA, Beyerdynamic — Niche and premium specialists focused on fidelity, modularity, and theater/studio applications where margin and brand trust are decisive.
- Rode, Samson — Aggressive at the content-creation and budget segments, pushing wireless sampling and compact systems to capture the long tail of creators and journalists.
Our company profiles in the full report combine product-level intelligence, patent analytics, dealer-channel mappings, and readiness scores that identify which firms are acquisition targets, likely consolidation leaders, or vulnerable to technology disruption.
Supply, regulation and cost dynamics to watch in 2026
- Raw-material pressure: a marked increase in magnetic-material costs in 2024 tightened transducer economics — event-driven price spikes for neodymium altered BOM cost structures and pushed some suppliers to re-evaluate magnet sourcing.
- Regulatory inflection: an EU restriction tightening lead content in solder joints takes effect mid-2026, requiring engineering redesigns or new assembly processes for products sold into that market.
- Geopolitical friction: export-control measures around rare earths and related components require stricter supplier due diligence and, in many cases, alternate sourcing pathways.
- Labor and location economics: rising manufacturing wages in Southeast Asia are changing the calculus for low-cost assembly; nearshoring and automation are back on the table for firms focused on margin protection.
- Legacy SKU disruption: supply disruptions have already forced limited productions of high-volume legacy mics, creating secondary-market demand and brand risk if availability is not managed.
Each of these dynamics is modeled in our stress-test scenarios so leaders can understand P&L sensitivity, product margin erosion, and time-to-market risk under plausible downside cases.
Actionable strategic playbook for 2026
- Short-term (0–6 months): secure multi-year commitments for critical transducer inputs; prioritize RoHS-compliant redesigns for major SKUs; freeze spectrum- and firmware-level requirements for wireless launches.
- Medium-term (6–18 months): accelerate modular-platform investments that allow shared baskets of parts across wired/wireless SKUs; expand service/firmware revenue streams to offset hardware margin pressure.
- Capital allocation & M&A: target tuck-ins that add wireless RF expertise, digital codecs, or service platforms rather than purely geographic expansion; use our M&A screening tool to size likely accretion and integration costs.
- Channel & product: for brands balancing pro and creator segments, adopt tiered SKUs with clear upgrade paths (hardware + subscription) to maximize lifetime value while protecting channel margins.
- Supply risk mitigation: combine dual-sourcing, qualified substitutions, and contract hedges; evaluate nearshoring for high-variability SKUs and automation investments where labor inflation is material.
Decision scenarios: prioritized first steps
- Manufacturer planning a new wireless handheld line: lock RF/codec standards, validate supplier roadmaps for rare-earth components, and negotiate conditional ROI-based tooling investments.
- Distributor optimizing inventory for 2026: prioritize high-turn, wireless-compatible SKUs and secure returnable-stock flex to manage legacy-model scarcity.
- Private equity evaluating targets: favor businesses with software/firmware platforms or proprietary RF stacks that offer post-sale monetization and defensible margins in a consolidating field.
Conclusion — the strategic value of the PW Consulting report
For leaders making pivotal 2026 decisions, the value of this study is its combination of rigorous market projection (USD 2,845.5 Million base in 2025; 5.42% CAGR 2026–2032) and operationally focused playbooks that translate scenarios into executable tactics. Whether managing product roadmaps, securing supply chains, or evaluating M&A, the report equips teams with the models and templates to act decisively while preserving strategic optionality.
To access our full company scorecards, segment and regional splits, interactive forecast models, and the complete set of implementation resources, consult the full PW Consulting Handheld Microphones Market report. Our subscription service also includes tailored advisory calls to adapt the insights to your balance-sheet and go-to-market realities.
For detailed analysis of this topic, please visit the official page: Handheld Microphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


