



PW Consulting Report: Magnetic Clamping Technology Market to Expand at a 6.45% CAGR Through 2026–2032

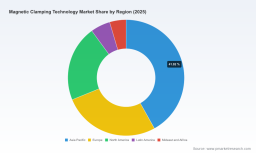
Magnetic Clamping Technology Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
Executive summary
Magnetic clamping technology is transitioning from a niche workholding solution to a mainstream enabler of automation, multi-face machining, and faster mold-change workflows. Our new market study — which covers 2020–2025 historic performance and provides a 2026–2032 forecast — quantifies that transition while translating it into actionable choices for procurement, R&D, and M&A leaders preparing for decisions in 2026. The sector demonstrates a steady compound annual growth rate (CAGR) of 6.45% over the forecast window, with the market expanding from a mid-single hundred million USD base in recent years toward a substantially larger opportunity by 2032. At the same time, concentration metrics indicate meaningful room for competitive maneuver: the top three players account for roughly 42% of the market and the top five for about 58% — evidence of both established incumbents and prospective challengers.
Magnetic Clamping Technology Market
Why 2026 is a pivotal year for corporate decision-makers
-
Capital cycles and procurement calendars across manufacturing industries are aligning with advanced automation investments scheduled for 2026. Organizations that lock in supplier relationships and technology roadmaps this year will gain a window of competitive uptime through the late 2020s.
Magnetic Clamping Technology Market -
Raw material dynamics are changing the cost and availability profile of magnetic systems. Neodymium oxide — a critical rare-earth input for high-performance permanent magnets — traded above USD 112,000 per tonne in 2026 amid demand pressures from electric vehicles and wind turbines. This tightness has direct implications for BOM engineering, long‑lead sourcing and hedging strategies.
Magnetic Clamping Technology Market -
Regulatory and safety standards are maturing: ISO 23582-1:2023 establishes essential safety requirements for magnetic clamping systems used on plastics and rubber machinery, and cleanroom compatibility (ISO Class 7 and 8) is increasingly referenced in product specifications for electro‑permanent systems. These developments create compliance thresholds that influence supplier selection, qualification timelines, and warranty conditions.
Market trajectory — a disciplined growth story
Our quantitative model shows consistent market expansion across the historical period into the forecast horizon, driven by adoption in molding, metalworking, and automation sectors. The calibrated CAGR of 6.45% reflects a combination of steady demand for faster setups, the growing footprint of electro‑permanent solutions, and incremental performance gains in magnet materials and control electronics. For strategy teams, this trajectory supports medium‑term investments (2–5 year paybacks) in both product development and capacity expansion, while leaving room for faster, targeted bets in aftermarket services and retrofit applications.
Core dynamics shaping supplier economics
-
Material cost volatility: The rare-earth market — valued at roughly USD 19.5 billion in 2024 — remains a cost driver. Firms that secure diversified supply, explore magnet formulation alternatives, or invest in design measures that reduce rare‑earth content will lower unit volatility risk.
-
Standards and safety: ISO 23582-1:2023 and cleanroom compliance requirements elevate the baseline for test documentation, traceability, and integration support. This increases the non-recurring engineering (NRE) and validation effort for suppliers and adopters alike.
-
Automation and systems integration: Magnetic clamping’s role in enabling deformation‑free holding, uniform force distribution, and rapid clamping for 5‑sided machining accelerates its adoption as part of integrated cell designs. Buyers should evaluate suppliers not only on magnet performance but on control interfaces, diagnostics, and serviceability.
Competitive landscape — what leading players bring to the table
The market is characterized by a mix of engineering-centric incumbents and regional specialists. Our competitive benchmarking evaluates product families, system compatibility, safety features, and go‑to‑market models.
-
SCHUNK GmbH & Co. KG (Germany) — Known for the MAGNOS suite, SCHUNK emphasizes uniform clamping for 5‑sided machining and vibration reduction. Strengths: application engineering and deep integration with milling centers.
-
Stäubli International AG (Switzerland) — Offers quick mold‑change magnetic systems (QMC series) with active safety and clamping force measurement. Strengths: solutions tailored for injection molding with a focus on small‑tonnage press compatibility.
-
AMF (Andreas Maier GmbH & Co. KG) (Germany) — Focuses on high holding forces for complex part geometries and close integration with zero‑point systems. Strengths: energy‑efficient platforms and strong presence in 5‑axis machining workflows.
-
ROEMHELD GmbH (RIVI M‑TECS) (Germany) — Supplies magnetic plates engineered for mold change, die casting and forming with attention to temperature resilience and safety during rapid tooling swaps.
-
Mag‑Autoblok Tecnomagnete (Italy) — A long-standing leader in electropermanent systems and customized solutions, with recent hybrid chuck developments signaling product modularity trends.
-
Earth‑Chain Enterprise (Taiwan) and regional specialists such as WALMAG, Eclipse Magnetics, Assfalg, Pascal Engineering, Braillon, Magnetool, Flaig and Spreitzer — collectively these firms contribute manufacturing breadth, niche applications expertise, and aftermarket services. Strengths include cost-competitive manufacturing, EEPM chucks for CNC machining, and localized technical support.
Our analysis shows a market neither perfectly consolidated nor fragmented; incumbency delivers scale, but technical differentiation and application depth create opportunities for focused challengers and partnership plays.
Recent industry movements to watch
-
Trade show activity in early 2026 (GLOBAL INDUSTRIE, BIEMH) underscores a resumed appetite for cross‑technology demonstrations — magnetic clamping paired with zero‑point, hydraulic, and vacuum solutions.
-
Product innovations such as hybrid self‑centering chucks and battery‑operated lifting magnets indicate a broader productization trend: buyers now expect plug‑and‑play modules that simplify retrofits and reduce footprint.
-
Company profile updates and distribution expansions highlight the push into new geographies and channel partnerships, amplifying aftermarket potential.
What the PW Consulting report delivers (practical content designed for action)
-
Market sizing and validated forecasts (2020–2032) with scenario sensitivity to raw‑material costs and adoption rates.
-
Regulatory and standards matrix (including ISO 23582‑1:2023 and cleanroom guidance) mapped to product development and procurement checklists.
-
Vendor scorecards that benchmark technical features, safety, service footprint, and unit economics — enabling rapid shortlists for RFPs.
-
Supply‑chain risk dashboard that quantifies exposure to rare earths and proposes hedging and sourcing strategies.
-
Commercial playbook for OEMs and systems integrators: pricing levers, aftermarket revenue models, and cross‑selling pathways into automation cells.
-
M&A and partnership framework: valuation multipliers, capability gaps to prioritize, and integration checklists for bolt‑on acquisitions or JV formations.
-
Field‑tested implementation guides and acceptance test procedures to reduce time‑to‑value post‑installation.
Strategic recommendations for 2026 decision-makers
-
Prioritize supplier assessments that include material traceability and ISO/cleanroom compliance evidence. Compliance is increasingly non‑negotiable and will shorten integration timelines.
-
Hedge rare‑earth exposure through multi‑source contracts, recycled magnet programs, or alternative magnet formulations where feasible. Factor raw‑material stress tests into total cost of ownership models.
-
Invest selectively in electro‑permanent magnetic (EEPM) platforms and control integration capabilities — these architectures combine low running energy with operational safety, making them attractive for automated production cells.
-
Design aftermarket and service offerings early. Rapid mold changes, diagnostic capabilities, and predictable maintenance windows translate directly into higher utilization and stickier customer relationships.
-
Use the market concentration profile to calibrate partner vs. competitor strategies: where incumbents dominate, focus on complementary modules and service differentiation; where fragmentation remains, pursue aggressive channel expansion and targeted acquisitions.
How to use this report in your 2026 planning cycle
Procurement teams: use the report’s vendor scorecards and acceptance checklists to reduce sourcing lead time and contractual risk. R&D and product: prioritize magnet formulations and control electronics that reduce rare‑earth dependency and support diagnostics. Corporate strategy and M&A: apply our valuation and integration framework to identify targets that either shore up supply or accelerate entry into adjacent automation markets.
Conclusion — the strategic payoff
Magnetic clamping technology will play a tactical and strategic role in factory modernization through the remainder of the decade. For executives making 2026 commitments, the critical choices are not binary “buy vs. build” questions but portfolio choices: which suppliers to lock in, which technologies to standardize on, and where to allocate R&D versus channel investments. Our report provides the quantified backdrop and the playbooks necessary to turn market momentum into measurable operating and financial outcomes.
Next steps
This preview highlights the report’s strategic value while withholding detailed segment-level disclosures and company-specific revenue splits. To access the full dataset, vendor profiles, and scenario models — and to obtain a tailored briefing for your executive team — please visit the PW Consulting report page for Magnetic Clamping Technology Market or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Magnetic Clamping Technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


