



PW Consulting Forecast: 5G Radome Market to Surge with a 13% CAGR, Led by Asia‑Pacific Demand

5G Radome Market: Strategic Imperatives for 2026 — PW Consulting
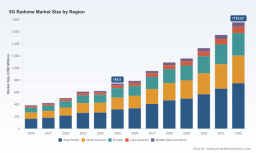
As service providers, infrastructure OEMs, and systems integrators plan capital deployment for the next wave of 5G densification, radome strategy is transitioning from a procurement afterthought to a deliberate product and site-level decision. PW Consulting’s latest 5G Radome Market study — using 2025 as the base year and projecting through 2032 — quantifies this shift and translates it into practical guidance for 2026 decision-making. The market has more than doubled since 2020 and enters a high-growth phase: our forecast shows a compound annual growth rate (CAGR) of 13.0% for the 2026–2032 period, lifting the addressable market to roughly USD 1,753.87 Million by 2032 (revenue unit: Million, currency: USD).
5G Radome Market
Why radomes matter now
Radomes are no longer purely mechanical enclosures. In 5G architectures — where mmWave, mid-band densification, and heterogeneous deployments coexist — radomes materially influence RF performance, thermal behavior, serviceability, and total cost of ownership. Decisions about materials, form factors, and integration strategies cascade into site acquisition timelines, CapEx efficiency, and long-term network quality. PW Consulting’s study positions radomes as a lever that stakeholders can use to reduce rollout friction, protect yield on spectrum investments, and optimize lifecycle economics.
5G Radome Market
Market trajectory and what it implies for 2026 decisions
-
Scale and momentum. The market expanded sharply in the 2020–2025 period, with the base-year size reaching USD 745.5 Million in 2025. The projected 13.0% CAGR for 2026–2032 signals sustained demand driven by macro deployments and retrofit cycles as operators densify networks and upgrade to higher-frequency assets.
5G Radome Market -
Concentration and competitive dynamics. Market concentration is moderate: the top-three players account for roughly 42.1% of the market, and the top-five for approximately 58.6%. These metrics suggest room for both established suppliers and specialist entrants, particularly in niche product lines (e.g., high-performance mmWave enclosures, lightweight airborne radomes, or low-cost small-cell shells).
-
Timing matters. For capital-intensive network rollouts planned in 2026, procurement windowing and supplier selection for radomes must align with equipment delivery schedules and permitting timelines. Regulatory initiatives and spectrum availability discussed below will compress or expand these windows; radome lead times and qualification plans must be synchronized accordingly.
Competitive landscape — who matters and where they play
Our competitive mapping synthesizes company capabilities, product strategies, and recent moves. Key vendors include global infrastructure suppliers and specialized composite manufacturers. Notable profiles from the report:
-
CommScope (United States) — Well-established in telecom infrastructure with radome offerings engineered for RF transparency and weather protection optimized for base station deployments. Their scale is an advantage where integrated antenna/radome packages are procured at program level ( https://www.commscope.com).
-
Exel Composites (Finland) — Focused on patented composite radome solutions that aim to minimize signal attenuation in high-frequency environments. Their recent IP development is targeted at deployment pain points for mmWave corridors ( https://exelcomposites.com).
-
Saint-Gobain (France) — Through its SHEERGARD range, the company supplies a breadth of structural systems (solid laminate, sandwich, fabric tensioned) with a focus on hydrophobic performance for outdoor and small-cell use cases ( https://www.saint-gobain.com).
-
General Dynamics Mission Systems (United States) — Brings aerospace/defense-grade radome expertise to high-frequency communications and mission-critical applications ( https://gdmissionsystems.com).
-
Laird Connectivity (United States) — Recently launched Radome5™ Poly, an injection-molded thermoplastic radome designed for indoor mmWave scenarios and small cells, signaling the commercialization of polymer-based, high-volume cost alternatives ( https://www.laird.com).
-
Supporting-material and component specialists — Companies such as Diab Group (core materials), Competition Composites, Pacific Radomes, and several regional manufactures (including Chinese suppliers) continue to supply the material and fabrication backbone for radome assemblies.
These vendor profiles are accompanied in the full report by supplier scorecards, capability heatmaps, and procurement playbooks that are actionable for OEM sourcing teams. To preserve strategic value for clients, the report provides deeper benchmarking and negotiation targets behind a paywall — an intentional guardrail aligned with the “trailer” principle of this release.
Technology, materials and product trade-offs
Material choice is the dominant trade-off axis. Glass-fiber composites, fluoropolymer laminates (e.g., PTFE), and engineered thermoplastics each offer distinct RF transparency, mechanical performance, manufacturability, and cost footprints. The optimal choice depends on site class (urban small cell vs. macro tower vs. airborne platform), intended frequency bands, environmental exposure, and serviceability constraints.
-
RF vs. durability: Higher RF transparency materials may increase sensitivity to impact or weathering; protective coatings and structural cores can mitigate those risks at an incremental cost.
-
Scale economics: Injection-molded thermoplastics can reduce per-unit cost for high-volume indoor small-cell runs but require upfront tooling investments and careful thermal/RF validation.
-
Repairability and lifecycle: For mission-critical or hard-to-access installations, repair-friendly systems and modular radome designs reduce lifecycle OPEX despite higher upfront cost.
The full study contains parametric cost models, lifecycle TCO calculators, and RF performance case studies to help engineering and procurement teams quantify these trade-offs for specific rollout plans.
Deployment economics and regulatory context
Two external dynamics will shape radome economics in 2026:
-
Infrastructure and spectrum policy. Regulatory moves to expedite buildouts, such as recent agency proposals to streamline approvals, coupled with planned mid-band spectrum auctions, are likely to accelerate densification programs and raise short-term demand for integrated radome/antenna solutions. Firms planning 2026 rollouts must factor regulatory cadence into supplier selection and site qualification timelines.
-
CapEx environment and cost pressure. Industry-wide 5G CapEx reached a multi-year inflection point, and total sector CapEx is estimated at approximately USD 250 billion by 2025. Deployers face equipment cost pressure, supply-chain volatility, and rising labor/material expenses (including fiber backhaul input costs). These forces increase the importance of radome cost-to-performance optimization and may prompt creative procurement models such as volume-tiered pricing, leasing, or integration contracts that bundle radomes with antennas and radios.
Operators and integrators should treat radomes not as passive line items but as strategic inputs that influence permitting speed, aesthetic compliance, and long-term maintenance budgets.
Risks, uncertainties and mitigation levers
-
Supply-chain concentration: While the market is not hyper-concentrated, lead times for specialized composite materials and tooling can introduce schedule risk. Mitigation includes multi-sourcing strategies, regional stocking hubs, and supplier qualification pre-approval.
-
Regulatory drag: Local permitting delays remain a persistent risk for urban densification. Early community engagement, standardized box designs, and pre-certified enclosures can materially shorten approval cycles.
-
Technology shifts: Advances in antenna integration (e.g., conformal arrays) and changes in preferred frequency bands can alter radome requirements mid-cycle. Designing modularity and upgradeability into radome choices reduces stranded-asset risk.
What the PW Consulting report delivers — practical outputs for 2026 action
This is a practical study designed for the program manager and the CFO as much as the RF engineer. Key deliverables include:
-
A concise market-sizing model (historical 2020–2025 and forecast 2026–2032) with scenario toggles for alternate rollout speeds and spectrum auction outcomes.
-
Supplier scorecards and CR-based concentration analysis to support shortlists and dual-sourcing decisions.
-
Radome selection playbooks that map site typologies to material choices, TCO outcomes, and RF performance trade-offs.
-
Procurement templates, expected qualification timelines, and a unit-cost sensitivity tool that incorporates tooling, materials, and logistics variables.
-
Case studies and failure-mode analysis from recent commercial deployments and defense-grade applications.
In keeping with the “trailer” approach of this release, we present high-level findings here to orient strategic decision-making while reserving the full set of segmented tables, region-by-application breakdowns, and supplier-specific price benchmarks for subscribers and report purchasers.
Actionable recommendations for 2026
-
Integrate radome strategy into the early procurement phase. Treat radomes as a performance and schedule risk in rollout planning rather than a downstream enclosure choice.
-
Pre-qualify at least two suppliers per major product class (composite, fluoropolymer laminate, engineered thermoplastic) and maintain a local inventory buffer to absorb short-term lead-time variation.
-
Commission RF-vs.-TCO pilots for high-volume small-cell and critical macro sites to generate empirical data that informs national deployment templates.
-
Engage with regulators proactively, leveraging standardized, pre-certified radome designs to accelerate permitting and reduce localized delays tied to aesthetics or environmental concerns.
-
Monitor vendor IP activity and product launches—recent examples such as the Laird Radome5™ Poly product introduction and Exel Composites’ European patent highlight the pace of innovation and the potential for design-led differentiation.
Conclusion — the strategic cliff notes
Radomes are a disproportionate value lever in 5G rollouts: modest design or procurement improvements can deliver outsized gains in schedule, spectrum efficiency, and lifecycle cost. The market is growing rapidly (13.0% CAGR for 2026–2032), with mid-term scale making supplier strategy, material selection, and regulatory alignment essential components of any successful 2026 deployment plan. PW Consulting’s 5G Radome Market report equips executives with the models, vendor insights, and procurement tools needed to translate these dynamics into defensible program decisions.
For the complete dataset, granular segmentation tables, supplier benchmarking matrices, and downloadable procurement templates, access the full report on PW Consulting’s portal. The detailed intelligence is designed to be directly actionable for 2026 budget cycles and rollout plans.
For detailed analysis of this topic, please visit the official page: 5G Radome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


