



PW Consulting: Intellectual Disabilities Services Market Poised for 6.19% CAGR Through 2032, New Report Shows

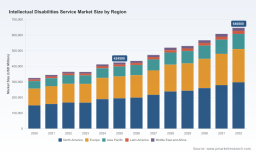
Intellectual Disabilities Service Market — 2026 Strategic Preview
Executive overview
PW Consulting’s newest market study, Intellectual Disabilities Service Market: 2026–2032, is released with a clear executive imperative: translate market momentum into executable strategies for the coming planning cycle. Anchored on a base year of 2025 and a historical review from 2020–2025, the study quantifies a market that has expanded markedly over the past half-decade and that our modelling projects will continue to grow at a compound annual growth rate of 6.19% through 2032. In plain terms, the market moved from roughly USD 325.5 billion in 2020 to about USD 424.5 billion in 2025 and is projected to approach USD 646.8 billion by 2032.
Intellectual Disabilities Service Market
Why this report matters for 2026 decision-making
2026 is a pivot year for operators, payors, investors, and policymakers in the intellectual disabilities services ecosystem. Converging forces — demographic demand, regulatory updates to HCBS quality and ICF/IID conditions of participation, wage and labor market shifts, and the rapid adoption of digital therapy platforms — mean that strategic choices made in 2026 will determine financial resilience and mission impact for the rest of the decade. This report is designed to convert broad market signals into concrete actions: where to invest in service delivery, how to redesign workforce models for retention and quality, how to approach M&A and partnerships, and how to structure contracts and reimbursement negotiations in an increasingly value-driven environment.
Intellectual Disabilities Service Market
What’s inside: operational, decision-ready content
-
Proprietary market sizing and scenario forecasts (base year 2025; forecast 2026–2032) with three alternative macroeconomic and policy scenarios to stress-test investment cases.
Intellectual Disabilities Service Market -
Service delivery playbooks that map workforce models, technology adoption timelines, and clinical integration checklists for residential, HCBS, vocational, and therapeutic settings.
-
Reimbursement and contracting guide: payer archetypes, negotiation levers, and a forensic framework for rate-setting and outcome-based contracting (national and state-level playbooks included).
-
M&A and partnership playbook: target screening criteria, valuation drivers, integration checklist, and post-merger operating model templates for scaling community-based services.
-
Practical KPIs and a 90–180 day operational roadmap for service providers to improve quality scores, reduce DSP vacancy, and prepare for managed care transitions.
-
Risk and regulatory heatmaps (including CMS HCBS quality measure changes and ICF/IID compliance obligations), plus mitigation playbooks for executives and boards.
-
Case studies and validated templates: sample RFIs/RFPs for payors, supplier contracting terms, and workforce compensation models aligned to state funding realities.
Market trajectory and strategic implications
The aggregate market trajectory — a recovery and step-up from 2023 into 2024–2025 and steady expansion into the early 2030s — reflects both structural demand (aging cohorts, earlier diagnosis and intervention, increasing service intensity) and policy-driven flows (Medicaid program design, HCBS evolution). The projected 6.19% CAGR through 2032 signals a market with both scale and fragmentation. For strategic planning in 2026, that implies three practical priorities: (1) define a defensible service footprint and partnership model; (2) reconfigure workforce strategy to manage labor cost inflation and retention risk; and (3) invest judiciously in digital modalities that demonstrably reduce cost-per-outcome.
Competitive landscape — who to watch and why
The sector remains highly fragmented; top-three and top-five concentration metrics confirm ample room for regional consolidation and new entrants. Several incumbent organizations and networks are shaping the competitive environment through acquisitions, partnerships, and platform launches:
-
Sevita (including The MENTOR Network and ResCare Community Living) — a national-scale operator focused on person-centered residential and HCBS models. The recent aggregation of capabilities positions Sevita as a fulcrum for continuity-of-care strategies across geographies.
-
BrightSpring Health Services — active on both the acquisition and portfolio-management fronts; its movement in and out of community living operations demonstrates a playbook of building integrated care offerings while optimizing asset portfolios.
-
Mosaic — a mission-driven operator with deep state-level proficiency in residential and 24-hour supports; representative of organizations translating scale into improved community inclusion outcomes.
-
The Arc of the United States — an advocacy and networked delivery model that can accelerate supported employment and policy influence when aligned with provider partners.
-
Keystone Human Services, Community Options, AbleLight, Devereux, Easterseals, KenCrest, Bayada, Lifeworks, and UCP — these organizations together illustrate the spectrum from national networks to regional specialists, each bringing distinct operating models, funding relationships, and community integration strategies.
Recent transactions and platform launches underscore strategic themes: consolidation for geographic scale and payer contracting leverage; digitization of therapy and tele-rehabilitation; and public–private collaboration to manage Medicaid transitions. Representative developments include BrightSpring’s portfolio moves and the rollout of tele-rehab platforms that expand access and change cost-per-session economics.
Regulatory, reimbursement, and labor dynamics shaping 2026 choices
-
Reimbursement: State Medicaid flows remain the dominant revenue engine for many service models. As an illustrative datapoint, New York State’s OPWDD reported Medicaid spending of approximately USD 9.1 billion in 2023 to serve over 130,000 individuals — an indicator of the scale and the degree to which state policy shifts can rapidly alter provider economics.
-
Regulation: Federal updates to HCBS quality measurement and the ongoing application of Medicare/Medicaid Conditions of Participation for ICF/IID settings increase compliance complexity and require board- level governance attention.
-
Labor cost and workforce: State-funded rate reforms, where present, have demonstrably reduced DSP vacancy in jurisdictions investing in rates and wages. Building flexible staffing models and embedding training-to-career pathways are essential 2026 actions to stabilize operations.
-
Managed care and program design: The expansion of managed care models in select states alters contract negotiation dynamics and necessitates robust outcomes measurement and care coordination infrastructure.
Strategic playbook — recommended actions for 2026
-
Providers: Prioritize revenue diversification and payer mix optimization; implement a phased digital-therapy deployment to realize productivity gains; redesign DSP roles with tiered certification and career ladders to reduce turnover.
-
Payors: Standardize outcome metrics in contracts, pilot shared-savings programs for supported employment and community inclusion, and require interoperable care plans to reduce care fragmentation.
-
Investors and acquirers: Focus on assets with proven state contracting relationships, scalable HCBS platforms, and embedded clinical governance; use scenario models from this report to stress-test reimbursement sensitivity.
-
Policymakers and system architects: Target funding reforms that tie rate increases to measurable quality gains, accelerate HCBS measurement implementation, and finance workforce development programs that reduce vacancy risk.
How PW Consulting’s report converts analysis into action
This report was constructed for operators who must make capital allocation, network design, and contracting decisions in 2026 with imperfect information. It combines a quantitative core (market sizing and scenario modeling), primary research (provider and payer interviews), and operational templates (integration checklists, procurement forms, KPI dashboards). In practical terms, a CEO can use the forecast and scenario outputs to re-weight capital plans; a payer can use the contracting templates to pilot outcome-based agreements; and an investor can use the valuation sensitivity models to price deals under alternative reimbursement regimes.
Market structure: fragmentation presents opportunity
Concentration metrics show the sector remains fragmented — a structural signal that consolidation, platform roll-ups, and strategic partnerships will continue to be strategic value-creation levers in 2026. Low top-player shares mean acquirers that can pair clinical quality with operational scalability will capture disproportionate bargaining power with payors and buyers.
Takeaway and next steps
PW Consulting’s Intellectual Disabilities Service Market: 2026–2032 is a tool for translating macro trends into boardroom-ready decisions. The market’s scale and growth trajectory create both opportunity and urgency: organizations that align workforce strategy, digital capability, and payer contracting in 2026 will be positioned to capture outsized value as the market expands over the next decade.
To preserve the utility of our strategic insights while protecting the detailed segmentation and primary-data tables that underpin robust decision-making, this piece intentionally highlights high-level findings and practical implications. The full report includes detailed regional and service-setting splits, payor-channel analyses, state-level reimbursement matrices, and downloadable operational templates to support immediate implementation.
Accessing the full analysis
Executives seeking the full dataset, segmented forecasts, and turnkey implementation assets should visit the PW Consulting report page to download the complete study and arrange a bespoke briefing. The full deliverable is designed to be operationalized within 30–90 days and includes a tailored decision-support session to apply the findings directly to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Intellectual Disabilities Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


