



PW Consulting: Hazardous Drug Disposal Services Market to Grow from USD 1.35B in 2025 to USD 2.22B by 2032 at a 7.34% CAGR

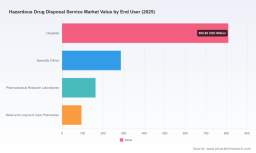
Hazardous Drug Disposal Service Market — Strategic Outlook for 2026 Decisions
Executive summary
As healthcare systems, pharmacies and life-science organizations move to tighten hazardous drug handling across the product lifecycle, the hazardous drug disposal service market has entered a sustained growth phase. PW Consulting’s latest market study — anchored on a 2025 base year and projecting through 2032 — quantifies that evolution and translates it into actionable guidance for executive decision-making in 2026. Our analysis estimates the global market expanded from approximately USD 948.5 Million in 2020 to USD 1,354.12 Million in 2025, and we model a continuation of that momentum into the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 7.34%, reaching an anticipated USD 2,223.25 Million by 2032.
Hazardous Drug Disposal Service Market
Why this matters for 2026 planning
-
Regulatory compression is driving near-term procurement and operational change. The EPA’s Hazardous Waste Pharmaceuticals Rule (Subpart P) and updates to generator rules, together with the continuing roll-out of USP General Chapter <800> requirements and a 2024 NIOSH list refresh, are tightening compliance thresholds and expanding the population of waste streams that must be managed under hazardous-waste standards. These shifts materially affect treatment, transport and recordkeeping requirements across providers and payers.
Hazardous Drug Disposal Service Market -
Policy heterogeneity creates execution risk. In 2025 and early 2026 we saw continued state adoptions of Subpart P and fresh EPA guidance on household medication disposal and management standards for healthcare facilities. Organizations that assume homogenous regulatory exposure risk non-compliance and unplanned cost escalation; those that model multiple adoption scenarios can lock in compliant, cost-effective channels before capacity squeezes emerge.
Hazardous Drug Disposal Service Market -
Market growth is both demand- and regulation-driven. The combination of rising hazardous-drug usage in oncology and specialty care, expanded testing and research activity, and tightened regulatory controls is sustaining demand for end-to-end solutions: segregation, characterization, chain-of-custody documentation, secure transport, and destruction tailored to controlled substances and RCRA-classified items.
What PW Consulting’s report delivers (practical, executable content)
Our objective was to make this study a working tool for procurement leaders, compliance officers, and operations heads who must make decisions in 2026. Highlights of the report’s actionable components include:
-
Compliance playbook: a step-by-step framework to map federal, state and local obligations against on-site handling practices (segregation, temporary storage, neutralization options, and permitted disposal routes), with checklists aligned to USP <800>, DEA and RCRA touchpoints.
-
Vendor selection and benchmarking toolkit: standardized RFP templates, service-level matrices and audit scorecards that let buyers compare offerings on legal defensibility, documented chain-of-custody, incineration or alternative destruction capacity, and hazardous-materials expertise.
-
Total-cost-of-ownership (TCO) models and scenario simulations: configurable models that integrate disposal fees, transport, internal handling labor, compliance penalties and contingency costs under alternative regulatory adoption pathways. These models are designed to be embedded in 2026 capital and OPEX planning cycles.
-
Operational readiness roadmaps: short- and medium-term initiatives (0–6 months, 6–18 months, 18–36 months) covering segregation pilots, staff training curricula, IT integration points (EHR/pharmacy systems to vendor tracking), and contract language for performance guarantees and audit rights.
-
Risk and capacity stress testing: bespoke scenario analyses that identify where regional disposal infrastructure or incineration capacity could become binding constraints and recommend mitigation via multi-vendor strategies, pooling arrangements or contractual capacity reservations.
Competitive landscape — interpreting who matters and why
The market shows a balance between national integrated waste players and specialist healthcare-focused providers. Concentration indicators in our study point to a market where the largest three firms control a meaningful share but where mid-market and specialist vendors retain significant room to grow — a dynamic that favors differentiated service models and geographic or vertical specialization.
-
Stericycle, Inc. (Lake Forest, Illinois) — A global leader with deep regulatory advisory capabilities and a strong presence in healthcare compliance services. Stericycle’s ongoing alignment materials around Subpart P and USP <800> and its procurement wins in public health demonstrate the advantage of combining national scale with compliance expertise.
-
Clean Harbors, Inc. (Norwell, Massachusetts) — A scale hazardous-waste operator with strengths in transportation, treatment and destruction services across North America. Clean Harbors is well suited to customers requiring integrated treatment capacity and hazardous-waste logistics.
-
Veolia Environnement S.A. (Paris) — A global environmental-services competitor with incineration capability and multinational footprints, attractive to health systems and pharma companies operating across jurisdictions.
-
Waste Management, Inc. (WM) — Leverages broad waste-management networks to offer packaged medical and pharmaceutical disposal solutions, often bundled with broader environmental services contracts.
-
Daniels Health — A specialist that emphasizes secure pharmaceutical waste containers, healthcare-focused compliance services and formulary analysis. Specialists like Daniels are winning share where healthcare clients demand clinical-facing operational support and working capital efficiency.
-
Other notable players — Republic Services, US Ecology and a set of regional specialists and niche healthcare providers complete the landscape; together they create competitive advantages for buyers willing to segment sourcing by service type or geography.
From a concentration standpoint, the market exhibits moderate concentration: the three largest vendors account for a significant portion of revenue while the top five command a clear majority, leaving room for specialized providers to differentiate on compliance support, clinical integration and customer service.
Recent developments that change action priorities in 2026
-
Policy updates: Several states adopted full Subpart P in 2025 and the EPA issued updated guidance in early 2026 — a pattern that increases the likelihood of staggered state-level adoption across the next 18–36 months and raises the premium on flexible, compliant disposal supply chains.
-
Guidance convergence: Industry leaders have updated USP <800> implementation materials and aligned waste handling guidance with RCRA interpretations; organizations that proactively harmonize their processes stand to lower audit exposure and avoid costly retrofits.
-
Procurement momentum: Public-sector and health-district procurements continue to favor vendors with documented RCRA and DEA competencies — a trend that underscores the value of demonstrable compliance evidence and interoperable documentation systems.
Strategic implications — five actions for 2026
-
Prioritize a compliance-first RFP: Build contract language that covers Subpart P adoption scenarios, audit access, chain-of-custody SLAs and witnessed destruction provisions for controlled substances.
-
Run a rapid segregation pilot: Reduce downstream disposal costs and regulatory exposure by piloting upstream segregation, staff training, and point-of-care containment in a subset of high-volume units (e.g., oncology clinics, specialty pharmacies).
-
Adopt a multi-vendor sourcing strategy: Combine national incumbents for scale with specialist providers for clinical operational integration and contingency capacity to mitigate regional infrastructure constraints.
-
Invest in traceability technologies: Data-driven chain-of-custody tools — barcode/RFID, cloud-based manifests, and EHR/pharmacy system integrations — materially reduce audit time and the cost of regulatory demonstrations.
-
Model the P&L and compliance exposure together: Use scenario-driven TCO and stress tests to budget for OPEX increases tied to accelerated regulatory adoption and to justify investment in prevention/segregation versus downstream disposal spend.
How PW Consulting helps
Clients engaging PW Consulting receive a tailored combination of market data, operational blueprints and supplier negotiation support. Our engagements typically include a custom regulatory exposure map, a supplier heat map calibrated to your footprint and a prioritized three-year implementation roadmap that converts report insights into executable programs that start delivering compliance and cost containment within quarters.
Next steps — where to find the full intelligence
This executive brief is designed to surface the strategic choices that will matter in 2026 and to demonstrate the depth of the analysis contained in the full report. PW Consulting’s full Hazardous Drug Disposal Service Market report contains the proprietary demand-supply model, regional capacity assessments, and the granular vendor scorecards and templates required to operationalize the recommendations above. For procurement teams, compliance leaders and private equity sponsors evaluating M&A or partnership plays, the complete report provides the detailed segmentation, contract clauses and financial models not disclosed here.
Contact PW Consulting to request access to the full study, schedule a briefing, or commission a bespoke market-impact assessment tailored to your operational footprint and regulatory exposure.
For detailed analysis of this topic, please visit the official page: Hazardous Drug Disposal Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


