



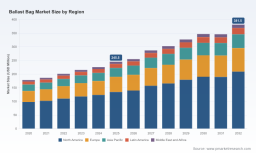
PW Consulting: Ballast Bag Market to Reach USD 381.5 Million by 2032, Growing at a 6.5% CAGR

Ballast Bag Market 2026: Strategic Briefing for Executive Decision-Makers
PW Consulting’s new Ballast Bag Market report (base year 2025, historical window 2020–2025, forecast 2026–2032) equips leaders with the forward-looking intelligence required to convert market growth into competitive advantage. The global market—measured in USD Million—emerged from a steady post‑pandemic recovery and is positioned to expand at a mid‑single-digit compound annual growth rate (CAGR) over the forecast window. That trajectory reflects a mix of recreational demand, industrial testing requirements, and evolving regulatory and material dynamics. This briefing distills the report’s strategic value for 2026 decisions while reserving the full segmentation and granular model outputs for report subscribers.
Ballast Bag Market
Market snapshot (what the macro numbers tell you)
Our market construction uses 2025 as the operational base year and leverages five years of historical data (2020–2025) to calibrate drivers and seasonality. From that base the market is forecasted through 2032 under multiple scenarios; under PW Consulting’s central case the sector grows at approximately 6.5% CAGR. The implication is clear: volume and revenue pools will expand meaningfully over the coming six-plus years, creating windows for product innovation, margin improvement through scale, and selective consolidation.
Ballast Bag Market
- Growth is multi‑vector: consumer-oriented segments (wake sports, recreational boating) remain the principal demand engine, while professional and industrial uses (marine load testing, aerospace test rigs) provide higher‑ticket project opportunities and technical differentiation.
- The expansion is not uniform — pockets of rapid deployment will appear where regulatory clarification, OEM integration, or certification adoption removes friction to purchase.
- For 2026 planners, the headline is actionable: invest where you can anchor long‑term OEM relationships or capture high‑value industrial tenders; use scale to absorb raw‑material cost swings and fund product premiumization.
Why this report matters for 2026 strategy
We designed the report as an operational playbook for the 2026 decision cycle. Executives contemplating capex, go‑to‑market pivots, or M&A will find three immediate payoffs:
Ballast Bag Market
- Clarity on demand elasticity and pricing power by product family, enabling pragmatic revenue and margin scenarios without relying on anecdote or single‑deal logic.
- Actionable supplier and raw‑material maps that translate PVC, polypropylene and cordura supply dynamics into procurement levers and hedging strategies.
- Compliance and certification pathways (industry standards and regional regulations), reducing time‑to‑contract in safety‑sensitive, load‑test arenas.
Report contents — practical modules included
To preserve the ‘trailer’ nature of this release we summarize the report’s scope without exposing the detailed segmentation tables and proprietary numeric outputs that subscribers receive. The full report contains:
- Methodology and assumptions: reconstructable models that show how historical demand, replacement cycles and new OEM adoption feed the 2026–2032 forecast.
- Scenario playbooks: three scenario trajectories (central, upside, downside) with triggers and contingency action lists for each.
- Cost and margin heatmaps: bill‑of‑materials modelling across material choices (PVC coated fabrics, welded vinyl, polyurethane, woven polypropylene, Cordura with steel shot filling) and assembly processes.
- Commercial playbooks: GTM templates for OEM partnerships, aftermarket retail, and e‑commerce channels; dealer economics and channel incentive designs.
- Regulatory and standards matrix: compliance checklists tailored for marine load testing and recreational modifications, including pathways to IMCA and LEEA alignment.
- Target lists and diligence pack templates: candidate screening criteria for bolt‑on acquisitions, joint ventures and strategic minority investments.
Competitive landscape: what leading players reveal about future moves
The market today is characterized by a set of specialized suppliers serving distinct verticals. Below we synthesize public profiles and commercial implications for the named manufacturers spotlighted in our research.
-
FATSAC (Milwaukee, USA) — A heritage US producer focused on water‑filled vinyl systems for wakeboarding and wakesurfing. Their emphasis on proprietary layered vinyl and welded seams signals a classic premium, brand‑led strategy: quality, durability and boat‑OEM recognition. Firms in this niche benefit from close OEM integration and strong direct‑to‑consumer credibility; their risk lies in raw material (PVC) cost volatility and the need to maintain certifiable safety claims as regulations tighten.
-
LEAD WAKE (California, USA) — Specializes in steel shot‑filled bags built into durable textile shells, leveraging recycled feedstock. This positioning answers two concurrent market currents: demand for precise, compact ballast and rising sustainability narratives. Their manufacturing approach (cordura shells, hand assembly) supports premium pricing but may face scale constraints unless investment in automated processes follows.
-
Wake Ballast (Arizona, USA) — Offers both water and steel shot products with an emphasis on rapid fulfillment, warranty coverage and customization. This hybrid product strategy is well suited for aftermarket growth and dealer networks. Their competitive edge derives from logistics and service; scaling international distribution and certification for industrial testing represents the next frontier.
-
DOOWIN (Qingdao, China) — A supplier of proof load test ballast bags in the multi‑ton range, compliant with IMCA D016 and LEEA 051 standards. This company illustrates the industrial end of the spectrum: high‑capacity, standards‑driven products for shipyards, cranes and heavy lifting tests. Cost‑competitive manufacturing and compliance expertise create a defensive moat in project procurement.
-
Safetmade (Turkey) — Focused on marine load testing, with customization options including human‑form freefall test bags. Their proposition is technical customization and regional proximity to European yards — a strategic advantage for tender capture where lead times matter.
-
Fend‑Air / Subsalve (USA) — Leveraging lift‑bag technology, they address the market for low handling weight, standards‑compliant test bags. Their systems approach and brand trust in heavy‑lift and subsea markets present an attractive model for cross‑selling into adjacent test and safety product categories.
Strategically, these players indicate two durable axes of competition: consumer/oem‑facing suppliers that prioritize brand, fit and aftermarket support; and industrial/certified suppliers that compete on technical compliance, scale and cost. For incumbents and entrants alike, successful strategies will combine one axis with selective moves into the other — e.g., premium wake bag vendors offering certified test units, or industrial suppliers developing rapid‑fulfillment small‑format kits for the recreational channel.
Regulatory and raw‑material dynamics to watch in 2026
- Regulation: Emerging local rules that address wake‑enhanced boating and ballast modifications (recent legislative activity provides early signals) will shape product labeling, installation standards and dealer responsibilities. Early engagement with regulators and the boating community reduces enforcement risk and creates credentials that win OEM contracts.
- Standards: For industrial load testing, compliant product design (IMCA, LEEA and equivalents) is a non‑negotiable entry criterion. Certification pathways lengthen sales cycles but materially increase contract size and stickiness.
- Materials: Raw‑material selection (PVC vs polyurethane vs woven polypropylene; recycled steel shot vs lead) directly affects lifecycle cost, weight efficiency and sustainability claims. Hedging strategies and supplier diversification are practical, near‑term levers.
Risks, catalysts and tactical recommendations for 2026
- Risk — Price and supply shocks: volatility in resin and commodity metals can compress margins quickly. Recommendation: implement multi‑tier supplier contracts with indexed pricing and volume carve‑outs.
- Catalyst — Certification adoption: a focused certification program for recreational products (lab testing + installation protocols) can unlock OEM fleet deals and accelerate dealer acceptance.
- Risk — Liability and safety incidents: a single high‑profile failure in wake or load testing segments could trigger recall costs and tighter regulation. Recommendation: prioritize traceability, serialisation and extended warranties.
- Opportunity — Product modularization: offering modular ballast systems that are interchangeable between water and shot modules or ship‑to‑shore usage creates aftermarket stickiness and recurring revenue potential.
- Opportunity — Sustainability premium: visible use of recycled steel and recyclable textile components can support differentiated pricing with environmentally conscious buyers.
How to use this report in your 2026 plan
For C‑suite leaders and corporate development teams, the report serves as a playbook and an execution accelerator. Practical use cases include:
- Prioritizing R&D investments across product families to improve margins and comply with evolving standards;
- Structuring procurement and H1 2026 supplier negotiations around indexed contracts and capacity guarantees;
- Running rapid commercial pilots with OEM and dealer partners using the report’s GTM templates and customer segmentation heuristics;
- Screening M&A targets using our transaction scorecard to find scale complements or technology gaps; and
- Preparing regulatory engagement plans and certification roadmaps to shorten sales cycles in industrial tenders.
PW Consulting’s Ballast Bag Market report is intentionally structured as an execution resource: detailed models, supplier maps, compliance matrices and commercial playbooks are included to fast‑track 2026 action. This press release has highlighted the strategic contours and decision levers; the full report contains the underlying data, segmentation tables, and proprietary forecasts that operational teams need to implement the recommendations above.
Next step
To access the full dataset, segmentation analyses and the executable templates referenced here, please visit the PW Consulting report page. Subscribers receive the granular spreadsheets, slide decks for board briefings, and rapid‑deployment playbooks that convert market insight into measurable outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Ballast Bag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


