



PW Consulting Forecast: Brine Preparation Systems Market to Top USD 794.51 Million by 2032, Backed by a 6.01% CAGR

PW Consulting Releases Strategic Brief: Brine Preparation Systems Market Outlook to 2032 — What Leaders Need to Know for 2026 Decisions
PW Consulting today publishes an executive briefing derived from our full Brine Preparation Systems Market report, crafted to equip C-suite leaders, procurement heads, municipal planners, and strategic investors with the evidence-based perspective they need to make high-confidence decisions in 2026. Drawing on a validated market model (historical 2020–2025, base year 2025), primary interviews with OEMs and end-users, and cross-checked trade statistics, this brief highlights the structural forces shaping the market while deliberately preserving proprietary segment-level tables for full-report subscribers.
Brine Preparation Systems Market
Market snapshot: scale, trajectory, and concentration
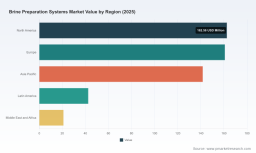
The global brine preparation systems market crossed the half-billion USD threshold in our base year, with total market revenue estimated at USD 528.4 Million in 2025. PW Consulting’s forecast model anticipates sustained mid-single-digit growth through the forecast window 2026–2032, with a compound annual growth rate (CAGR) of 6.01% and end-period market scale approaching USD 795 Million by 2032 under the baseline scenario. Market structure remains modestly concentrated: the top three suppliers account for under 40% of market revenue, while the top five capture just over half—an architecture that both enables scale winners and leaves room for regional and capability-focused challengers.
Brine Preparation Systems Market
Why this briefing matters for 2026 strategic choices
-
Investment timing: The 6.01% CAGR and the shape of our demand curve identify specific windows where capacity investments and targeted R&D deliver disproportionate returns. For suppliers planning plant expansions or new product introductions, 2026 is the pivotal year to lock engineering timelines and supplier contracts to capture the early uptick in commercial and municipal procurement cycles.
Brine Preparation Systems Market -
Procurement and Total Cost of Ownership (TCO): For large buyers—municipalities, road maintenance contractors, food processors—the economics of automated versus manual systems are evolving rapidly. Buyers who re-run TCO models incorporating our updated operating-cost assumptions and regulatory drivers will materially improve lifecycle savings and environmental compliance outcomes.
-
M&A and partnership playbook: Given the market’s moderate concentration and the prevalence of regional specialists, 2026 will favor bolt-on acquisitions that extend channel reach or unit economics (e.g., automation modules, corrosion-resistant materials, service contracts). Our scenario analyses identify the categories of targets that maximize integration synergies while preserving margin.
Drivers, headwinds, and windows of competitive advantage
-
Raw-material dynamics: Feedstock economics remain a core input for brine system operators. Recent commodity intelligence shows U.S. salt used in brine exhibited a low unit value relative to processed salt products in 2023, and salt-in-brine continues to represent a significant share of salt producers’ mix. Meanwhile, global industrial salts demand—valued at roughly USD 15.7 billion in 2024—creates sustained upstream demand pressure. Companies that secure low-cost, stable salt supply chains or who innovate to reduce salt consumption per operational unit will capture margin upside.
-
Industrial demand pull: Specific industrial segments—most notably chloralkali production (caustic soda, PVC precursors)—are driving increased demand for brine inputs in certain regions. Suppliers who can certify purity, consistency, and supply reliability stand to win long-term contracts with chemical manufacturers.
-
Regulatory tightening and environmental constraints: Environmental regulation on runoff and chloride management in de-icing applications is altering procurement specifications for municipalities and contractors. This regulatory tightening is a double-edged sword: it raises barriers for low-cost, low-compliance suppliers while creating opportunities for system providers offering precision dosing, runoff mitigation features, and lifecycle environmental assessments.
-
Technological differentiation: Automation, sensor-enabled mixing control, and integration with fleet-management systems are emerging as decisive features. Systems that combine ease-of-maintenance, traceable quality controls, and lower labour requirements command pricing premiums and reduce buyer friction in regulated environments.
What the full report contains — practical, procurement-ready deliverables
PW Consulting’s full Brine Preparation Systems Market report goes beyond descriptive analysis to deliver operationally useful deliverables for decision-makers. The document includes:
-
A calibrated market model (historical 2020–2025, base 2025) and scenario-based forecasts through 2032, with sensitivity tables to test commodity-price, regulation, and adoption-rate hypotheses.
-
Buyer-centric TCO templates for automated versus manual/semi-automatic systems, adjustable for local labour, salt cost, energy tariffs, and maintenance cadence.
-
CapEx guidance and payback calculators tailored by installation profile (municipal de-icing hub, large food processing plant, chemical feedstock supplier), including recommended financing structures.
-
Regulatory impact mapping and mitigation playbooks—highlighting compliance requirements, reporting workflows, and retrofit options to manage runoff and chloride reduction targets.
-
Procurement and supplier-selection scorecards—factor-weighted evaluations that translate technical specs into procurement-ready decision matrices.
-
Vendor shortlists and capability maps: high-level supplier assessments and capability clusters (automation, heavy-duty industrial, food-grade hygiene, winter-road focus). Note: detailed vendor market shares and region/application splits are reserved for the full report to protect analytical IP and to encourage direct engagement with our team.
Competitive landscape: strategic profiles and implications
The competitive field is composed of legacy builders, food-equipment specialists, and winter-maintenance innovators. Our review of leading players clarifies where strategic advantage resides and where gaps remain.
-
BrineMaker Inc. (United States) — Strengths: deep salts experience, multiple U.S. manufacturing sites for logistics optimization, and strong product engineering capability. Strategic implication: scale-oriented buyers and large processors will find BrineMaker attractive for customized, integrated solutions with accessible spare-parts logistics.
-
GEA Group (Germany) — Strengths: industrial-scale hygiene and controlled-mixing systems tailored to food processing, with disciplined focus on cost-of-ownership and cleaning protocols. Strategic implication: global food processors seeking hygienic, high-throughput mixing systems should prioritize vendors with food-industry credentials and validation records.
-
BAK Food Equipment / NOWICKI USA / Rhino Manufacturing — Strengths: purpose-built meat and seafood processing brine platforms, robust operator-centric designs, and food-grade materials. Strategic implication: these suppliers compete less on price and more on operational reliability, consistent flavor control, and reduced downtime—key decision levers for quality-sensitive processors.
-
AccuBrine / GVM Inc. / VariTech / Brine Masters / AUTOBrine / Camion Systems / Dultmeier / Pengwyn / Marlo — Strengths: focused portfolios for winter maintenance, municipal brine-making, and de-icing applications, with automation, upflow technologies, and skid/portable solutions. Strategic implication: municipal procurement teams should evaluate total lifecycle chloride use, equipment footprint, and integration with existing fleet systems when comparing these specialists.
-
Cargill Deicing Technology — Strengths: distribution reach and commodity integration via dealer networks; strategic for customers prioritizing supply continuity and dealer-based service models.
Across these segments, our supplier mapping finds differentiated value propositions—ranging from high-spec food-grade systems to rugged, low-maintenance road-deicing units. The tactical play for suppliers in 2026 is to strengthen channel partnerships, invest selectively in automation modules, and lock salt supply or blending agreements that offer predictable input costs.
Actionable recommendations for 2026
-
Suppliers: Prioritize modular automation retrofits and aftermarket service offerings; these drive higher-margin recurring revenue and accelerate adoption among conservative buyers.
-
Buyers (municipal & contractor): Recalculate procurement value using updated TCO models that include environmental compliance costs and expected shifts in salt prices; short-list vendors that demonstrate measurable chloride reductions.
-
Food processors: Demand end-to-end hygiene validation and supplier SLAs for brine consistency—downtime and quality variance are cost multipliers in meat, poultry, and seafood processing.
-
Investors & M&A teams: Target regional system integrators and software-enabled service providers for bolt-on acquisitions; prioritize assets with proprietary control algorithms or strong installed-base service contracts.
Methodology and validation
Our forecasts rely on a blended methodology: bottom-up build of installed base and replacement cycles, top-down macro demand checks against industrial salts flows, and triangulation with OEM interviews and procurement tenders. The model uses USD (Million) as the reporting unit, with the base year set to 2025 and the forecast period running 2026–2032. Where market outcomes are sensitive to regulatory shifts, we present alternate-policy scenarios in the full report to help executives stress-test strategic options.
Next steps — how to access the full intelligence
This briefing is a strategic primer. The full PW Consulting Brine Preparation Systems Market report contains the granular models, vendor scorecards, and procurement tools necessary to act in 2026 with confidence. To obtain the complete report or to schedule a custom briefing that adapts our findings to your operational footprint, contact PW Consulting’s industry team. Our analysts will walk you through the scenario outputs and provide the bespoke decision-support templates that underpin Board-level capital decisions.
PW Consulting — translating market intelligence into decisive advantage for 2026.
For detailed analysis of this topic, please visit the official page: Brine Preparation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


