



PW Consulting Predicts Low Refractive Index Resin Market to Reach USD 836.95 Million by 2032, Growing at an 8.1% CAGR

Low Refractive Index Resin Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting’s latest market study on Low Refractive Index (Low-RI) Resins synthesizes proprietary modeling, supplier-level due diligence, and scenario planning to equip commercial leaders with the tools to make high‑confidence decisions in 2026. The market has demonstrated consistent expansion through the post‑pandemic recovery and into near-term growth: our baseline shows the global Low‑RI resin market rising from approximately USD 334 million in 2020 to about USD 485 million in the 2025 base year, and we forecast acceleration toward roughly USD 837 million by 2032 at a compound annual growth rate (CAGR) of 8.1% over the 2026–2032 forecast horizon. This trajectory reflects intensifying demand across photonics, optical interconnects, AR/VR, and advanced packaging, but it is accompanied by material‑level risk and regulatory pressures that will shape winners and losers in the next 18–30 months.
Low Refractive Index Resin Market
Executive snapshot — what this report means for 2026 decision makers
- Market momentum is robust: the Low‑RI resin sector is on a multi‑year growth path with double‑digit contributions from emerging photonics applications. Executives should plan capacity, R&D, and commercial investments with a four‑to‑six year horizon in mind.
- Supply and regulatory risk are front‑of‑mind: specialty fluorinated monomers exhibit pronounced price volatility and regulatory scrutiny in key jurisdictions—strategic procurement and material substitution options are core to risk mitigation.
- Competition is product‑led and IP‑heavy: a small group of specialist resin developers dominate advanced low‑RI chemistries through targeted patents and application partnerships; partnership strategies will often outperform pure organic scaling.
- Operational playbooks matter: the commercial edge will belong to firms that pair materials performance with systems engineering, scale‑efficient manufacturing, and documented regulatory pathways.
Why 2026 is a strategic inflection point
Several converging trends make 2026 the year to move from exploratory pilots to committed capability builds. First, end‑market adoption of photonics‑intensive products — from co‑packaged optics and fiber lasers to AR/VR optics and advanced anti‑reflective coatings — is maturing past laboratory validation into manufacturable designs. This raises demand not only for lower refractive indices but also for predictable curing behavior, thermal stability, and compatibility with high‑throughput processes.
Low Refractive Index Resin Market
Second, raw‑material supply volatility and cost swings in specialty monomers (some precursors have shown year‑over‑year price volatility exceeding 25%) are compressing margins for downstream OEMs and creating urgency to diversify supplier networks or qualify alternative chemistries. Third, the regulatory landscape for fluorinated chemistries is evolving rapidly: while some regulatory bodies have signaled pathways for essential‑use exemptions or classification of certain polymer forms as low concern, parallel PFAS‑related testing and compliance requirements are increasing due diligence burdens for suppliers and buyers alike.
Low Refractive Index Resin Market
For firms considering expansion or product launches in 2026, these dynamics mean that timing, partner selection, and an end‑to‑end risk plan will determine the return on investment more than raw technical novelty alone.
What PW Consulting’s report delivers to strategic teams
- Actionable market sizing and forecast model (2020–2032) with scenario toggles for demand, regulatory constraint, and raw‑material shocks — downloadable model allows you to stress test your revenue plans under multiple states of the world.
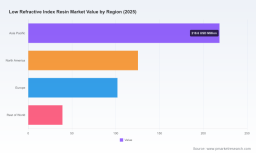
- Segment mapping and adoption curves across optical end uses — we outline trajectories for each application class and identify near‑term pockets of upside and functional obsolescence (note: detailed segment tables and regional/application splits are reserved for the full report and data portal).
- Competitive benchmarking and supplier scorecards that evaluate technology maturity, IP position, manufacturing footprint, and compliance readiness — designed to speed partner selection and M&A screening.
- Go‑to‑market playbooks: customer qualification checklists, pilot acceptance criteria, value‑based pricing frameworks, and “first‑1000 units” manufacturing ramp templates for resin‑enabled optical components.
- Procurement and supply‑chain toolkits: category TCO models, hedging strategies for specialty monomers, dual‑sourcing matrices, and contract templates that embed regulatory clauses.
- Regulatory & compliance playbook: region‑specific testing roadmaps, PFAS risk assessments, and recommended engagement points with regulators to support essential‑use arguments and approvals.
- M&A and partnership diagnostic: targets filtered by technology fit, incremental revenue potential, and integration risk, plus a priority roadmap for licensing, JV, or acquisition approaches.
Competitive landscape — profiles that define the market
The Low‑RI resin market is characterized by specialized, vertically focused players that combine chemistry IP with applications engineering. Our report’s supplier scorecards drill into product families, patent estates, OEM relationships, and manufacturing scale. Highlights include:
- Luvantix ADM Co., Ltd. (South Korea): A market leader with deep emphasis on UV‑curable low‑RI chemistries tailored for fiber lasers and photonics. Their portfolio includes low‑index UV resins and epoxy systems that minimize shrinkage and withstand elevated processing temperatures. Significant OEM relationships and a portfolio of original patents make Luvantix a go‑to partner for co‑development of high‑performance optical components.
- Fospia (South Korea): Focused on fluorinated acrylate platforms designed for specialized fiber and laser recoating applications. Fospia’s chemistries prioritize thermal and water resistance, and the company has purpose‑built product lines for optical fiber process compatibility.
- Inkron (Nagase Group, Finland): Known for siloxane‑based low‑RI coatings with exceptionally low refractive indices across a range of optical device applications. Inkron’s materials are often selected where broad transparency and low birefringence are required, complementing higher‑index offerings in multi‑layer optical stacks.
- MY Polymers (Israel): A polymer specialist supplying low‑RI solutions for primary fiber coatings, lamination adhesives, and photonics applications, with demonstrated market engagements across North America, Europe and Asia.
- NTT‑AT (Japan): Positions itself as a precision supplier with materials that deliver fine refractive index control and high transparency, oriented toward optical recording, displays, and optical energy applications.
- DIC Corporation (Japan): A larger specialty chemicals player with UV‑curable optics capabilities and scale advantages for film and coating applications.
Our analysis shows that the competition is not purely about lowest RI number; it is equally about cure performance, thermal budget, processing compatibility, and regulatory defensibility. IP‑rich players that can demonstrate application‑level integration and compliance readiness tend to command premium positioning.
Recent developments that change the decision calculus
- Product innovation: Leaders are pushing new form factors and process‑ready solutions, from ultra‑thin micro GRIN lens arrays for co‑packaged optics to epoxy systems with zero curing shrinkage — these launches shift manufacturability and integration risk in favor of early adopters.
- Industry engagement: Supplier presence at major optics and photonics forums signals commercial readiness and supply confidence; expecting more demonstration‑to‑purchase conversions through 2026.
- Regulatory and product lifecycle moves: Some legacy low‑RI acrylate grades have been slated for discontinuation for commercial or regulatory reasons, increasing the strategic value of qualified alternatives and raising the cost of switching for OEMs.
- Supply chain noise: Specialty precursor pricing and availability variability underline the need for multi‑tier contingency planning and vertical integration options for high‑value applications.
Five strategic moves for 2026
- Prioritize application‑led partnerships over chemistry‑led R&D alone. Co‑development agreements with optical OEMs (joint validation timelines and acceptance criteria) substantially reduce time to qualifying production purchases.
- Implement a two‑track procurement strategy: qualify one chemistries primary supplier and one alternative with fast‑swap pathways. Embed price‑adjustment and capacity‑commitment clauses tied to validated performance metrics.
- Accelerate low‑PFAS and compliance‑forward product development. Regulatory forward‑planning — including targeted testing programs and documented environmental dossiers — is becoming a procurement precondition for tier‑one customers.
- Use capital selectively: commit to modular, plug‑and‑play production capacity that can be repurposed across resin families. This reduces stranded asset risk should a particular monomer or application see regulatory or market contraction.
- Prepare M&A and licensing playbooks now. Targets that offer complementary processing expertise, regional manufacturing footholds, or niche IP (e.g., two‑photon polymerization capability, micro‑GRIN architectures) will unlock scale faster than internal build alone.
Closing — why PW Consulting’s study is timely for 2026 planning
The Low‑RI resin market presents a high‑growth, high‑complexity opportunity set. The next 12–24 months will separate firms that can convert technical novelty into reproducible, regulation‑ready manufacturing from those that remain design‑centric without durable commercial moats. PW Consulting’s report pairs quantitative forecasting (2020–2032) with operational playbooks, supplier scorecards, and regulatory roadmaps to help executives translate market momentum into defendable revenue streams in 2026 and beyond.
For commercial teams, R&D leaders, and corporate strategists, the full report provides the granular segmentation, regional and application splits, supplier rankings, and downloadable financial models needed to execute with conviction. Access to the complete data sets and supplier scorecards is available on our report page — a focused read that will materially reduce the time from strategic intent to validated opportunity capture.
For detailed analysis of this topic, please visit the official page: Low Refractive Index Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


