



PW Consulting Forecasts Ophthalmic OCTA Equipment Market to Grow at 9.0% CAGR (2026–2032)

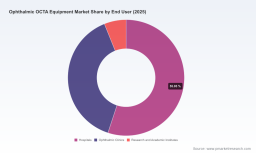
Ophthalmic OCTA Equipment Market — 2026 Strategic Outlook
PW Consulting’s latest industry brief on the Ophthalmic Optical Coherence Tomography Angiography (OCTA) Equipment market provides a focused, decision-ready roadmap for executives preparing budgets, product roadmaps, and M&A strategies in 2026. Built on a validated market model with a 2025 base year and a 2026–2032 forecast horizon, the analysis quantifies a sustained growth trajectory — from approximately USD 585.9 Million in 2025 to an expected USD 660.1 Million in 2026 and a market approaching USD 1.07 Billion by 2032 — reflecting a compound annual growth rate (CAGR) near 9.0% across the forecast window. This brief summarizes the strategic implications we expect to shape supplier and buyer behavior in 2026, highlighting the high-level drivers and tactical levers that matter for capital allocation and competitive positioning.
Ophthalmic Octa Equipment Market
Executive snapshot
- Market trajectory: historical build from 2020 through 2025 supports the forecast starting point (base year 2025); growth accelerates through 2032 under multiple scenario assumptions.
- Forecast metrics: 2026 projection and 2026–2032 CAGR of around 9.0% underpin capital planning and product investment cases.
- Market structure: concentration remains non-trivial, with leading-vendor clusters controlling a significant portion of installed bases — an important factor for entrants and consolidation plays.
Why 2026 is an inflection point
Three converging forces make 2026 a pivotal year for OCTA equipment strategy. First, reimbursement dynamics materially change the economics of advanced retinal imaging. The introduction of CPT code 92137 for computerized retinal diagnostic imaging that includes OCT angiography (effective January 1, 2025) has already re-priced OCTA relative to standard OCT codes under the 2025 MPFS schedule, improving the per-procedure reimbursement proposition for sites that adopt angiography-capable platforms. Operational constraints around billing (for example, bilateral billing rules and combinations with other angiography codes) require tactical coding workflows that we document in the full report.
Ophthalmic Octa Equipment Market
Second, clinical and technological advances — from spectral-domain speed improvements to the increasing commercial maturity of swept-source platforms that deliver deeper imaging and wider fields — are expanding the clinical applications of OCTA beyond retina clinics into glaucoma workflows, anterior segment angiography, and perioperative assessments. Rapid acquisition speeds and modular upgrade paths are now differentiating procurement decisions.
Ophthalmic Octa Equipment Market
Third, capital spending realities are mixed. Hospital capital budgets remain meaningful but cautious: while median capital budgets and increases in capex-to-depreciation ratios indicate persistent demand for equipment lifecycle refreshes, many institutions report plans to defer or reduce large-ticket procurements in response to macro pressures. That dichotomy forces equipment vendors to rethink commercial models, emphasizing flexible finance, demonstrated ROI, and service-led revenue to sustain bookings.
Report — practical content you can use in 2026
PW Consulting’s full report is structured around actionable, transaction-oriented deliverables rather than solely high-level market narration. Highlights include:
- Proprietary market model (2020–2032) with scenario outputs and sensitivity toggles for reimbursement, capital-spend, and technology diffusion assumptions.
- Procurement playbooks for hospitals and multi-site clinic groups including ROI calculators, service contract templates, and trade-in programs designed to accelerate upgrade cycles.
- Competitive product benchmarking that maps imaging capabilities (axial resolution, acquisition speed, field-of-view, multimodal integration), upgradeability, and typical buyer personas.
- Regulatory and reimbursement compendium detailing CPT interactions, billing rules, and payer submission templates to support revenue cycle optimization.
- Commercial strategies for OEMs: pricing and bundling scenarios, go-to-market segmentation, partner ecosystems (AI/software vendors), and near-term M&A targets prioritization.
- Operator-level adoption playbooks for ophthalmic clinics and ambulatory surgery centers that include training protocols, utilization thresholds, and referral economics.
To preserve the strategic value of the IP in our datasets and to respect commercial confidentiality, the release intentionally omits core proprietary segment-level breakdowns from this public brief. The full report contains those detailed splits and is available through our website.
Competitive landscape — what buyers and investors should watch
The competitive map is defined by a mix of established imaging incumbents and fast-moving platform specialists. Device differentiation increasingly centers on acquisition speed, depth-of-penetration (swept-source versus spectral-domain tradeoffs), multimodal integration (fundus, OCT, OCTA), and software-driven analytics. Key vendor strengths observed in our research include:
- Carl Zeiss Meditec AG (Jena, Germany): A product portfolio blending high-throughput imaging with advanced angiography modules, positioning the company for enterprise-level deployments where workflow and instrument ecosystems matter.
- Heidelberg Engineering GmbH (Heidelberg, Germany): Technological leadership in high-resolution vascular imaging and recent regulatory milestones expanding clinical use-cases in pediatrics and supine imaging; the company’s emphasis on image quality and acquisition efficiency is a distinct commercial lever.
- Topcon Corporation (Tokyo, Japan): Strength in swept-source platforms and integrated color fundus imaging, appealing to buyers seeking a consolidated imaging modality for mixed clinical practices.
- Canon Medical Systems Corporation (Otawara, Japan) and NIDEK Co., Ltd. (Gamagori, Japan): Both bring clinically competitive OCTA offerings with a focus on high axial resolution and broad diagnostic coverage for retinal and optic nerve applications.
- Optovue / Visionix (Fremont, CA): Platform flexibility and upgradeability make their solutions attractive to high-volume retina practices focused on iterative performance improvements.
- Optopol, Intalight, Haag-Streit, Huvitz: Regional strengths, cost-competitive models, and focused R&D on swept-source or non-mydriatic capabilities create local-market disruption opportunities, particularly when coupled with regulatory approvals and distribution partnerships.
Recent regulatory and market events that matter
- Intalight secured CE mark approval for a swept-source OCT platform in May 2025 — a near-term enabler for EU commercialization and a signal of growing swept-source competition.
- Heidelberg received successive FDA clearances in 2024 expanding clinical workflows and acquisition efficiency, reinforcing that regulatory momentum continues to shape product launch calendars and competitive windows.
- Reimbursement developments (CPT 92137 and its MPFS valuation) are increasing per-procedure economics for OCTA-capable systems; translating this to net revenue requires operational adjustments that clinics and hospitals must implement.
Strategic implications and recommended actions for 2026
Our research yields clear, actionable recommendations for primary stakeholders:
- OEMs and new entrants: Prioritize modular architectures that enable field upgrades, and design flexible financing and service packages to address buyer capital constraints. Accelerate regulatory filings in high-value geographies and align clinical validation programs to demonstrate reimbursement-supported use-cases.
- Hospital systems and multi-site groups: Use the period following reimbursement repricing to standardize imaging platforms across referral networks. Insist on total cost of ownership (TCO) scenarios that include utilization thresholds, bundled maintenance, and upgrade paths.
- Standalone ophthalmic clinics and ambulatory centers: Negotiate provider-level performance guarantees tied to reimbursement realization and consider subscription-based access models to mitigate upfront capital risk.
- Investors and private equity: Look for consolidation opportunities that combine imaging hardware with analytics/software to capture downstream service and recurring revenue streams. Early-stage targets with validated swept-source IP and regulatory clearance pathways are particularly attractive.
- Distributors and channel partners: Develop bundled offerings combining imaging hardware, AI analytics, and revenue-cycle support to help customers capture reimbursement value quickly and sustainably.
Methodology and credibility
PW Consulting’s conclusions draw on a triangulation of proprietary shipment datasets, primary interviews with hospital procurement leads and OEM commercial executives, regulatory filings, reimbursement schedules, and third-party capital-spend surveys. The base-year 2025 model is built from historical observations (2020–2025) and scenario-tested across multiple sensitivity cases (reimbursement variance, capital spending shifts, and accelerated technology replacement cycles). Our concentration analysis and vendor benchmarking were validated with vendor-provided technical specifications and independent clinical feedback.
Next steps
For executives preparing budgets, product roadmaps, or transaction diligence in 2026, PW Consulting’s full Ophthalmic OCTA Equipment Market report offers the granular segmentation, vendor scorecards, and executable templates needed to act with confidence. This public brief is intended as a strategic primer; our complete dataset and supporting materials — including the model, downloadable playbooks, and a confidential supplier evaluation matrix — are available on request.
- Access the full report for in-depth segmentation, regional and application splits, and the procurement toolkit.
- Contact PW Consulting’s Ophthalmic Equipment Practice to schedule a tailored briefing or a live model walkthrough for your executive team.
PW Consulting — translating market data into practical, high-impact decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Ophthalmic Octa Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


