



PW Consulting: Cross Laser Light Market Poised for 6.0% CAGR — From USD 515.49M in 2025 to USD 775.11M by 2032

Cross Laser Light Market: Strategic Briefing for 2026 — PW Consulting
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a tactical preview of our Cross Laser Light Market study (base year 2025, forecast 2026–2032). This briefing highlights the report’s strategic value for executive decision-making in 2026 — showing the kind of insight and recommendations the full analysis delivers while intentionally reserving detailed segment-level tables and proprietary forecasts for the full report.
Cross Laser Light Market
Market snapshot: what matters to C-suite and product leaders
The cross laser light market reached USD 515.49 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 6.0% over the 2026–2032 forecast window, reaching an estimated USD 775.11 Million by 2032. These headline numbers reflect healthy, steady demand driven by continued investment in construction layout tools, industrial alignment solutions, and growing use in specialized laboratory and medical positioning contexts. For 2026 planning, the takeaway is clear: the market presents incremental growth opportunities that reward targeted product differentiation, supply-chain resilience, and regulatory-compliant design.
Cross Laser Light Market
Why 2026 is a strategic inflection point
-
Technology consolidation. Manufacturers are converging around higher-visibility green-beam systems, integrated drivers for diode modules, and combination units that blend point, line, and cross projections. Product launches in late 2025 and early 2026 signal a move toward higher-brightness modules and 360° coverage for professional use-cases.
Cross Laser Light Market -
Regulatory clarity is tightening. Global safety frameworks such as IEC 60825-1 and updated FDA guidance relevant to surveying, leveling and alignment lasers are raising the bar for compliance. Companies that invest early in certification and documentation avoid costly rework while accelerating channel acceptance.
-
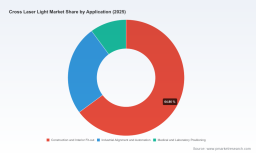
Sector-specific adoption. Construction, interior fit-out, and industrial automation remain the primary end-markets. However, precision positioning in medical and laboratory environments is a growing high-margin niche that rewards higher-spec, certified devices and close OEM partnerships.
Key market dynamics executives must internalize
-
Regulation and standards shape product roadmaps. IEC 60825-1 conformity, CE/TUV safety approvals, and U.S. FDA considerations should be embedded into product development timelines. For hazardous-environment applications, approvals such as MSHA are core to market access in mining and select industrial segments.
-
Product differentiation is increasingly technical. Buyers value high-visibility green beams, robust self-leveling mechanisms, waterproof/shock-resistant housings, integrated electronics for lifetime monitoring, and modular optics that support both cross-lines and point projections.
-
Supply-chain concentration risk. Laser diode availability and the quality of driver electronics are critical bottlenecks. Procurement strategies must consider multi-sourcing, safety stock for key modules, and partnerships with component specialists to avoid production and delivery disruption.
-
Channel economics matter. Traditional professional tool channels remain dominant for jobsite-grade units, while OEM and B2B procurement channels drive volume for industrial and mining modules. Service contracts and aftermarket consumables (batteries, mounts, calibration) are meaningful margin levers.
-
Competitive investments are accelerating. Recent product releases — including high-brightness industrial modules and new 360° electronic self-leveling green cross-line units — indicate incumbents are prioritizing high-visibility, higher-spec models to capture professional users willing to pay a premium.
Competitive landscape: structure, capability clusters, and implications
The market is populated by legacy power tools brands, specialized laser module manufacturers, and vertically integrated industrial suppliers. Each cluster brings different strengths for a 2026 strategy:
-
LAP GmbH Laser Applikationen (Lüneburg, Germany — https://www.lap-laser.com): Known for industrial crosshair lasers (XtrAlign series) with durable designs and long-life modules, LAP is a reference for precision alignment in automotive and wood-processing lines. Their focus on ruggedized, long-lifetime products makes them a natural partner for industrial integrators.
-
Laser Tools Co., Inc. (USA — https://lasertoolsco.com): A leader in intrinsically safe alignment lasers, including MSHA-certified models for hazardous environments. Recent product introductions through late 2025 and early 2026 signal strengthening capabilities in high-brightness, combination systems designed to reduce downtime in heavy industries.
-
World Star Tech Inc. (Markham, Canada — https://worldstartech.com): A module-level specialist that designs diode modules with integrated drivers and optical generators. Their ISO 9001 certification and custom solutions model position them as a preferred supplier for OEMs seeking tailored laser modules for machine vision and instrumentation.
-
Major tool brands — Bosch, DeWalt (Stanley Black & Decker), Hilti, Leica Geosystems, Klein Tools: These firms leverage wide professional distribution, brand trust, and field-oriented features (self-leveling, rugged housings). They compete primarily on visibility, durability, and service networks.
-
Value and scale players — Huepar, Kapro: These manufacturers offer high-feature sets such as 360° green-beam models and competitive pricing, creating pressure in the mid-market but also driving adoption of advanced form factors.
Strategic implication: 2026 is an acquisition- and partnership-friendly environment. Companies seeking rapid capability access (e.g., intrinsic safety, high-brightness modules, custom drivers) should evaluate bolt-on acquisitions, OEM supply agreements, or co-development arrangements rather than attempting multi-year internal builds.
What the full PW Consulting report delivers (practical, operational outputs)
-
Market sizing and validated growth trajectories (top-line and by major application group), with transparent methodology and scenario modelling to stress-test 2026 budgets.
-
Product and technology landscaping: comparative feature matrices, component sourcing maps, and a technology readiness timeline to guide R&D prioritization.
-
Regulatory and compliance playbook: practical checklists for IEC 60825-1, FDA-relevant considerations for SLA devices, CE/TUV pathways, and MSHA approvals where applicable.
-
Competitive diagnostics: concise vendor profiles, recent product-intro tracking, go-to-market maps, and an M&A heatmap identifying likely targets for capability or channel acquisition.
-
Commercial playbook: pricing benchmarks, channel margin models, and a 12-month go-to-market sprint plan (product launches, trade shows, dealer training, and aftermarket subscription pilots).
-
Scenario planning and sensitivity analysis: demand shock, supply constraints, and regulatory tightening scenarios with recommended mitigation actions and trigger points.
Actionable recommendations for 2026 decision cycles
-
Prioritize compliance-first product adjustments. Incorporate IEC 60825-1 alignment at prototype stages and ready FDA-facing documentation for any devices servicing laboratory or medical users — reduce time-to-market friction.
-
Target differentiated optics and driver electronics. Invest in green-beam visibility and integrated driver modules to win professional users who value brightness and stability; consider co-development with module specialists to shorten delivery cycles.
-
Hedge supply risk. Lock multi-year component contracts for key diode suppliers, and include dual-sourcing clauses in vendor agreements. Maintain strategic buffer inventory for critical subassemblies through at least H1–2026.
-
Rebalance channel strategies. For premium professional units, leverage branded tools channels and service contracts; for industrial volume modules, prioritize OEM partnerships and direct B2B procurement channels.
-
Explore targeted M&A and partnerships. Evaluate small, highly specialized module makers and intrinsic-safety-certified suppliers as acquisition candidates to accelerate capability without heavy CAPEX.
-
Monetize aftermarket services. Develop calibration-as-a-service, extended warranty packages, and consumable bundles to improve lifetime value and stabilize revenues against cyclical equipment purchases.
Using this preview in your 2026 planning
This briefing is a strategic overview intended to catalyze executive alignment. For product planning, prioritize safety certifications and optics upgrades in Q1–Q2 2026. For procurement and supply-chain directors, begin contract talks and alternative sourcing pilots now. For corporate development teams, request our M&A heatmap and target shortlist to accelerate diligence.
Next steps and where to get the full intelligence
The full PW Consulting Cross Laser Light Market report contains the detailed segment-by-segment models, pricing matrices, regional demand curves, and vendor scorecards that support the strategic recommendations above. This release intentionally omits the granular segmentation tables and proprietary metrics so that decision-makers who require actionable numbers and executable roadmaps will access the full dossier and bespoke briefings.
Contact PW Consulting to request the full report, receive the vendor scorecard, or schedule a custom briefing to translate these insights into a 90‑day action plan for your business.
— PW Consulting, Strategy & Industry Research
For detailed analysis of this topic, please visit the official page: Cross Laser Light Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


