



PW Consulting Forecast: Laser Line Dielectric Mirror Market Poised to Reach USD 675.05 Million by 2032

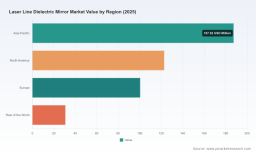
Laser Line Dielectric Mirror Market 2026: Strategic Implications from PW Consulting’s Forward-Looking Analysis
PW Consulting’s latest market study on Laser Line Dielectric Mirrors offers a practical, decision-focused roadmap for executives, product leaders, and supply-chain managers planning moves in 2026 and beyond. Combining a structured forecasting framework with vendor benchmarking, technology readiness assessments, and supply-chain stress-testing, the report translates market momentum into actionable options—without sacrificing the rigor required for capital allocation, sourcing strategy, and product roadmap prioritization.
Laser Line Dielectric Mirror Market
Macro snapshot: steady growth, concentrated supply, rising strategic risk
Our analysis shows that the global laser line dielectric mirror market reached USD 441.6 Million in 2025 and is expected to expand at a compound annual growth rate (CAGR) of approximately 6.25% through our forecast window. Under PW Consulting’s base-case projection, this trajectory takes the market toward roughly USD 675 Million by the end of the planning horizon. Growth is driven by sustained demand in industrial laser processing, medical instrumentation, scientific research, and defense applications—each governed by distinct performance and procurement imperatives.
Laser Line Dielectric Mirror Market
Market structure matters. Measured concentration metrics indicate a mid-level consolidation: the three largest players account for just over 32% of market value while the five largest capture roughly 48%. That profile creates a market where specialized high-performance vendors coexist with agile regional suppliers—an environment that rewards technical differentiation, supply-chain robustness, and downstream partnerships.
Laser Line Dielectric Mirror Market
Why this matters for 2026 decision cycles
- Capital allocation: A multi-year growth path with a mid-single-digit CAGR validates incremental capacity investments for specialist coatings (e.g., ion-beam sputtering, IBS) and for high-LIDT product lines, but argues against broad-based greenfield capacity unless tied to a clear OEM commitment.
- Product strategy: Demand is bifurcating—commodity mirrors optimized for price and lead-time coexist with premium, application-specific mirrors (ultrafast, high-LIDT, multi-wavelength stacks). R&D and product roadmaps should prioritize either scale or technologic differentiation, not both, unless supported by strategic partnerships.
- Sourcing & procurement: Recent export controls and raw-material constraints increase the cost of downtime. Procurement teams should adopt dual-sourcing, strategic inventory, and supplier qualification playbooks to reduce single-point-of-failure exposures.
Supply-chain headwinds and material realities
Two structural factors are reshaping supplier economics and procurement risk. First, regulatory measures and export controls imposed by major producing countries have tightened access to certain coating materials and specialty substrates, extending lead times and introducing price volatility. Second, core substrates and coating architectures—ranging from fused silica and Zerodur to multi-micron dielectric stacks—remain the technical backbone of performance claims, with standard high-reflectance coatings commonly requiring several microns of deposition for peak performance at common laser lines.
For procurement and operations leaders, this means three pragmatic responses in 2026: (1) execute supplier redundancy and near‑shoring where feasible; (2) qualify alternative materials and process routes preemptively; and (3) incorporate scenario-based buffer stock policies that balance working capital with revenue-at-risk from production interruptions.
Competitive landscape: differentiated capabilities, clear stratification
The competitive set spans long-established opto-mechanics houses, specialist thin-film coaters, and vertically integrated OEMs. Across the vendor universe, capability patterns are clear: a subset of suppliers focus on ultra-high-reflectivity and high laser-induced damage threshold (LIDT) mirrors for high-energy and ultrafast lasers; others emphasize catalog breadth, modularity, or cost-competitive volume offerings.
- Specialist high-performance vendors: Companies that promote ultra-high reflectivity (>99.9% in some cases) and elevated LIDT dominate premium niche segments. These companies are attractive partners for OEMs and for defense and scientific users whose procurement decisions prioritize lifetime and performance over unit price.
- Catalog and systems suppliers: Larger optics firms maintain broad catalogs and tight integration with system-level customers. Their strengths include supply continuity, global service networks, and established qualification processes for OEM acceptance.
- Regional and fast-follow manufacturers: Agile manufacturers, particularly those focused on UV and narrowband variants, are competing on lead time and customization. They can capture aftermarket and mid-tier OEM work, especially where price sensitivity is higher.
Representative market participants include legacy optics houses and specialist coating firms—in each case, success derives from specific technical propositions: high-damage-threshold coatings, IBS and e‑beam deposition expertise, large-area mirror assemblies, and multiwavelength/broadband designs. Recent vendor developments illustrate how players are pressing both product and go-to-market advantages through catalog refreshes, new thin-film series, trade-show product validation, and supplier excellence recognition.
What PW Consulting’s report delivers to practitioners
PW Consulting’s Laser Line Dielectric Mirror report is intentionally operational. Key deliverables include:
- Demand-side segmentation and scenario models that translate application trends into volumetric and revenue risk profiles under multiple demand-shock scenarios;
- Vendor scorecards built from capability, capacity, quality (including LIDT performance) and lead-time metrics—designed for procurement RFIs and strategic sourcing;
- Technology readiness assessments covering coating processes (IBS, ion-assisted deposition, e-beam), substrate choices, and emerging material substitutes with cost-performance trade-offs;
- Supply-chain resilience playbooks—dual-sourcing matrices, buffer-stock algorithms, and localization decision frameworks calibrated to 2026 procurement constraints;
- Commercial playbooks for OEMs and system integrators outlining bundling strategies, warranty & test-spec alignment, and aftermarket monetization opportunities;
- Financial and M&A frameworks for buyers evaluating tuck-ins, capability buys, or capacity-driven acquisitions—complete with sensitivity sweeps tied to material price and lead-time risk.
Each deliverable is accompanied by reproducible templates, step-by-step supplier evaluation checklists, and a library of vendor profiles that allow teams to move from insight to execution quickly.
Strategic recommendations for 2026
- Prioritize modular investments: For manufacturing players, invest selectively in modular coating and metrology upgrades that shorten qualification cycles for new coatings. This reduces time-to-market for high-margin specialty mirrors.
- Lock in strategic supply: Negotiate multi-year offtake or volume agreements with high-quality substrate suppliers and leading coaters; structure contracts with material-indexed pricing and lead-time SLAs to hedge against export-control volatility.
- Segment go-to-market: Define separate product streams for premium, specification-driven customers and for catalog/volume segments. Align sales incentives and R&D roadmaps accordingly.
- Build resilience into procurement: Implement a phased dual-source plan for critical coating materials and consider localized inventory hubs in target end-markets to shorten response times for OEM customers.
- Explore targeted M&A: Buyers seeking technical depth should prioritize bolt-on acquisitions that add IBS capabilities, high-LIDT test labs, or domain expertise in ultrafast optics rather than broad capacity plays.
Regulatory watch and material innovation
Regulatory developments affecting exports of certain materials and production equipment are a live issue. Firms should adopt an early-warning approach to policy changes and embed regulatory scenario analysis into procurement cadence. In parallel, material substitution and process innovation (e.g., lower-dependence coating stacks or alternative rare-earth-free architectures) represent a medium-term de‑risking pathway that should be part of R&D roadmaps for 2026–2028.
Call to action: what to ask next
For executives shaping 2026 plans, the immediate questions are operational rather than theoretical: Which suppliers will you qualify this year? How much strategic inventory is defensible? Where will you place next incremental investment—capability, geography, or partner alliance?
PW Consulting’s report equips leaders to answer these questions with concrete numbers, vendor evaluations, and scenario-tested sourcing playbooks. To preserve the competitive value of granular segment-level forecasts and the vendor scorecards that power procurement decisions, PW Consulting provides full datasets, customized sourcing simulations, and client-side workshops through the complete report package.
Closing perspective
The laser line dielectric mirror market is mature in its core physics but dynamic in its commercial and supply-chain dimensions. 2026 will be a year where winners are defined less by basic optics know-how and more by agility—how fast they can qualify alternative materials, contract for critical supplies, and align product portfolios to differentiated end-user needs. PW Consulting’s analysis is designed to move teams from strategic intent to executable programs within months, not quarters.
For access to the full report, including segment-level forecasts, vendor scorecards, and the reproducible templates mentioned above, request the PW Consulting Laser Line Dielectric Mirror 2026 report and schedule a briefing with our senior analysts. The detailed datasets and supplier benchmarking are intentionally gated to ensure competitive confidentiality and to provide clients with tailored decision-support for their 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Laser Line Dielectric Mirror Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


