



PW Consulting: M‑Cresol Market Set to Grow at 3.9% CAGR, Hitting USD 707.23 Million by 2032

PW Consulting: Strategic Brief — Global M‑Cresol Market Outlook (2026–2032)
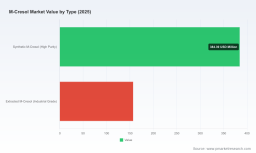
PW Consulting today releases an executive briefing that encapsulates the strategic value of our forthcoming M‑Cresol Market report for corporate decision‑making in 2026. The global M‑cresol market reached roughly USD 541.1 Million in our 2025 base year and, under the scenarios modelled in this study, is projected to grow at a compound annual growth rate (CAGR) of approximately 3.9% across the 2026–2032 forecast window, approaching the low‑to‑mid USD 700 Millions range by the end of the period. This briefing outlines the actionable intelligence and risk frameworks built into the full report — intentionally high‑level here, with granular tables and firm‑level metrics reserved for the complete publication.
M Cresol Market
Why this report matters for 2026 decision cycles
-
Procurement precision: Our price‑and‑cost models translate feedstock volatility into contract negotiation levers and inventory strategy recommendations, enabling procurement teams to lock in margins with index‑linked and outcome‑based clauses.
M Cresol Market -
Operational resilience: Producers can prioritise capex to address regulatory compliance and feedstock substitution, supported by plant‑level cost curve diagnostics that identify the assets most at risk from margin compression.
M Cresol Market -
M&A and portfolio allocation: Investors receive a decision framework that flags consolidation opportunities and stress points in the value chain based on concentration metrics, margin pools and geography‑driven tariff exposure.
-
Policy and sustainability planning: The report maps environmental and safety regulation implications across operating models, providing a timeline for necessary investments in pollution control and waste management to avoid regulatory shock in 2026 and beyond.
What is included in the PW Consulting M‑Cresol Market report
-
Market sizing and forecast (2020–2032) with top‑line scenarios and sensitivity analyses that isolate the impacts of feedstock prices, energy inflation and trade policy shifts.
-
Price formation and production cost modelling: dynamic models that tie toluene/benzene/naphtha indices to per‑tonne production economics and downstream price pass‑through.
-
Proprietary competitive benchmarking: ranked scorecards across capacity, product quality (including high‑purity synthetic grades), technology stack, asset age and disclosed commercial strategies.
-
Supply‑chain stress tests and trade‑flow simulations that quantify the commercial consequences of tariff changes, feedstock shortages, and regional energy price divergence.
-
Commercial playbooks for buyers and sellers, including sample contract language, hedging strategies, inventory optimisation algorithms and go‑to‑market templates for specialty grades.
-
M&A, greenfield and brownfield investment decision matrices: NPV and IRR outputs under multiple policy and price scenarios, and an acquisition screening model that flags attractive targets by margin profile and geographic arbitrage potential.
-
Regulatory and ESG readiness checklists, including estimated capital requirements to meet evolving phenolic compound controls and worker safety expectations.
Market dynamics shaping 2026 strategy
Two structural forces dominate the current landscape: feedstock dependency and regulatory pressure. M‑Cresol production is intrinsically linked to petroleum‑derived feedstocks (notably toluene and benzene), and movements in these raw material markets materially shift production economics. The latter half of 2025 showed divergent signals — a moderation in feedstock‑driven costs in some regions attributable to naphtha declines, while toluene prices ticked up in others, tightening margins for producers exposed to that index. Our models convert these movements into clear profitability thresholds for different production routes.
Trade policy is an equally consequential variable. Phenolic compounds under HTS code 3814 have been exposed to trade measures that add a material tariff burden on certain imports; this, combined with region‑specific levies introduced in early 2025, reshapes competitive dynamics by increasing landed costs for affected supply. The net effect is a re‑rating of regional arbitrage: some local assets gain competitiveness, while cost‑sensitive import routes become less viable without structural price concessions.
Regulatory trends on environmental controls and worker safety are converging across major markets. Phenolic compounds are receiving increased regulatory scrutiny, raising the bar for compliance spend. Our scenario work identifies the production footprints most sensitive to these regulatory shifts, and estimates the capital intensity of remediation investments required to preserve operations under tightening rules.
Competitive landscape — concentrated but segmented
The M‑Cresol supply base is materially concentrated, with the largest three suppliers controlling a majority share and the top five nearing solid concentration. This structure produces two commercial realities: first, meaningful pricing power exists at the top end for premium, high‑purity synthetic grades; second, supply risks can be acute for specialised downstream consumers reliant on a narrow set of suppliers.
Key industry participants analysed in the report include LANXESS AG (Cologne), Sasol Limited (Johannesburg), Mitsui Chemicals (Tokyo), Atul Ltd (Valsad), a number of Chinese producers with substantial regional capacity, and dedicated specialty players in Japan and India. Each exhibits different strategic postures: some prioritise high‑purity synthetic routes suited to pharmaceutical and electronics applications; others leverage byproduct or coal‑tar streams to serve industrial grade markets. Coal‑gasification byproducts, for example, create a distinctive cost profile and route to market that incumbent commodity players can exploit.
We include an appraisal of recent industry developments — such as the December 2025 decline in production costs in some regions tied to feedstock softening — and assess how these episodic events alter competitive positioning over a 12–18 month horizon. The report’s firm‑level profiles synthesize disclosed strategy with inferred positioning from observed trade flows and capacity trends.
Strategic imperatives and recommended actions for 2026
-
For producers: prioritise product differentiation through investment in purification and control technologies to capture margins in high‑purity segments; adopt flexible feedstock pathways and hedge strategies to blunt short‑term index volatility.
-
For buyers (agrochemical, pharmaceutical, resin manufacturers): diversify supplier portfolios across production routes and geographies; negotiate volume‑weighted price collars and conditional supply commitments linked to feedstock indices to share risk with suppliers.
-
For investors and M&A teams: screen assets using the report’s concentration and margin maps — target bolt‑on plays that add purity capability or geographic access to markets shielded from high tariff exposure.
-
For policymakers and corporate sustainability leaders: phase‑in compliance expenditures and pilot waste‑minimisation technologies now to avoid operational interruptions, and consider incentives that lower the upfront cost of environmental upgrades.
What we do not disclose here (and why you need the full report)
This briefing intentionally omits the granular segmentation tables, regional allocations by application, company volume shares and plant‑level cost tables that drive transaction‑grade decisions. Those datasets underpin the pricing and M&A models and are included exclusively in the full PW Consulting report and accompanying data workbook. If you are evaluating a sourcing strategy, capex decision, or acquisition in 2026, relying on headline growth rates without access to the underlying segmentation and trade‑flow matrices will materially understate execution risk.
How PW Consulting supports executive teams
Our advisory work pairs the quantitative outputs from this market study with hands‑on implementation support: bespoke procurement playbooks, due‑diligence templates for asset purchase, negotiation warrooms for contract renewals, and regulatory compliance roadmaps. Engagements typically begin with a 2–4 week diagnostic that calibrates the syndicated models to your firm’s procurement mix, asset locations and risk appetite.
Next steps
For access to the full M‑Cresol Market report, plant‑level datasets, executable commercial playbooks and a private briefing with the PW Consulting chemicals team, visit the PW Consulting website or contact our research desk. The full report contains the proprietary scenarios, firm benchmarking and transaction models essential for shaping defensible strategies in 2026 and beyond.
PW Consulting — converting market complexity into strategic advantage.
For detailed analysis of this topic, please visit the official page: M Cresol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


