



PW Consulting: Synthetic Bone Graft Market to Hit USD 2,147.56 Million by 2032, Growing at a 6.72% CAGR

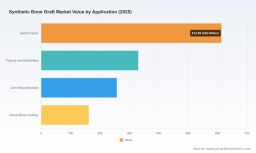
Synthetic Bone Graft Market — 2026 Strategic Brief: PW Consulting Executive Insights
As healthcare providers, device manufacturers, and investors plan their 2026 agendas, the synthetic bone graft market presents a mix of steady growth, technology-driven disruption, and regulatory inflection points that will separate winners from laggards. PW Consulting’s new market study (base year 2025; forecast 2026–2032) shows the industry advancing from approximately USD 988.45 million in 2020 to USD 1,362.16 million in 2025, with our base-case projection growth to roughly USD 2,147.56 million by 2032 — an implied compound annual growth rate (CAGR) of 6.72% across the 2026–2032 forecast window. This brief highlights the strategic implications of those dynamics for corporate decision‑makers in 2026 and explains what practical intelligence our full report delivers (note: fine-grained regional and subsegment tables are reserved for the full report to preserve the report’s role as the primary source of granular market detail).
Synthetic Bone Graft Market
Why 2026 Is a Pivotal Year for Strategic Positioning
-
Regulatory momentum is reshaping product trajectories. The device class and clearance pathway (most synthetic bone grafts reach market via FDA 510(k) as Class II devices) remains familiar, but recent expanded clearances and novel material approvals are creating new commercial use-cases and competitive pressure.
Synthetic Bone Graft Market -
Clinical evidence and reimbursement signals are converging. While many bone substitutes are currently treated as inherent to the primary surgical procedure, a small but growing set of regulatory and coding developments are enabling distinct pathways to recognition — and, therefore, value capture — for differentiated products.
Synthetic Bone Graft Market -
Material innovation is accelerating adoption vectors. Advances in hydroxycarbonapatite (HCA) chemistries, bioactive glass formulations, magnesium-based void fillers and flowable, stand-alone graft technologies are forcing incumbents and challengers to re-evaluate R&D, manufacturing and market-entry strategies.
Core Macro Findings (Executive Summary)
-
Market size and trajectory: The market has demonstrated consistent expansion through 2020–2025 and, under our base-case assumptions, is expected to grow at ~6.72% CAGR during 2026–2032, doubling market value in roughly a decade. This trajectory supports both organic growth strategies and continued M&A activity.
-
Moderate market concentration: Top-three vendors account for just under half of market revenue (CR3 ≈ 48.6%), and the top-five control approximately 62.4% — a structure that favors scale but leaves meaningful room for specialist players with differentiated technology or clinical positioning.
-
Technology and clinical differentiation matter most: Manufacturers that can combine meaningful clinical evidence, clear regulatory positioning, and defensible manufacturing scale will be able to extract premium pricing or secure preferred placement in hospital formularies.
Competitive Dynamics: What the Leading Players Are Doing
-
Incumbent orthopedics majors (e.g., market leaders with integrated orthopedics portfolios) continue to leverage broad commercial channels and bundling strategies. Their scale allows heavy investment in surgeon education, logistics and clinical studies.
-
Specialist companies are accelerating clinical differentiation. Recent examples include next‑generation HCA-based launches, expanded device clearances that broaden indications beyond spine into tumor/trauma/osteomyelitis use-cases, and novel material approvals (notable launches and clearances in 2025 and 2026). These moves indicate a two‑track market: standardized commodity substitutes versus premium, evidence-backed differentiated products.
-
M&A and partnership flows will intensify. Given the moderate concentration and fragmented mid-market, strategic acquirers will target bolt-on technologies (e.g., bioactive glass, magnesium-based fillers, flowable / stand-alone grafts) to broaden clinical portfolios quickly.
Selected Vendor Posture and Implications
-
Large, diversified orthopedics firms: Continue to compete on reach and integrated solutions; their play is to defend surgical channels and embed substitutes into broader biologics portfolios.
-
Focused innovators: Recent regulatory and commercial wins from novel-material specialists demonstrate the commercial viability of seeing differentiated biology and delivery as a scalable route-to-market.
-
Smaller technology developers: Regulatory clearances for new chemistries and delivery formats create acquisition interest, but successful scaling requires early commitments to manufacturing quality, health economic evidence and surgeon adoption programs.
Practical, Actionable Content in the Full Report
PW Consulting’s full market study is built for decision-makers and is intentionally operational. The report includes:
-
A fully transparent market model (historical 2020–2025 + detailed forecast 2026–2032) with scenario toggles to test adoption rates, pricing sensitivity, reimbursement shifts and regulatory outcomes.
-
Commercial playbooks for new product launches, including sample surgeon engagement frameworks, hospital procurement approaches, and distributor/channel strategies by product archetype.
-
Regulatory and reimbursement trackers that map likely 510(k) comparators, evidence thresholds for expanded indications, and pathways to improved coding or coverage visibility.
-
Competitor profiles and benchmarking (product portfolios, go-to-market footprint, pipeline assets and recent corporate events), together with a M&A target shortlist and valuation range methodologies.
-
Clinical evidence roadmaps and RWE study templates to support HTA, payer conversations and hospital adoption cases.
Strategic Playbook for 2026 — Recommended Actions
-
Prioritize differentiated materials: Allocate R&D resources to chemistries with meaningful clinical differentiation (e.g., bioactive glass, magnesium formulations, engineered HCA) or to delivery formats that expand indications (flowable, injectables, stand-alone grafts). Differentiation reduces direct price competition with commoditized ceramics.
-
Build regulatory roadmaps early: For new materials and expanded indications, engage regulators early to clarify substantial equivalence strategies, pre‑submission feedback and potential data requirements. Recent 510(k) precedents suggest that expanded claims can materially widen addressable markets when supported by targeted clinical evidence.
-
Design reimbursement and value dossiers in parallel with trials: Because many suppliers still face “inherent-to-procedure” reimbursement norms, sponsors should invest in health economic models and real-world evidence demonstrating incremental value (reduced reoperation, faster fusion, lower complication rates) that can underpin contracting conversations.
-
Refine commercial segmentation: Focus sales resources on high-opportunity surgical specialties and centers of excellence where product differentiation translates to formulary preference. Pursue strategic OEM/distributor partnerships where internal reach is limited.
-
Prepare for M&A play: Companies with unique materials or evidence packages should prepare sell-side materials now; acquirers should actively screen mid-market innovators addressing spine and complex void-filling indications.
-
Invest in manufacturing resilience: New material classes often require different production and quality infrastructure. Early capex planning reduces time-to-market risk and protects gross margins as adoption rises.
Signals to Monitor — 12 to 24 Month Watchlist
-
Regulatory clearances that broaden labeled indications from spine-only to tumor/trauma/osteomyelitis applications.
-
New CPT or reimbursement guidance that shifts payment from “inherent” to reportable, or the assignment of RVUs to category III codes.
-
Large-scale RWE or randomized studies showing durable clinical benefits (fusion rates, reoperation avoidance) that justify differential pricing.
-
Material supply chain pressure or production innovations that change cost curves for ceramics, polymers or metallic fillers.
-
M&A activity clustering around differentiated chemistries or flowable/stand‑alone graft technologies.
Concluding Perspective and Call to Action
For executives mapping 2026 priorities, the message is clear: the synthetic bone graft market is large, growing and selectively open to premiumization through material and clinical differentiation. The measured CAGR and the market’s concentration profile indicate that both scale and specialty plays can be profitable — but each requires a distinct set of commitments in evidence generation, regulatory strategy and channel execution.
PW Consulting’s full Synthetic Bone Graft Market report contains the granular segmentations, regional splits, price decks and downloadable financial model you need to translate these insights into executable plans. To access the detailed tables and the operational toolkits referenced here — including the forecast model and competitor scorecards — please visit our report landing page or contact your PW Consulting account executive.
For detailed analysis of this topic, please visit the official page: Synthetic Bone Graft Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


