



PW Consulting Market Insight: Casting & Splinting Sector to Hit USD 4,580.0 Million by 2032, Growing at a 6.18% CAGR (USD 3,010.0 Million in 2025; Top‑5 Firms Hold 56.8%)

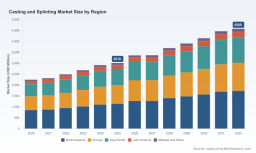
PW Consulting Releases Strategic Preview: Casting and Splinting Market Outlook to 2032 — A Tactical Guide for 2026 Decision-Makers
PW Consulting today publishes a strategic preview of our forthcoming Casting and Splinting Market report, designed to inform executive decision-making in 2026. Anchored on a 2025 base year and a five‑year historical window (2020–2025), the research models the market through 2032 under a 6.18% compound annual growth rate (CAGR). The preview highlights macro drivers, competitive movement, regulatory and reimbursement headwinds, and the practical tools in the full report that procurement leaders, product teams, and investors will rely on to set strategy in the year ahead.
Casting And Splinting Market
Why this preview matters for 2026 planning
-
Timing: With procurement cycles, capital planning and product roadmaps set in 2026, understanding where value pools expand and where margin pressure intensifies is essential for prioritizing investments.
Casting And Splinting Market -
Clarity: The market is transitioning from commodity immobilization products toward performance-differentiated solutions (lightweight materials, breathable systems, and customized devices). Executives need a concise translation of these trends into actionable choices.
Casting And Splinting Market -
Risk mitigation: Supply‑chain and raw‑material concentration, evolving reimbursement rules, and regulatory review pathways create decision points that can materially affect go‑to‑market timing. This preview flags those inflection points.
Macro picture — growth, concentration and the strategic implications
The casting and splinting sector is on a sustained growth path from the 2025 baseline, driven by demographic pressure, increasing elective orthopedic procedures, sports-medicine demand, and faster adoption of advanced materials and personalized devices. Our model projects robust expansion to 2032 on a mid-single‑digit CAGR (6.18%), reflecting both underlying clinical demand and product substitution dynamics.
Market concentration metrics point to a moderately consolidated landscape: the top three players account for a meaningful share of industry revenues, and the top five approach parity with other medical consumables segments. This structure favors scale players with broad distribution and R&D resources, while leaving strategic space for agile specialists to capture premium niches through innovation or service differentiation.
Regulatory, reimbursement and procurement dynamics you cannot ignore
-
Reimbursement complexity: Casting and splinting supplies continue to be governed by HCPCS codes (e.g., Q4001–Q4051), which differentiate by material type, patient age bands and anatomic site. Accurate coding and documentation (neurovascular assessments, wound status) remain essential to secure appropriate reimbursement.
-
Regulatory pathways: New materials and device designs typically follow FDA 510(k) pathways. Manufacturers planning material substitutions, bio‑based resins, or integrated electronics should allocate time and budget for regulatory validation early in product development.
These two levers—reimbursement and regulatory—are primary gating factors for commercial adoption and can materially alter ROI timelines for new product initiatives.
Material and technology shifts: where innovation is concentrating
Material substitution is a dominant theme. Fiberglass and other synthetic composites continue to edge out traditional plaster in many clinical settings due to superior strength‑to‑weight ratios and faster setting times. At the same time, thermoplastics and 3D‑printed custom splints are emerging as high‑value options where comfort, fit and reduced patient follow‑up matter. Expect innovation to cluster around three areas:
-
Performance materials — lighter, breathable, faster-curing formulations that enhance patient comfort and throughput in emergency and outpatient settings.
-
Customization — 3D printing and thermoformable systems that enable better fit and potentially shorter immobilization windows for select indications.
-
Service augmentation — modular systems and disposables that reduce clinician application time and improve infection control protocols.
Competitive landscape — patterns from recent activity
Our competitive review examines legacy incumbents, specialist innovators, and global distributors. Key movements observed through late‑stage 2025 and early 2026 include product launches featuring bio‑based resins and thermo‑responsive technology, modular high‑ventilation systems aimed at sports and emergency use, and the introduction of 3D‑printed custom splints for personalized care.
Selected strategic behaviors and implications:
-
Product innovation by incumbents: Established manufacturers are refreshing portfolios with semi‑rigid, breathable tapes and modular splinting systems that directly target clinician workflow and patient comfort. These moves are defensive (protecting share) but also open premium price points.
-
Channel partnerships and distribution scale: Recent strategic partnerships to expand hospital and clinic coverage underline the importance of commercial reach and value-added service levels in procurement negotiations.
-
Specialist play for customization: Additive manufacturing entrants and thermoplastic specialists are carving out use cases where bespoke fit and comfort translate into measurable clinical benefits — a potential pathway to adjacent service revenues.
Our full competitive mapping profiles major players and their strategic postures, enabling clients to benchmark product pipelines, distribution strengths, and M&A appetites.
What the full report contains — practical tools for strategy teams
The full PW Consulting report goes beyond narrative and delivers operational tools that executives can deploy immediately. Highlights include:
-
Market sizing and multi‑scenario forecasts through 2032 (base year 2025), with sensitivity testing for adoption curves and price migration.
-
A validated segmentation framework (by product family, material class and channel) and growth drivers for each segment. Note: detailed segment tables and regional splits are available in the full report.
-
Competitive intelligence dossiers on incumbent manufacturers, distributors and specialist entrants — including recent product launches, partnership activity and strategic roadmaps.
-
Reimbursement mapping aligned to HCPCS codes and practical documentation checklists to maximize reimbursement capture.
-
Regulatory playbook outlining common 510(k) pitfalls and timelines for material and design changes.
-
Supplier and raw‑material risk matrix and mitigation playbook for procurement teams.
-
M&A and partnership screening criteria and a short‑list of mid‑market targets matched to acquirers by strategic fit.
How to apply these findings in 2026 — tactical recommendations
-
For manufacturers: Prioritize portfolio upgrades that reduce clinician time and improve patient experience (breathability, weight, cure time). Allocate regulatory budget early when integrating new resins or 3D processes.
-
For distributors: Invest in value‑added services (training, application support, digital ordering) to defend margins as product commoditization continues in mainstream lines.
-
For hospitals and health systems: Reassess procurement specifications to balance unit cost against clinician time and downstream outcomes; leverage reimbursement mapping to avoid under‑coding.
-
For investors and PE: Identify targets with differentiated IP in materials or scalable customization workflows; prioritize targets with clear reimbursement and regulatory pathways.
Methodology and data integrity
PW Consulting’s forecast combines historical market data (2020–2025), primary interviews with clinicians, procurement leaders and manufacturers, and a proprietary demand model that projects out to 2032. Financials are expressed in USD (Millions) with 2025 used as the base year for forward valuation. Competitive concentration metrics and scenario variance are calculated using audited company disclosures and verified secondary sources. Where applicable, sensitivity runs illustrate upside adoption of advanced materials and downside scenarios driven by reimbursement pressure.
Next steps — secure the full intelligence
This preview is intended to orient 2026 strategy planning and to highlight where granular intelligence is most valuable. The full report contains the segment tables, regional breakdowns, unit pricing benchmarks, and downloadable templates that enable immediate operational action. PW Consulting invites commercial leaders, product heads, and investors to access the complete dataset and bespoke advisory services to translate these insights into a 90‑day action plan.
To obtain the full Casting and Splinting Market report and discuss tailored strategic engagements, please visit the PW Consulting research center or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Casting And Splinting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


