



PW Consulting: Secondary Medical Diagnosis & Treatment Microscope Market Poised to Grow at an 8.15% CAGR, Unlocking Major Opportunities

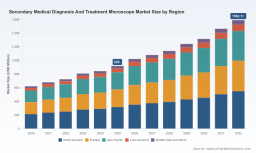
Secondary Medical Diagnosis and Treatment Microscope Market: Strategic Preview for 2026 Decisions
PW Consulting is pleased to release a strategic preview of our forthcoming market research report, Secondary Medical Diagnosis And Treatment Microscope Market (base year 2025). This briefing distills the high‑confidence insights executives and investors will need to set winning strategies in 2026 — from capital allocation to product roadmaps, regulatory timing and M&A prioritization — while reserving the granular, model‑driven segment outputs for the full report.
Secondary Medical Diagnosis And Treatment Microscope Market
Executive snapshot: a growing, technology‑led capital equipment market
The secondary surgical and diagnostic microscope market has transitioned from optical‑dominated equipment to a hybrid ecosystem where digital visualization, heads‑up displays, and AR fluorescence are now standard differentiators. Our market model shows the total market expanded from approximately USD 621.8 Million in 2020 to USD 920.0 Million in 2025, and is forecast to continue at an 8.15% compound annual growth rate through 2032 — reaching roughly USD 1,592 Million by the end of the forecast horizon. This trajectory reflects a mix of replacement dynamics in mature hospitals, new adoption in high‑volume specialty suites, and incremental revenue from digital modules, software, and services.
Secondary Medical Diagnosis And Treatment Microscope Market
Why this matters for 2026 strategic choices
- Capital investment planning: Procurement cycles for capital equipment are lengthening, and the growing attachment of software and visualization modules changes lifetime value calculations. Organizations that assume a purely hardware depreciation model risk underestimating recurring service and upgrade revenue potential.
- Product development prioritization: Buyers are valuing interoperability, ergonomics and team‑centric visualization features (3D/4K, heads‑up, AR fluorescence). Roadmaps that convert optical excellence into digitally enabled workflows capture disproportionate share during upgrade cycles.
- M&A and partnership playbooks: The market shows moderate concentration among established OEMs while leaving niches for focused innovators. Strategic bolt‑ons that add AI‑assisted visualization, fluorescence capability, or OR integration platforms will accelerate time‑to‑value for acquirers.
Market structure and concentration — what incumbents and challengers should know
The competitive landscape remains a blend of long‑standing optical specialists and aggressive digital entrants. Market concentration is meaningful: the top three players control a substantial portion of industry revenue, and the top five entities account for a clear majority. For market entrants, this implies that commercial strategies must be surgical — either targeting underserved clinical workflows and geographies or offering compelling platform interoperability that obviates incumbent switching costs.
Secondary Medical Diagnosis And Treatment Microscope Market
Technology trends shaping buyer behaviour
- Digital visualization is table stakes. Heads‑up displays, 3D/4K exoscopes, and hybrid optical/digital systems are no longer optional for high‑volume neurosurgery and ophthalmology suites. These features materially improve ergonomics, teaching and team alignment in the OR.
- Augmented fluorescence and task‑specific imaging are moving from experimental to procedural standard. Fluorescent visualization for tumor margins and intraoperative tissue characterization is gaining regulatory and clinical traction, changing feature roadmaps for microscope manufacturers.
- Service and software monetization. After‑sales software features (workflow integration, OR video management, analytics) are increasingly the lever for margin expansion and customer retention.
Regulatory and reimbursement context — near‑term considerations
Regulatory activity in early 2026 reinforces the move toward digital adjuncts. Notably, U.S. regulatory clearances enabling intraoperative fluorescence visualization have expanded options for neuro‑oncology workflows. In parallel, the U.S. FDA’s reclassification of certain optical diagnostic devices signals that agencies are focusing on balancing access with device controls — a dynamic companies must track when launching imaging adjuncts or diagnostic analytics.
On reimbursement, surgical microscopes continue to be supported indirectly through existing DRG and CPT pathways tied to procedures (neurosurgery, ophthalmology, ENT), rather than via discrete hardware codes. That structural fact shapes sales cycles: hospital capital committees evaluate microscopes as part of procedural productivity and clinical outcome investments rather than standalone revenue generators.
Competitive landscape: capabilities, differentiators and strategic playbooks
The market’s profile mixes global optical leaders and fast‑moving digital innovators. Across the competitive set, three recurring strategic archetypes have emerged:
- Platform incumbents that leverage optical heritage while iterating digitally. These firms compete on imaging quality, brand trust and integrated workflow solutions for multispecialty ORs.
- Focused ophthalmic specialists that optimize red reflex, coaxial illumination and ergonomics for eye surgery. Their play emphasizes clinical outcomes and high procedural throughput.
- Digital disruptors and exoscope developers that prioritize remote visualization, deep integration with surgical navigation, and minimally invasive workflows. These players often pursue partnerships with software and AI companies to extend capability rapidly.
Recent corporate actions underscore these dynamics. Manufacturers have secured regulatory approvals and expanded product families with heads‑up 3D modules, 4K digital microscopes and AR‑enabled devices, accelerating conversion of traditional optical buy cycles into digital upgrade cycles. For acquirers and OEMs preparing 2026 launches, the lesson is clear: new products must justify premium pricing through measurable improvements in OR throughput, ergonomics and intraoperative insight.
What PW Consulting’s full report delivers (practical, executable outputs)
Our full report is built for strategy teams, corporate development and product leaders who must act in 2026. It includes:
- A closed‑form market model and base case/alternative scenarios calibrated to clinical adoption rates, hospital procurement cycles and module attach‑rates — enabling rapid stress‑testing of revenue outcomes under differing rollout speeds.
- A vendor matrix that maps product portfolios against capability vectors (optical quality, digital visualization, fluorescence, OR integration, service models), plus qualitative scoring to identify attack and defense priorities.
- Commercial playbooks for market entry and expansion, including channel strategies, tender vs. direct mixes, and value‑based selling approaches tailored to neurosurgery, ophthalmology and ENT buyers.
- Regulatory and reimbursement trackers with timeline scenarios and impact assessments for fluorescence adjuncts and diagnostic reclassifications.
- Transaction and partnership pipeline guidance that prioritizes targets based on capability gaps, cultural fit and expected synergies by the year‑end 2026 value creation horizon.
- An ROI stress tester to model upgrade vs. replace decisions in hospital fleets, incorporating capital depreciation, service contracts and software monetization assumptions.
Strategic recommendations for 2026 (actionable and prioritized)
- Prioritize modular digital architectures: Roadmaps should enable field upgrades from optical to hybrid/digital modes to protect installed bases and accelerate attach‑rate for software services.
- Build fluorescence and task‑specific imaging capability early: Regulatory windows and adoption by specialty societies create first‑mover advantage in tumour and retinal applications.
- Design selling motions around clinical and operational outcomes: Procurement teams react to measured throughput and training benefits more than to technical specifications alone.
- Use M&A selectively to acquire interoperability and analytics capabilities rather than optics alone: software and visualization platforms are the primary drivers of sustained margin expansion.
- Invest in education and OR integration services: Demonstrable improvements in ergonomics and team performance accelerate hospital‑level adoption of premium systems.
How PW Consulting’s intelligence supports boardroom decisions
Boards and executive teams face tradeoffs between organic R&D, bolt‑on acquisitions, and commercial partnerships. PW Consulting’s integrated model and strategic playbooks compress the time to insight by connecting clinical trends, regulatory pathways and procurement economics. The result is an evidence‑based roadmap that translates technical differentiation into 24‑ to 36‑month commercial KPIs.
Next steps — where to get the full intelligence
This preview surfaces the critical strategic signals you will need for 2026 planning. The full Secondary Medical Diagnosis And Treatment Microscope Market report contains the complete market model, scenario outputs, executable go‑to‑market plans and detailed vendor assessments. To access the full report, company‑level briefings, or a customized strategy workshop, please visit PW Consulting’s research portal or contact our advisory team directly. Note: to preserve competitive integrity, the full report contains the granular segmentation and vendor share tables omitted here.
PW Consulting remains committed to equipping healthcare technology leaders with actionable, defensible strategies that align clinical impact with commercial performance. In a market where optical craft meets digital acceleration, the right play in 2026 will determine who leads the next wave of OR transformation.
For detailed analysis of this topic, please visit the official page: Secondary Medical Diagnosis And Treatment Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


