



PW Consulting: Clinical Disorder Treatment Market to Expand at a 6.18% CAGR During 2026–2032, New Report Finds

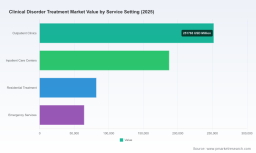
Clinical Disorder Treatment Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, decision-focused preview of our newly published Clinical Disorder Treatment Market report. This briefing is designed to demonstrate the strategic value of the full report for executives, investors, payers and product teams planning actions in 2026, while reserving the proprietary granular tables and segment-level line items for the complete publication.
Clinical Disorder Treatment Market
Market trajectory at a glance
The global clinical disorder treatment market is on a structurally positive trajectory. Using 2025 as our base year, PW Consulting’s top-line model projects the market expanding from an estimated USD 585,500 Million in 2025 to approximately USD 892,100 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.18% across the 2026–2032 forecast window. The 2026 near-term inflection is notable: our model anticipates acceleration relative to the early-2020s recovery curve as regulatory shifts, reimbursement dynamics, and care-delivery innovations combine to enlarge addressable patient flows and therapeutic adoption.
Clinical Disorder Treatment Market
While this preview highlights macro directionality and strategic ramifications, the complete report contains full historical series (2020–2025), monthly and annualized revenue scenarios, and proprietary sensitivity runs. To preserve the report’s role as the single source of detailed segmentation intelligence, we are intentionally omitting the granular regional and sub-segment tables here.
Clinical Disorder Treatment Market
Why the 2026 planning cycle should prioritize this market
- Durable demand fundamentals — Rising prevalence of mental health conditions and expanding insurance coverage are lifting baseline demand across settings and disorder types.
- Regulatory re‑rating — Accelerated FDA pathways and priority mechanisms for novel modalities (notably psychedelic-assisted and other experimental agents) are compressing time-to-market for a new class of therapeutics, creating first-mover advantages for sponsors who can execute robust clinical and commercial plans.
- Commercial churn — Imminent patent expirations and ongoing generic pressure will reshape product portfolios and pricing power, increasing the value of differentiation through delivery models, adjunctive indications and label expansions.
- Service model transformation — Telehealth, hybrid care and expanded outpatient capacity are shifting revenue between inpatient and community-based settings, requiring providers and payers to rethink contracts and capacity investments.
Competitive landscape — implications for 2026 positioning
The sector is characterized by a mix of large multinational originators, specialty psychiatric providers, and major generics players. Market concentration remains relatively low: the top-three players account for under a fifth of market revenue (CR3 ~18.45%) and the top-five account for roughly one-quarter (CR5 ~25.12%). That structure creates both opportunity and risk — scale matters for R&D and supply resilience, but nimble entrants can capture meaningful niche value.
Key strategic profiles and near-term implications:
- Johnson & Johnson (Janssen): With Spravato (esketamine) and an extended neuroscience franchise, J&J continues to be a bellwether for how complex, clinic-administered therapies scale commercially. Their acquisition-driven expansion into novel CNS assets suggests an aggressive play for label breadth and treatment sequence positioning — important for competitors to anticipate when modeling adoption curves.
- Eli Lilly and Company: As a long-standing innovator in antidepressant development, Lilly’s pipeline and commercialization muscle make it a natural contender in both new-molecule launches and label-extension strategies; agile payer engagement will be essential to defend premium pricing.
- Pfizer and GlaxoSmithKline (GSK): These incumbents supply broad portfolios that serve as backbone therapies; their global reach and partnership capacity allow rapid lifecycle management and geographic prioritization following regulatory events.
- AstraZeneca and Otsuka: Heavyweights in antipsychotics and bipolar treatments, they will be closely affected by patent cliffs and need to accelerate diversification into adjunctive and novel modalities.
- Specialty behavioral health operators (e.g., Acadia Healthcare, Universal Health Services): Providers are reconfiguring care networks to capture demand shifts to outpatient and residential models — their contract negotiations, capacity investments and payer partnerships will materially influence local pricing and access dynamics.
- Teva and other generics manufacturers: Intensifying generic competition following key patent expirations will compress branded margins while expanding volume-driven access; originators should prepare for rapid erosion in unit price across vulnerable molecules.
Regulatory and policy catalysts shaping 2026
2026 is already proving to be a watershed year for regulatory dynamics in psychiatric therapeutics. The US FDA’s recent acceleration mechanisms — including national priority designations for psychedelic-based therapies and allowances for early-phase work on previously constrained compounds — materially change the risk/reward calculus for sponsors. These shifts dovetail with a broader policy environment: a presidential focus on serious mental illness, heightened attention to domestic manufacturing of APIs and finished products, and evolving reimbursement pathways for clinic-administered and digital hybrid therapies.
Concurrently, patent expirations on several high-revenue molecules later in 2026 will unlock generics competition and necessitate strategic responses such as lifecycle extensions, combination product strategies, and differentiated service offerings linked to proprietary delivery platforms.
Operational and supply-chain considerations
- API and finished-dose manufacturing risk: Current analyses show significant reliance on non-domestic production for both patented APIs and finished products; executives should run stress tests and secure dual-sourcing strategies as part of 2026 contingency planning.
- Capacity rebalancing across care settings: As outpatient and hybrid models scale, capital allocation should prioritize ambulatory infrastructure and digital integration to capture shifting revenue pools.
- Payer contracting and value demonstration: With new modalities and psychedelic-assisted programs entering regulatory pathways, rigorous real-world evidence (RWE) plans and economics-of-care models will be decisive in securing favorable coverage.
What PW Consulting’s report delivers — practical, executable intelligence
Our full Clinical Disorder Treatment Market report is structured to support immediate 90/180/360-day decision cycles and longer-term strategic investments. Core deliverables include:
- Top‑line and scenario-based forecasts (2026–2032) with sensitivity to adoption curves, pricing erosion and reimbursement shifts.
- Regulatory pathway maps and approval-timing impact assessments, including implications of accelerated programs for psychedelic and novel agents.
- Patent-expiry impact models and generics-entry timing, calibrated to company portfolios and therapeutic classes.
- Care-delivery market maps that tie patient flows to provider economics across inpatient, outpatient, residential and emergency settings.
- Commercial playbooks: launch sequencing, payer evidence dossiers, and salesforce deployment optimization for clinic-administered therapies.
- M&A and portfolio optimization frameworks: valuation sensitivities, integration risk matrices and divestiture candidates.
- Supply chain resilience frameworks: API sourcing heatmaps, dual-sourcing strategies and manufacturing investment prioritization.
Each section pairs quantitative models with executable checklists and templated board-ready slides so teams can move from insight to investment or operational decision in weeks, not months.
Practical strategic actions for 2026
- For R&D and portfolio teams: Prioritize accelerated programs with clear payer-endpoints; build RWE protocols early to shorten commercialization timelines under priority regulatory mechanisms.
- For commercial and market-access leaders: Prepare for rapid formulary negotiations tied to new specialty-administered products; invest in outcomes-based contracting pilots where data collection infrastructure exists.
- For providers and health systems: Rebalance bed and outpatient capacity with an emphasis on multidisciplinary, hybrid-care models that can capture higher outpatient throughput and lower cost per episode.
- For finance and corporate development: Model downside scenarios tied to patent expirations and upsides from psychedelic-class approvals; maintain optionality via staged M&A contingent on regulatory milestones.
- For operations: Initiate API sourcing stress-tests and short-list alternative contract manufacturers to mitigate concentrated supplier risk.
Final note — why PW Consulting’s analysis matters for 2026
Decisions made in 2026 will determine which organizations capture the majority of value created over the next decade. Our macro forecast (CAGR 6.18% through 2032 with a materially larger market by the end of the forecast period) indicates both growth potential and disruption risk. The combination of regulatory acceleration, patent-driven commoditization, evolving care models and supply-chain exposures means leaders must translate insight into concrete operational moves this year.
To maintain our role as a strategic enabler, PW Consulting intentionally positions this preview as a directional briefing. The full report contains the segment-level revenue tables, regional splits, disorder-type and service-setting forecasts, and the proprietary scenario matrices necessary for valuation, commercial planning and operational redesign. Access to those granular datasets and bespoke advisory engagement options is available through PW Consulting’s market research portal.
For executive teams preparing 2026 budgets, M&A roadmaps or regulatory strategies, our report is built to accelerate decision cycles and reduce execution risk. Contact PW Consulting to obtain the full report and schedule a tailored executive briefing that translates these insights into a 90‑day action plan for your organization.
For detailed analysis of this topic, please visit the official page: Clinical Disorder Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


