



PW Consulting: Government & Military SATCOM Market Hits USD 10.9 Billion in 2025, Poised for 7% CAGR Through 2032

Government And Military Satellite Communications Market: Strategic Imperatives for 2026 Decision‑Makers
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Government And Military Satellite Communications Market
Executive summary
The Government and Military Satellite Communications (Gov/Mil SATCOM) market is transitioning from platform-centric procurement to outcome-driven, multi-orbit communications architectures. PW Consulting’s new market report — calibrated to a 2025 base year and projecting through 2032 — quantifies this transition and translates it into practical decision frameworks for defense and government program managers, prime contractors, and commercial SATCOM providers planning 2026 investments.
Government And Military Satellite Communications Market
Key macro facts that shape the 2026 decision window: the addressable Gov/Mil SATCOM market exhibited steady expansion in the early 2020s, achieving a clear inflection by the 2025 base year, and our modelling points to a sustained compound annual growth rate (CAGR) of approximately 7.0% across the 2026–2032 forecast horizon. That trajectory underpins an industry that is simultaneously growing in absolute scale and evolving structurally as multi‑orbit, resilient, and allied‑centric capabilities gain procurement priority.
Government And Military Satellite Communications Market
Why this matters for 2026 strategy
-
Budget timing & program alignment: Growing market scale means more commercial capacity and a larger pool of suppliers competing for government contracts — but procurement windows are tightening. Governments are accelerating programs that favor proliferated and protected SATCOM, changing the cadence of awards and sustainment decisions.
-
Technology risk vs procurement agility: Investments in protected payloads, resilient terminals, and cross‑linking demand careful tradeoffs between immediate capability and long‑lived platform commitments. The right strategic posture in 2026 preserves operational options without over‑committing to a single orbit or vendor.
-
Allied interoperability & export controls: Recent export‑control reforms and allied licensing adjustments materially affect partnership strategies. Firms and government buyers must balance sovereign assurance with the operational benefits of allied supply chains and international commercial capacity.
Market trajectory and what the numbers imply
Our time‑series synthesis shows sustained growth from the historical window into the forecast period. This is not a commodity market expansion: growth is being driven by demand for resilience, anti‑jamming capability, low latency tactical links, and managed services that blur the line between commercial and defense SATCOM offerings. The CAGR of roughly 7% over 2026–2032 reflects the combined effect of modernization programs, commercial LEO service adoption for tactical use, and increasing sustainment spend on protected terminals and ground systems.
For decision‑makers, the implication is twofold: first, procurement strategies framed for 2026 must be modular and optioned to accept alternative capacity paths (GEO, MEO, LEO), and second, suppliers must present interoperable, coalition‑ready solutions rather than single‑vendor stacks to remain competitive.
Strategic themes that define winners and losers
-
Resilience as the organizing principle — Multi‑layered architectures that combine protected GEO payloads with proliferated LEO/MEO constellations are becoming the baseline requirement for high‑value missions. Programs emphasizing mobility, anti‑jamming, and assured communications will capture disproportionate budget attention.
-
Services over hardware — A shift toward managed SATCOM services and networked mission support is reshaping procurement economics. Buyers increasingly favor predictable, service‑level driven contracting that bundles capacity, ground systems, and sustainment.
-
New entrants and incumbents co‑exist — LEO native players and small GEO specialists accelerate innovation cycles, while legacy primes convert systems engineering depth into integrated architectures for national programs. Strategic collaboration models (alliances, JV, subcontracting) will determine access to major contracts.
-
Policy levers matter — Export control adjustments and dedicated government initiatives that underwrite commercial participation (e.g., proliferated GEO programs) materially change opportunity sizing for suppliers; staying ahead of these policy inflections is a source of competitive advantage.
What the report contains — actionable intelligence for 2026
This report was written to be a tactical tool for executives and program managers. Readers will find:
-
Proprietary market sizing and multi‑scenario forecasts (base year 2025, forecast 2026–2032) with sensitivity analyses calibrated to policy and technology inflection points.
-
Decision frameworks for procurement: modular contracting templates, commercial‑services integration blueprints, and a vendor short‑listing methodology that converts strategic priorities into RFP evaluation criteria.
-
Capability roadmaps: comparative assessments of GEO, MEO, and LEO access strategies, protected payload options, and terminal modernization pathways indexed against mission types.
-
Supplier playbooks: vendor risk and opportunity matrices, alliance candidate lists, and negotiation levers informed by procurement practices in the U.S. and allied nations.
-
Operational impact studies and war‑gaming scenarios: performance tradeoffs under contested environments, sustainment and logistics modelling, and rapid‑fielding templates for tactical units.
-
Regulatory and policy tracker: a concise digest of export control shifts, procurement office behaviors, and program funding signals that quantifies impact on supplier market access.
Competitive landscape — what the major players are doing
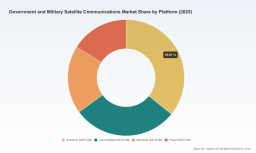
The Gov/Mil SATCOM ecosystem in 2026 is a mosaic of large defense primes, satellite operators, terminal specialists, and disruptive LEO entrants. Market concentration is meaningful but not monopolistic: the top three firms together account for a notable portion of spend, and the top five extend that influence further — a pattern that favors integrated proposals for national scale programs while leaving room for specialized suppliers to excel in terminals, managed services, and tactical payloads.
-
Defense primes (Lockheed Martin, Northrop Grumman, Boeing): These firms convert systems integration depth into program wins for programmatic efforts that demand secure, resilient architectures. Their strengths lie in heritage MILSATCOM payloads, complex ground systems, and program management for high‑assurance missions.
-
Network and systems integrators (L3Harris, RTX): Focused on terminal modernization and sustainment, these companies are critical in translating protected payload capabilities into fielded tactical connectivity, with large sustainment programs providing steady revenue backbones.
-
Commercial operators (SES, Intelsat, Iridium): Offering multi‑orbit and managed capacity, these operators are increasingly competing for government business through hybrid commercial‑defense contracts and service agreements that emphasize flexibility and rapid capacity provisioning.
-
New orbit and platform entrants (SpaceX, Astranis, AST SpaceMobile): LEO constellations and small GEO specialists are forcing incumbents to reconsider architectural assumptions. Their offers — low latency, global reach, and rapid refresh cycles — are compelling for tactical and beyond‑line‑of‑sight use cases.
-
Terminal and antenna specialists (Cobham, Gilat, Viasat): Ruggedized, multi‑band terminals and field‑deployable antenna systems are the interface layer that ultimately determines mission effectiveness. Competitive differentiation is increasingly about software, waveform agility, and supply chain robustness.
Recent contract signals and policy moves to watch in 2026
-
Large program awards and IDIQ ceilings for protected tactical SATCOM concepts are reshaping supplier pipelines and investment priorities. Program design contracts for anti‑jam GEO solutions have drawn both primes and emergent small‑sat vendors into collaborative bid strategies.
-
Government procurement behavior shows a pronounced tilt toward commercial purchasing channels for SATCOM capacity, which intensifies competition among commercial operators to meet defense SLAs and security requirements.
-
Targeted export‑control reforms and allied licensing realignments reduce friction for coalition supply chains, increasing the attractiveness of multinational industrial architectures — but also introduce new compliance and IP governance questions that require early legal and programmatic alignment.
Guidance — what to do next (for buyers and suppliers)
-
Buyers: adopt modular contracting with option windows for alternative orbit capacity; require coalition and cross‑vendor interoperability in RFPs; insist on measurable resilience KPIs, not just bandwidth metrics.
-
Primes & operators: structure proposals as outcome packages (capacity + terminal + sustainment + cyber hardening) to meet evolving procurement preferences; accelerate partnerships with LEO providers and terminal specialists.
-
SMEs and terminal vendors: prioritize waveform agility, anti‑spoofing features, and ruggedization while validating sustainment and logistic readiness to compete for prime-led procurements.
-
Investors: look for companies that can deliver integrated service propositions, demonstrate government procurement wins, and show roadmap alignment with protected payload programs and multi‑orbit service offerings.
Access the full intelligence
This article highlights the strategic takeaways from PW Consulting’s Government And Military Satellite Communications Market report. The full report — incorporating granular segment modelling, company scorecards, procurement templates, and downloadable scenario models — provides the operational data and decision‑support tools necessary to execute on 2026 strategies.
To retain competitive advantage in a market that is both expanding and reconfiguring its core economics, program managers and commercial leaders must pair technical choices with procurement design and alliance strategy. The full PW Consulting report supplies that integrated playbook — enabling confident 2026 decisions while preserving flexibility for the unpredictable operational environment ahead.
For detailed analysis of this topic, please visit the official page: Government And Military Satellite Communications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


