



PW Consulting: Rare Endocrine Disease Treatment Market Forecast to Grow from USD 16,450 Million in 2025 to USD 29,592 Million by 2032 (8.75% CAGR) — North America Leads (USD 7,651.9M), Somatostatin Analogs Top Therapy; Top 3 Firms Hold 42.15%

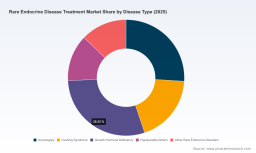
Rare Endocrine Disease Treatment Market 2026: Strategic Imperatives from PW Consulting
Executive preview
PW Consulting’s latest market research — Rare Endocrine Disease Treatment Market — equips biopharma executives, investors, and health-system strategists with the evidence and decision frameworks required to set winning priorities in 2026. Built on a transparent modeling framework spanning 2020–2025 (historical) and a detailed forecast from 2026–2032, the study shows a resilient, innovation-driven market that grew from approximately USD 10,850.5 Million in 2020 to USD 16,450 Million in 2025, and is projected to reach roughly USD 29,591.76 Million by 2032 at a compound annual growth rate (CAGR) of 8.75% through the forecast window.
Rare Endocrine Disease Treatment Market
Why this report matters for 2026 corporate decision-making
-
Momentum and timing: The market’s high-single-digit CAGR reflects a unique intersection of regulatory incentives, meaningful clinical breakthroughs, and growing payer willingness to fund high-value rare-disease therapies. 2026 will be a pivotal year for translating clinical wins into durable commercial advantage.
Rare Endocrine Disease Treatment Market -
Prioritization under constraint: R&D budgets and M&A war chests are finite. Our deliverables translate macro growth into specific go/no‑go thresholds and launch sequencing recommendations that preserve optionality while accelerating high-impact programs.
Rare Endocrine Disease Treatment Market -
Risk management: With several first-in-class and label-expansion approvals materializing in 2024–2026, strategic choices around manufacturing scale-up, payer contracting, and evidence generation will determine who captures the fastest-growing share of the expanding headline market.
What the PW Consulting report delivers (operationally focused)
-
Actionable market sizing & forecasting — a transparent global model with downloadable worksheets (USD, revenue unit: Million), historical reconciliation (2020–2025), and scenario alternatives (base, upside, downside) for 2026–2032.
-
Segmentation roadmaps — disease, therapy modality, and regional opportunity maps that prioritize subsegments by commercial attractiveness, but intentionally withhold granular public splits to protect proprietary insight and drive full report engagement.
-
Launch playbooks — step‑by‑step execution plans (pricing, contracting, field force sizing, KOL engagement, and digital patient support) for first-in-class agents and late-stage label expansions.
-
Commercial and payer modelling — HTA and reimbursement pathways, value-dossier templates, and outcome-based contracting frameworks tailored for orphan‑disease dynamics.
-
Portfolio optimization and M&A screen — scoring engine that integrates scientific differentiation, addressable population, regulatory risk, manufacturing readiness, and likely reimbursement to rank assets for buy/sell/license decisions.
-
Clinical and RWE playbook — pragmatic designs for confirmatory studies, surrogate endpoints acceptable to regulators and payers, and RWE generation plans that maximize post-launch value capture.
-
Supply chain & manufacturing readiness assessment — capacity, cold-chain, and tech-transfer checklists that reduce launch latency and allocation risk.
Methodology highlights (so you can interrogate the model)
-
Base and historical years: The model uses 2025 as the base year and incorporates historical market activity from 2020–2025 to validate growth drivers.
-
Forecast horizon: 2026–2032 with an explicit CAGR of 8.75% in the base-case projection; scenario analysis varies underlying epidemiology, uptake curves, and pricing assumptions.
-
Currency and units: All financials are presented in USD (revenue unit: Million) and include transparent assumptions for price erosion, patient access timelines, and market exclusivity impacts.
-
Sensitivity testing: User-accessible drivers include time-to-peak uptake, label breadth, reimbursement coverage rate, and competitor entry timing.
Competitive landscape: who’s shaping the market and what to watch
The market is neither a pure commodity nor a closed oligopoly: the top three firms account for a meaningful, but not dominant, share (CR3 ≈ 42.15%), and the top five account for a majority positioning (CR5 ≈ 58.6%). That structure favors both disciplined incumbents and focused new entrants with differentiated assets.
-
Ascendis Pharma (Copenhagen) — a leader in pro‑drug and sustained‑release TransCon technologies with late-stage programs across growth hormone and hypoparathyroidism. Their platform approach reduces dosing burden, a competitive axis that materially affects adherence and payer value conversations.
-
Novo Nordisk (Bagsværd) — leveraging strong commercial reach to expand once-weekly growth hormone indications. Recent regulatory momentum around pediatric label expansions underscores how rapid label breadth can convert platform reach into market share.
-
Recordati Rare Diseases (Milan) — a focused portfolio player in pituitary and adrenal dysfunctions; its specialized channel experience makes it an attractive partner or acquirer for orphan programs needing dedicated field expertise.
-
Neurocrine Biosciences (San Diego) — with the approval of the first non‑steroidal adjunct therapy for classic congenital adrenal hyperplasia, the company demonstrates how mechanism novelty can unlock new clinical practice patterns and payer conversations.
-
Ipsen, Pfizer, and AstraZeneca (Alexion) — these established players bring deep specialty-commercial capabilities and global reimbursement relationships that matter most in launch execution and contracting.
-
Spruce Biosciences and MBX Biosciences — smaller, nimble firms that represent the upstream innovation pool; their success will often hinge on partnering or well‑timed exits.
Recent industry inflections and regulatory tailwinds
-
Novel approvals and label expansions are remapping addressable populations. Notable regulatory events in 2024–2026 have validated new mechanisms and dosing paradigms (e.g., oral somatostatin receptor ligands and expanded weekly growth-hormone indications), accelerating payer discussions about long-term cost-effectiveness.
-
Orphan drug incentives, Fast Track and priority designations continue to lower development risk and extend exclusivity advantages, shaping transaction timing and competitive entry calculus.
-
Approval of breakthrough modalities that reduce treatment burden (oral vs. injectable, less frequent dosing) creates two-tier markets within the same therapeutic class: high-value premium segments and legacy lower-price segments. Capturing premium positioning requires coordinated clinical, commercial, and HEOR strategies.
Priority strategic plays for 2026
-
Optimize launch sequencing: Use a dynamic threshold approach to prioritize indications and geographies where price realization and access are highest in year 1–3 post-launch.
-
Evidence-first contracting: Build integrated pre-launch HEOR packages with commitment to post‑launch RWE that underpin outcomes-based contracts favored by specialty payers.
-
Partnerships over binary bets: Smaller innovators should pursue staged licensing deals that align milestone payments with regulatory and payer de‑risking events to maximize valuation while preserving upside.
-
Manufacturing and distribution hedges: Early investment in secondary manufacturing capacity and cold-chain resilience reduces launch disruption risk for differentiated biologics and extended-release formats.
-
Defend with label and service: Incumbents should combine label expansion, patient-support services, and digital adherence tools to blunt disruptive entrants offering improved convenience.
-
M&A screening cadence: Target assets should demonstrate either immediate revenue synergy potential or clear pathway to payer-acceptable outcomes within a 24–36 month window post-acquisition.
How PW Consulting helps you act in 2026
Clients commissioning our full report receive the complete model, competitor dashboards, bespoke scenario workshops, and an executive decision pack that converts market insight into board-ready recommendations. Practical outputs include launch scorecards, M&A candidate prioritization matrices, payer engagement scripts, and a customizable financial workbook to stress-test internal planning at multiple price and uptake points.
Closing (the trailer)
The Rare Endocrine Disease Treatment Market is entering a phase where clinical innovation, regulatory incentives, and payer sophistication converge to create outsized opportunities for companies able to align evidence generation with commercial execution. PW Consulting’s report distills the complexity into the strategic choices that will define market leadership in 2026 and beyond.
To access the full dataset, interactive models, and the detailed segmentation maps that inform our recommendations, please visit our report landing page — the granular figures and regional/disease-level splits are available exclusively with the full report.
For detailed analysis of this topic, please visit the official page: Rare Endocrine Disease Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


