



PW Consulting: Medical Desktop Ultrasonic Equipment Market Poised to Reach USD 10.39 Billion by 2032, Expanding at a 6.0% CAGR

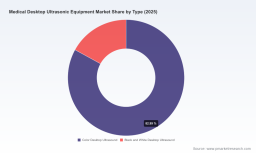
Medical Desktop Ultrasonic Equipment Market: Strategic Implications for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s new market study on Medical Desktop Ultrasonic Equipment frames 2026 as a pivotal year for capital deployment, portfolio rebalancing, and go-to-market repositioning. Built on a 2020–2025 historical base with 2025 as the reference year, the study quantifies the desktop ultrasonic market at approximately USD 6,911.9 Million in 2025 and traces growth from USD 5,120.45 Million in 2020. Our forecast horizon (2026–2032) points to steady expansion at a 6.0% CAGR, with the market projected to approach USD 10,392.94 Million by 2032. Those macro trajectories underscore durable demand driven by hospital departmental upgrades, point-of-care diffusion, and a multi-year replacement cycle among imaging capital stock.
Medical Desktop Ultrasonic Equipment Market
Why 2026 matters to executives
-
CapEx windows are opening. Fiscal and tax policy shifts in 2025—most notably the expansion of Section 179 deduction limits under the One Big Beautiful Bill Act (OBBBA)—create a near-term incentive to accelerate purchases of qualifying medical equipment, including desktop ultrasound systems. For CFOs and heads of procurement, this changes the calculus on timing versus financing of upgrades and fleet renewals.
Medical Desktop Ultrasonic Equipment Market -
Aftermarket and service are strategic value pools. Labor market projections and the evolving repair ecosystem (employment for medical equipment repairers is forecast to grow significantly through 2034) make service contracts, spare-parts logistics, and remote diagnostic capabilities critical levers for margin protection and customer retention.
Medical Desktop Ultrasonic Equipment Market -
Reimbursement and cost-allocation dynamics remain a constraint and an opportunity. Macro-level evidence from workers' compensation and health-plan analyses shows that durable medical equipment occupies a modest but meaningful share of medical spend—making cost-of-ownership narratives (throughput improvements, downtime reduction, and reimbursement optimization) persuasive with hospital CFOs.
-
Technology and product roadmaps are accelerating. AI-enabled image enhancement, compact beamformer architectures, and PC-based scanning platforms are reshaping product tiering between desktop and handheld systems. This creates strategic choices for OEMs: compete on features, integrate vertically into software platforms, or specialize in niche clinical workflows.
What the PW Consulting report delivers (practical, decision-ready content)
-
Proprietary market sizing and forecast: A transparent model covering 2020–2032 with scenario runs calibrated to demand, procurement cycles, and regulatory shocks (base year 2025; forecast CAGR 6.0% for 2026–2032).
-
Demand-driver heat maps and buyer personas: Hospital departments, outpatient clinics, ambulatory surgical centers, and veterinary clinics profiled by purchase drivers, procurement timelines, and service expectations.
-
Supply-side diagnostic: Component dependencies, critical supplier concentration, and lead-time sensitivities for transducers, beamformers, and display subsystems—with mitigation playbooks for sourcing risk and dual-sourcing scenarios.
-
Go-to-market playbooks and commercial pilots: Channel strategies for direct sales, distributors, and OEM partnerships; pricing frameworks; and trial-to-adoption conversion templates tailored to desktop-form factor use-cases.
-
Aftermarket and service economics: Modular contract templates, tiered service offerings, spare-parts inventory models, and revenue-smoothing approaches for subscription & SaaS-enabled imaging features.
-
M&A and portfolio prioritization toolkit: Deal-screening scorecards, payback models, and integration checklists aimed at identifying bolt-on opportunities and defensive investments given observable market concentration metrics.
-
Regulatory readiness checklist and reimbursement mapping: Practical steps to prepare for 510(k) pathways, clinical validation plans, and payer engagement blueprints—critical for companies planning U.S. market entry or platform upgrades.
Competitive landscape — concentrated yet dynamic
Market concentration is material: the top three firms account for nearly half of current revenue share (CR3 ~48.5%), and the top five exceed roughly two-thirds of the market (CR5 ~64.2%). That structure produces a bimodal competitive environment where scale incumbents defend broad clinical footprints while focused specialists and new entrants pursue niche workflows and cost-efficient desktop alternatives.
-
GE Healthcare (Chicago, Illinois, USA) — A broad clinical portfolio and deep channel relationships make GE a natural anchor for hospital-grade desktop upgrades and enterprise imaging suites. Expect continued emphasis on integration with enterprise imaging and service-led solutions (www.gehealthcare.com).
-
Philips Healthcare (Amsterdam, Netherlands) — Philips balances premium desktop offerings with workflow-centric features and enterprise software integrations. Its strength lies in cross-modality purchasing influence and lifecycle service contracts (www.philips.com/healthcare).
-
Mindray Medical International (Shenzhen, China) — Cost-competitive desktop and tabletop systems, combined with aggressive global distribution, position Mindray to capture share in emerging and mid-market hospital segments (www.mindray.com).
-
Esaote (Genoa, Italy) — Specialist desktop and tabletop platforms focused on musculoskeletal and cardiovascular niches; differentiation through clinical specificity and tailored probes (www.esaote.com).
-
Telemed (Vilnius, Lithuania) — PC-based beamforming and OEM-friendly platforms offer flexibility for partners seeking desktop ultrasound integrations and low-cost customization (www.pcultrasound.com).
-
MEDA Co., Ltd. (Tianjin, China) — Focused on platform-style devices for ophthalmic and general diagnostic use; potential consolidation target for product-line expansion (www.meda.com.cn).
-
Keeler (part of Halma plc; Broomall, Pennsylvania, USA / Windsor, UK) — Ophthalmic desktop systems with high clinical trust; attractive for specialty practice penetration (www.keelerusa.com).
-
Contec Medical Systems (Qinhuangdao, China) — Volume-oriented desktop B-ultrasound offerings targeted at price-sensitive buyers and emerging markets (www.contecmed.com).
-
BMV Medtech Group (Shenzhen, China) — Compact desktop solutions with a focus on automatic modes and color Doppler functionality for mixed human and veterinary markets (www.bmvmed.com).
-
Edan Instruments (Shenzhen, China) — Recent regulatory momentum: Edan secured U.S. FDA 510(k) clearance in December 2025 for its Nano series (Nano C5/C5 EXP and Nano L12/L12 EXP), expanding its addressable desktop-compatible opportunity set (U.S. FDA K251268; www.edan.com).
Recent regulatory and technology signals to watch
-
FDA clearance activity continues to open U.S. adoption pathways for portable and desktop-capable platforms. Notable 2025 clearances (for example, Edan and other portable systems) shorten time-to-market for devices designed to play in desktop workflows.
-
New device approvals combining imaging with AI-assisted guidance (e.g., AI-driven navigation for spinal procedures) are beginning to tilt buyer preferences toward integrated software-and-hardware bundles; Accuro’s regulatory clearance in 2025 for SpineNav-AI–enabled devices exemplifies this trend.
-
Component and manufacturing risk management is a live boardroom issue; our supply-side chapters model lead-time shocks and provide mitigation scorecards.
-
Macro imaging market context remains supportive: broader ultrasound imaging markets continue expanding on technological upgrades and broader clinical uses (historical external market analyses project a multi-year rise from a baseline in 2021 toward materially higher valuations by 2030), which validates long-term desktop demand in our scenarios.
A 2026 playbook — practical recommendations for decision-makers
-
Prioritize high-conviction CapEx that leverages tax benefits. Use accelerated Section 179 allowances where eligible to shorten payback periods on fleet refreshes.
-
Tie R&D to modularity. Develop common beamformer and software stacks to enable both desktop and portable SKUs without duplicative development cost.
-
Monetize service. Create tiered service bundles and remote-diagnostics subscriptions to capture recurring revenue and increase lifetime customer value.
-
Screen M&A targets with concentration in mind. Tactical acquisitions should either increase scale in underpenetrated clinical segments or add differentiated clinical functionality not easily replicated by incumbents.
-
Negotiate channel exclusivity and demo fleets. For market entry teams, securing in-hospital pilot sites with clear KPIs accelerates diffusion and supports reimbursement conversations.
-
Operationalize regulatory readiness. Prepare 510(k) strategies in parallel with clinical studies and establish payer engagement teams to map reimbursement trajectories early.
How to use the full PW Consulting report
This market brief highlights the strategic contours you need to plan for 2026, but our full report contains the granular segmentation, proprietary forecasting tables, buyer-level pricing elasticities, and downloadable financial models necessary to execute. PW Consulting clients will find plug-and-play ROI calculators, M&A scorecards, and a supplier-risk dashboard to support immediate board-level decisions. To access the complete intelligence package, including the full breakdown by product form, application clusters, and regional go-to-market matrices, please consult the PW Consulting report webpage and client portal.
Closing note
In a market forecast to expand from a mid-single digit billion-dollar base toward double-digit-billion territory over the next decade, desktop ultrasound represents both a defensive core for incumbent portfolios and an entry point for nimble challengers. The 2026 decision window—shaped by tax incentives, regulatory clearances, and accelerating service economics—requires integrated strategy across product, commercialization, and aftermarket functions. PW Consulting’s report equips leaders with the analytics and playbooks to translate that strategic intent into executable plans.
For detailed analysis of this topic, please visit the official page: Medical Desktop Ultrasonic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


