



PW Consulting: Soldier Combat System Market Poised for 6.45% CAGR in 2026–2032 Forecast

Soldier Combat System Market 2026: Strategic Imperatives from PW Consulting’s New Market Study
Executive summary
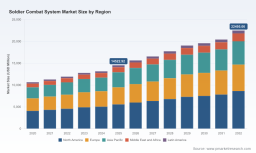
PW Consulting today releases a strategic briefing based on our full Soldier Combat System Market research report (base year 2025, forecast 2026–2032). The market has moved from a post‑pandemic recovery phase into a sustained modernization cycle—driven by digitization of small units, proliferation of multispectral sensors, and renewed procurement programs across advanced militaries. Our analysis shows the market expanding at a compound annual growth rate (CAGR) of 6.45% through 2032, reflecting accelerating investment in networked C4I, soldier lethality and protection, and power/data management solutions.
Soldier Combat System Market
Market trajectory: the macro picture
Between 2020 and 2025 the Soldier Combat System market demonstrated steady expansion as programs evolved from prototype to initial fielding. Our topline data shows the global market grew from roughly USD 10.7 billion in 2020 to about USD 14.5 billion in 2025. Under our base forecast, that trajectory continues—reaching an estimated market size in the mid‑tens of billions by 2026 and rising toward the low‑tens of billions by 2032 as persistent modernization, capability refreshes, and new program starts aggregate.
Soldier Combat System Market
Market concentration is moderate: the three largest providers account for close to two‑fifths of market revenues, while the five largest approach just over half. This structure indicates meaningful incumbent strength but ample opportunity for well‑targeted entrants, specialists and integrators.
Soldier Combat System Market
What is driving growth — and what constrains it
- Drivers
- Operational digitization: Nations are funding full‑system digitization for small units—integrated C4I, sensor fusion, and sensor‑to‑shooter chains are now programmatic priorities.
- Sensor and multi‑modal awareness: Multispectral day/night sensors, heads‑up displays and battlefield positioning are being integrated into head‑borne and dismounted architectures.
- Protection and survivability: Advances in lightweight armour, camouflage materials and biomonitoring are converging with electronic solutions to create differentiated, layered protection packages.
- Power & data management: The need to supply and manage multiple high‑draw devices on a soldier is creating demand for centralized power hubs, smart textiles and energy‑efficient subsystems.
- Constraints and risk factors
- Integration complexity and soldier burden: More capability does not automatically translate into operational advantage—power, weight, ergonomics and human‑machine interfaces remain primary risk vectors.
- Export and regulatory controls: Systems that include munitions‑listed items, night vision, or advanced comms face export controls and licensing regimes that materially affect route‑to‑market strategies.
- Programme timing and budget uncertainty: Large framework awards skew supplier landscapes; procurement timing creates waves of demand that require precise capacity planning.
- Supply chain and materials: E‑textiles, advanced optics and bespoke electronics expose suppliers to component lead times and sourcing vulnerabilities.
Competitive landscape — reading the field
The market exhibits a mix of prime systems integrators, platform specialists and component innovators. Leading primes leverage system‑of‑systems capabilities—integrating C4I, sensors and protection—while niche players drive material and component innovation. Recent program activity underscores these dynamics.
- Systems integrators and primes — Companies with existing footprint in vehicle and force digitization have translated that expertise into soldier system programmes. Their value proposition is end‑to‑end integration: sensor suites, communications, mission management and vehicle connectivity that reduce fielding risk for procurement authorities.
- Sensor, optronics and comms specialists — Firms focusing on imaging, night vision and soldier‑worn comms provide high‑margin modules that repeatedly appear across integrator solutions. The competitive battleground is increasingly about SWaP (size, weight, and power) and multispectral performance.
- Protection and apparel innovators — Lightweight armour, multispectral camouflage and smart textiles are now integral to system effectiveness. Partners who can marry protection with sensor/data conduits gain a procurement edge.
Prominent firms exemplify these roles: prime integrators with modular, open‑architecture platforms; sensor and optronics providers delivering next‑generation situational awareness; and protection specialists offering materials innovation and production scale. High‑visibility programme awards and showcases during 2024–2026 confirm that incumbents remain influential, but teaming, consortia and OEM partnerships are the primary channels for market entry and scale-up.
Recent programme signals (selected)
- Major European digitization programmes have moved into framework contracting and initial regeneration rounds, underscoring opportunities for suppliers that can support long‑term sustainment and iterative capability upgrades.
- U.S. acquisition authorities are funding head‑borne mission command and multispectral sensor integrations through competitive rapid‑prototype vehicles—creating a near‑term ramp for qualified vendors able to meet military‑grade certification.
- Cross‑industry teaming arrangements—combining armour manufacturers with data and apparel specialists—have emerged as a dominant route to winning national procurement lots and international competitions.
What’s inside PW Consulting’s full report (practical deliverables)
- Actionable market models: topline historicals and a 2026–2032 forecast by capability area, platform and procurement cycle that enable revenue planning and scenario analysis (detailed subsegment tables and downloadable data included in the subscriber package).
- Buyer and programme mapping: a prioritized view of active and near‑term national programmes, procurement milestones and procurement modalities to enable capture planning.
- Competitive playbooks: supplier profiles, capability matrices and capability‑to‑procurement fit—designed for commercial teams to identify prime‑teaming partners and measuring sticks for RFP responses.
- Technology deep dives: assessments of power/data management, multispectral sensors, heads‑up interfaces and biomeasurement/e‑textile readiness for integration, together with TRL recommendations and test regime checklists.
- Regulatory and export advisory: practical guidance on export control exposure, ITAR implications and mitigation strategies for multinational supply chains.
- Investment and M&A signals: valuation and capability gaps that create acquisition targets, licensing opportunities and co‑development options.
Strategic implications for 2026 corporate decision‑makers
For executives and strategy teams preparing 2026 planning cycles, the report emphasizes five immediate priorities:
- Prioritize modularity and open architecture — Procurement authorities are favoring systems that enable incremental upgrades and multi‑vendor ecosystems. Companies should productize modular interfaces and compliant data/power standards to lower integration friction and increase survivability as a supplier.
- Invest in power and human‑centred integration — Marginal gains in sensor performance are insufficient if battery life and ergonomics degrade mission performance. Allocate R&D resources to power hubs, e‑textile integration, and rigorous field ergonomics testing.
- Adopt a programme capture playbook — Large framework awards create long windows of demand but require sustained engagement. Firms should combine targeted teaming agreements, regional compliance plans and a backbone of sustainment capability to win and keep programmes.
- Mitigate export/regulatory exposure — Build export control expertise into business development; factor ITAR and national licensing regimes into partner selection and contractual frameworks early.
- Pursue selective partnerships and bolt‑ons — Given the market concentration and the modular nature of programmes, sensible M&A and JV activity—focused on sensor fusion, power systems or protective materials—accelerates market access without incurring full systems integration risk.
How to use this research in 2026 planning
Procurement teams, product strategy groups and investors will use this report differently—but with a common objective: reduce uncertainty around programme timing, technical risk and go‑to‑market pathways. Examples of immediate actions we recommend:
- Run a 12‑month capture sprint for one prioritized programme with a validated teaming partner and a compliant export plan.
- Accelerate lab‑to‑field validation of power and e‑textile subsystems to secure inclusion in next‑generation integration contracts.
- Map existing product roadmaps to C4I and sensor standards to identify three product design changes that eliminate integration blockers for prime partners.
- Use the market model to stress‑test capacity and cash‑flow across scenario cases—programme wins, delayed awards, and accelerated multinational buys.
Final note — why this matters
By 2032 the soldier combat system landscape will be defined less by individual capability advances and more by how disparate technologies are stitched together under doctrine, sustainment and export constraints. The next 18 months are pivotal: programmes in procurement and prototype today will set the rhythm for supply chains and capability refreshes for a decade. PW Consulting’s report provides the modelling, programme mapping and playbooks your team needs to make decisive, risk‑calibrated moves in 2026.
Accessing the full intelligence
This release is a strategic preview. The full PW Consulting Soldier Combat System Market report contains the detailed subsegment analytics, programme calendars, supplier scorecards and downloadable datasets that senior leaders use for bid/no‑bid decisions, M&A screening and product investment roadmaps. Visit our report page to view the executive dashboard and to request the full data package and client workshop.
For detailed analysis of this topic, please visit the official page: Soldier Combat System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


