



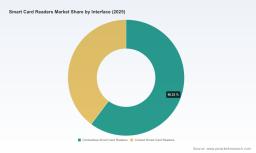
PW Consulting: Smart Card Readers Market to Reach USD 4.24 Billion by 2032 on a 10.45% CAGR, Contactless Segment Tops USD 1,273.94 Million in 2025PW Consulting: Molecular Diagnosis of Tumors Market to Rise from USD 9,450.5 Million (2025) to USD 19,932.18 Million by 2032 at 11.25% CAGR — North America, NGS and Breast Cancer Lead; Top‑5 Hold 52.8%

Smart Card Readers Market 2026: Strategic Imperatives for Procurement, Security, and Scale
PW Consulting today releases a forward-looking briefing distilled from our forthcoming Smart Card Readers Market report (base year 2025). As enterprises and public-sector leaders prepare capital and operating plans for 2026, the market’s macro trajectory, evolving standards, and supplier dynamics collectively create a narrow window of strategic decisions that will determine deployment success for the next technology cycle.
Smart Card Readers Market
Why the 2026 inflection matters
Our market model shows a robust compound annual growth rate (CAGR) of 10.45% over the forecast period, reflecting accelerating adoption of contactless and hybrid authentication technologies across identity, payment, and access-control use cases. The global market—measured in USD millions—has expanded markedly from the early 2020s baseline and continues into 2026 with a clear uptrend. That expansion is driven not only by volume replacement of legacy readers but also by incremental feature adoption (FIDO, PKI, NFC enhancements) and regulatory-driven refresh cycles in government and financial services.
Smart Card Readers Market
For decision makers, three implications are immediate: timing matters for procurement and certification, investment in interoperability reduces total cost of ownership, and supplier selection must balance innovation leadership with proven compliance and supply resilience.
Smart Card Readers Market
What the report delivers — operationally actionable intelligence
PW Consulting’s report is designed as a strategic playbook for vendors, system integrators, and enterprise buyers who must translate market signals into procurement and deployment choices in 2026. The deliverables include:
- Market sizing and scenario modeling: a top-down macro view plus three demand scenarios tied to policy, payment modernization, and enterprise security refresh cycles.
- Regulatory and standards matrix: mapping FIPS 201, ISO/IEC 7816, ISO/IEC 14443, FIDO and PKI requirements to procurement specifications across major verticals.
- Vendor diligence templates: a checklist and scorecard for RFPs covering cryptographic modules, certification footprints, lifecycle support, and supply-chain risk.
- Deployment playbooks: migration pathways from legacy contact systems to hybrid contact/contactless architectures, including infrastructure needs (e.g., cabling, RS-485 vs TCP/IP, edge-to-cloud integration).
- Commercial frameworks: licensing and maintenance models, cost-to-serve benchmarks, and contracting language to protect buyers against long lead times and support discontinuities.
- M&A and partnership lenses: indicators for strategic investments and potential consolidation targets based on market concentration and technological gaps.
We intentionally present these practical tools without disclosing the granular segmentation tables in this preview; the full dataset—broken down by region, interface type, and end-use—is reserved for subscribers to preserve competitive advantage for readers who elect to access the full report.
Competitive landscape: balancing innovation and compliance
The supplier field includes global incumbents with deep compliance pedigrees and regional players that compete on cost and integration flexibility. High-level concentration metrics tell a story of moderate consolidation: the three-largest firms capture a meaningful share of the market, and the five-largest materially extend that concentration. This structure creates both opportunities and risks for buyers. On one hand, established vendors reduce certification friction for government and regulated financial deployments; on the other, concentrated supply creates exposure to capacity constraints and pricing pressure during periods of rapid demand.
Representative suppliers in the competitive set include:
- Advanced Card Systems Ltd. (ACS) — a Hong Kong–based supplier with a broad portfolio spanning PC-linked, contact, contactless and mobile readers, and a strong presence in e-government and identity solutions. Recent activity: ACS showcased FIDO and NFC innovations and secured domestic certification pathways in key markets during early 2026.
- Identiv Inc. — U.S.-based provider of the uTrust reader family used for PIV/FIPS 201 and enterprise logical access control, with multiple USB and contactless models focused on identity ecosystems.
- HID Global Corporation — a major U.S. player offering OMNIKEY readers that integrate PKI, FIDO and access control capabilities for large enterprise and government programs.
- Thales Group and IDEMIA — European suppliers with an emphasis on high-assurance cryptographic implementations and strong ties to national eID and payment programs.
- Regional and specialist vendors — including secure payment terminal manufacturers and component specialists from Asia and North America who compete on embedded integration, cost, and route-to-market partnerships.
Recent vendor developments highlight two important dynamics. First, certification and standards alignment remain a gating factor for public-sector contracts—ACS’s 2026 test certifications and trade-show activity underscore how suppliers leverage compliance endorsements to accelerate adoption. Second, standards evolution continues to expand capability: the NFC Forum’s 2025 certification update (CR15) extended practical contactless read range, enabling richer use cases in convenience payment and mobile-onboarding scenarios. Buyers should treat standards updates as trigger points for procurement reviews rather than marginal upgrades.
Regulatory and standards considerations that should shape 2026 buys
- Government procurement often requires FIPS 201 or equivalent credentials; approved-product lists materially shorten procurement cycles but narrow supplier choice.
- ISO/IEC 7816 and ISO/IEC 14443 remain the interoperability bedrock for contact and contactless readers; any RFP absent explicit compliance statements will generate risk in cross-vendor deployments.
- Market access rules—such as BIS certification for specific geographies—must be embedded in sourcing timelines to avoid deployment delays.
These constraints mean procurement teams should front-load certification verification and request up-to-date compliance artifacts during the RFP stage. In many projects, the time-to-market delta caused by certification gaps exceeds hardware lead times.
Three strategic playbooks for 2026
From our advisory practice, three pragmatic strategies emerge for organizations planning deployments in 2026:
- Risk-aware innovation: pursue pilot programs with vendors that combine FIDO and PKI support but require contractual clauses for firmware updates, escrowed cryptographic modules, and interoperability testing across your incumbent systems.
- Phased migration with infrastructure alignment: adopt a staged replacement approach that synchronizes reader rollouts with network upgrades—especially when moving from legacy proprietary wiring to TCP/IP or RS-485 backbones. Include a migration lane for dual-interface (contact + contactless) readers to protect backward compatibility.
- Supplier ecosystem hedging: maintain at least two validated vendors per deployment region to mitigate supply-chain shocks. For high-assurance government or financial implementations, prioritize vendors with documented presence on government approved-product lists and an on-the-ground support footprint.
Procurement checklist — what to require in your RFP
- Explicit statement of standards compliance (ISO/IEC 7816, ISO/IEC 14443, FIPS 201 where applicable).
- Cryptography and lifecycle management details (supported algorithms, firmware signing, key escrow options).
- Interoperability test results and references for similar deployments in your vertical.
- Warranty, spare-parts lead times, and field-service SLAs calibrated to your risk tolerance.
- Roadmap alignment: vendor commitments on upcoming standards (e.g., FIDO evolution, NFC read-range improvements) and a plan for fielding critical updates.
Risks and red flags
Key risks we identify for 2026 decision makers include:
- Supplier concentration risk — a small set of firms account for a disproportionate share of installed bases and certification expertise, elevating the cost of switching.
- Standards drift — rapid updates to NFC and FIDO specifications can produce partial interoperability unless managed as part of procurement governance.
- Regulatory friction — jurisdictional certification requirements or approved-product lists can force last-minute vendor changes if not anticipated early in the procurement cycle.
How PW Consulting’s report helps you act
The full Smart Card Readers Market report translates the macro trajectory and supplier dynamics into blueprint-level guidance for 2026. Subscribers will receive:
- Complete market sizing and segmentation datasets (regional, interface, and end-use) with scenario-based projections through 2032.
- Vendor capability matrices and comparative profiles with direct links to certification records and recent product developments.
- Actionable deployment templates and contractual language to accelerate procurement while protecting against certification and supply risk.
In this preview we have deliberately withheld granular segmentation figures to preserve the strategic advantage available in the full dataset. Organizations seeking to align 2026 capital and operating plans with market realities should review the complete report for the methodological appendices, supplier scorecards, and downloadable RFP templates.
Next steps for leaders
If your 2026 plan includes identity modernization, point-of-sale refresh, or large-scale access-control replacement, start by: (1) mapping your certification requirements to target vendors, (2) initiating supplier pre-qualification to validate compliance artifacts, and (3) scheduling standards-impact reviews aligned to your procurement calendar. Early alignment with these steps will convert market momentum into operational advantage and reduce execution risk.
PW Consulting stands ready to brief executive teams and procurement committees with tailored insights from the report. For access to the full market dataset and customized advisory engagements, please contact our industry team or visit our report subscription page.
For detailed analysis of this topic, please visit the official page: Smart Card Readers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


