



PW Consulting: Microbes Protein Hydrolysates Market to Climb from USD 465.5 Million in 2025 to USD 721.0 Million by 2032, Expanding at a 6.45% CAGR

PW Consulting Releases Strategic Brief: Microbial Protein Hydrolysates Market — A Decision-Maker’s Guide for 2026
Executive Summary
PW Consulting today publishes an executive-level market briefing derived from our forthcoming Microbial Protein Hydrolysates Market report. This briefing synthesizes the macro trajectory, competitive dynamics, technology and feedstock trends, and regulatory inflection points that will shape commercial choices in 2026. Our analysis shows a resilient addressable market that expanded materially in the early 2020s and is forecast to continue growing at a compound annual growth rate (CAGR) of 6.45% during the 2026–2032 forecast window. With the global market exceeding USD 460 million by 2025 and a projection toward a substantially larger market by 2032, corporate strategies formed in 2026 will determine which players capture scalable share in the next growth cycle.
Microbes Protein Hydrolysates Market
Why 2026 Is a Strategic Pivot Year
-
Commercialization momentum is accelerating: Multiple pilot-to-scale transitions that began earlier in the decade are moving into sustained production and regulatory commercialization. 2026 is the year when several scale-up decisions, capacity allocations, and offtake arrangements will crystallize into durable competitive advantage.
Microbes Protein Hydrolysates Market -
Cost and feedstock debates shift from theory to practice: Producers are now choosing between gas-fermentation routes (methane/natural gas), autotrophic CO2‑and‑hydrogen systems, and traditional yeast fermentation tied to sugar feedstocks. Each pathway implies distinct cost curves, geographic capital intensity and environmental narratives—factors that buyers and investors will prioritize in 2026.
Microbes Protein Hydrolysates Market -
Regulation and market acceptance reach tipping points: Regulatory approvals for microbial single-cell proteins and related hydrolysates in feed and food sectors have already occurred in targeted jurisdictions. 2026 will reveal whether regulatory windows widen or remain patchwork—directly influencing go-to-market sequencing and risk allocation for new entrants.
Macro Snapshot: Trajectory and Scale
Our historical tracking shows the market expanding steadily through 2020–2025. By the base year (2025) the market scale surpassed the mid‑hundreds of millions (USD), reflecting both rising demand in feed/food and widening applications in pharma and bio‑stimulants. Under our central forecast, the market grows at a 6.45% CAGR for 2026–2032, reflecting the combined effect of industrial scale-up, broader regulatory approvals, and incremental application adoption across animal feed, food ingredients, and biotechnology uses.
What Our Report Delivers — Practical, Actionable Outputs
PW Consulting’s full market research report is structured to be directly operational for corporate strategy teams, investment committees and commercial leaders. Key deliverables include:
-
Strategic scenarios and 18–36 month decision playbooks: tailored for producers, ingredient buyers and feed formulators to prioritize markets, pick partners and schedule capital deployment.
-
Technology readiness and economics matrix: comparative techno‑economic analysis of methanotroph gas fermentation, autotrophic CO2/hydrogen routes, and yeast fermentation, showing capital intensity, operating cost drivers, and sensitivities to feedstock price swings.
-
Regulatory roadmap and risk register: jurisdictional summaries, approval pathways for feed and food, and recommended evidence packages to accelerate dossier acceptance and commercial clearance.
-
Supply chain stress tests and sourcing playbook: scenarios for feedstock shortages, logistics disruptions and long‑lead equipment, plus mitigation strategies including co‑location, feedstock hedging and contract structures.
-
Commercialization blueprints: go‑to‑market templates for B2B and B2B2C routes, licensing vs manufacturing make/buy decision trees, and price positioning models based on formulation economics.
-
M&A and partnership radar: a prioritized shortlist of strategic targets and partnership archetypes aligned to five distinct corporate strategies (vertical integrator, niche specialist, ingredient aggregator, licensing platform, and sustainability-first challenger).
Segmentation and Concentration (What We Reveal — and What We Privately Model)
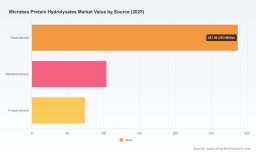
The market is segmented by region, source organism (yeast, bacterial, fungal and single‑cell proteins), and application (animal feed & pet food, food & beverage, pharmaceuticals & biotech, agriculture & bio‑stimulants). Publicly, we provide high‑level directional splits and growth vectors; within the full report we offer granular volume and revenue splits, price curves by application, and sensitivity runs. Market concentration is moderate: our CR3 and CR5 metrics indicate that top-tier specialists and industrial fermentation incumbents jointly command a meaningful portion of the market, leaving substantial room for differentiated challengers.
Competitive Landscape — Players to Watch
We profile established ingredient suppliers, fermentation innovators and vertically integrated feed players. Selected company dynamics observed in the last 18 months illustrate strategic patterns:
-
Unibio (Denmark) — A gas‑fermentation pioneer focused on methanotrophic single‑cell protein for aquaculture. Regulatory approvals for targeted uses and initial commercial shipments position Unibio as a practical case study for market entry via feed segments with clear safety endpoints.
-
Calysta Inc. (United States) — Developer of FeedKind via methane fermentation; the company’s operational shift toward concentrated manufacturing footprints (notably in joint ventures) illustrates a common industry tradeoff between distributed R&D presence and centralized commercial output.
-
Solar Foods (Finland) — Advances in autotrophic protein production (CO2 + hydrogen + electricity) underscore the growing role of electro‑driven bioproduction. Solar Foods’ product showcases for food applications highlight a dual pathway: premium food ingredients vs. scaled feed markets.
-
Angel Yeast, Kerry Group, DSM‑Firmenich, Corbion, Lallemand, and Alltech — These incumbents bring manufacturing scale, route‑to‑market breadth, and established formulations expertise. Their activities range from supplying yeast hydrolysates for cell culture to integrating fermentation‑derived ingredients into nutrition portfolios.
Recent Movements: Signals and Tactical Lessons
-
Product showcases and formulation demos (e.g., Solar Foods’ consumer‑oriented protein beverages) demonstrate that microbial proteins are transitioning from technical proof to consumer propositions; companies should plan for both ingredient specifications and consumer communication strategies.
-
Operational consolidations (e.g., Calysta reallocating resources toward joint‑venture manufacturing) show that capital discipline and production scale are prioritized over distributed R&D footprints once commercial validation is achieved.
-
Research breakthroughs in functionality (e.g., Angel Yeast’s yeast peptide synergies with mineral nutrition) highlight the innovation runway in value‑added hydrolysates beyond crude protein metrics — these functional claims can command premium pricing when supported by clinical or field data.
-
Regulatory approvals for specific feed uses (e.g., Unibio approvals for aquaculture) are practical enablers that materially reduce adoption friction; companies should coordinate regulatory strategy with early adopter customers to accelerate pathways to revenue.
Implications for Corporate Strategy in 2026
-
Prioritize feedstock and energy security: Given divergent process chemistries, secure access to low‑cost methane, renewable electricity, or sugar substrates early. Our scenarios show feedstock cost exposure dominates margin outcomes for many producers.
-
Design staged scaling with contractual de‑risking: Move from pilots to committed capacity using offtake-backed financing, modular plants, or JV structures to share capex risk while locking in demand from anchor customers.
-
Differentiate on function, not just protein: Investing in hydrolysis processes that yield defined peptide profiles or functional bioactivity creates defensible product tiers and reduces commoditization risk.
-
Adopt a regulatory-first commercialization calendar: Align product launches to jurisdictions with clear approval pathways and early adopter channels, particularly in feed segments that can accept novel ingredients more rapidly than human food.
-
Plan M&A and partnerships proactively: Larger ingredient players and fermentation specialists will be selective buyers; 2026 is an opportune window for mid‑sized innovators to seek partnership capital or strategic exits as markets consolidate.
How PW Consulting’s Report Supports 2026 Decisions
This briefing is a doorway to a comprehensive toolkit in the full PW Consulting report: downloadable data models, proprietary price and cost curves, ready‑to‑use commercial slide decks, regulatory dossier templates, and a prioritized partnership/M&A list. For strategy teams, the immediate value is threefold: accelerate due diligence with validated assumptions; reduce execution risk with proven scaling playbooks; and sharpen portfolio choices by marrying techno‑economic realities with market demand pathways.
Methodology and Confidence
Our analysis combines a bottom‑up build of supply capacity, expert interviews across producers and buyers, proprietary survey data, and a curated regulatory and patent landscape review. We apply conservative adoption curves for human food use and more aggressive trajectories for feed and industrial applications where regulatory pathways are comparatively established. Confidence bands are provided in the full report so decision‑makers can stress‑test outcomes under alternative feedstock, energy price, and regulatory timelines.
Next Steps — Access and Engagement
PW Consulting’s Microbial Protein Hydrolysates Market report is designed as an active decision support tool for teams making capital allocation, partnership and portfolio choices in 2026. This briefing intentionally highlights strategic lines of sight while reserving the granular segment tables, regional and application splits, and deal‑level company models for the full report. To obtain the complete dataset, scenario models and industry playbooks, please visit our report page or contact PW Consulting’s industry desk to schedule a deep‑dive workshop tailored to your organization’s strategic questions.
For detailed analysis of this topic, please visit the official page: Microbes Protein Hydrolysates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


