



PW Consulting Predicts Solid State Cooling Market to Reach USD 2,019.32 Million by 2032, Growing at a 12.48% CAGR

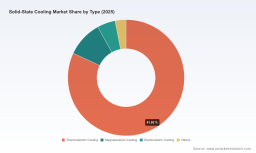
Solid State Cooling Market: Strategic Preview for 2026 Decision-Makers
As organizations plan product road maps, capital allocation and partnership strategies for 2026, PW Consulting’s latest Solid State Cooling Market report delivers the strategic intelligence required to make confident, timely decisions. This advisory brief previews the report’s high‑value insights: a macro view of market growth through 2032, the competitive landscape and technology inflection points, operational levers for rapid commercialization, and the practical frameworks we provide to translate opportunity into executable programs. Consider this a trailer — deep enough to inform priorities, intentionally withholding granular segment tables so stakeholders visit the full report for the complete playbook.
Solid State Cooling Market
Market snapshot: a fast‑maturing market with sustained double‑digit growth
Our analysis establishes solid‑state cooling as a growth market transitioning from niche, specialty deployments into broader commercial and industrial adoption. Using 2025 as the base year, the market is approaching a near‑billion dollar scale (USD, revenue in Million), and under our central forecast grows at a compound annual growth rate (CAGR) of 12.48% through the 2026–2032 horizon. The trajectory is non‑linear — the technology is already accelerating into adjacent applications as efficiency gains, regulatory pressure on traditional refrigerants, and system‑level integration reduce historic barriers.
Solid State Cooling Market
Key market structure signals worth noting for 2026 planning: the market demonstrates modest concentration with the top three firms representing a meaningful but not dominant share of global revenue (our CR3 and CR5 measures indicate a market that is competitive but consolidating). This dynamics profile favors both incumbent manufacturers focused on volume and reliability, and agile entrants that can capture premium niches with differentiated materials or integration expertise.
Solid State Cooling Market
Why this matters for 2026 strategy
- Prioritization: Firms must choose between scaling established thermoelectric product lines for near‑term revenue and investing in next‑generation materials and system architectures for longer‑term upside.
- Timing: With a steep growth curve expected in the latter half of the decade, 2026 is a pivot year — investments made now in supply chain resilience, prototype validation and standards alignment will compound advantage as adoption widens.
- Risk calibration: The market offers asymmetric upside but requires active mitigation of material supply constraints and realistic timelines for efficiency improvements to reach parity with vapor compression at larger scales.
Technology inflection: efficiency breakthroughs and their strategic implications
One of the most consequential developments we track is a 2025 breakthrough in nano‑engineered thin‑film thermoelectric materials, validated in laboratory refrigeration testing and recognized in industry awards. The technology promises substantial efficiency improvements versus incumbent bismuth‑telluride‑based modules, effectively compressing time‑to‑market for systems that can compete at larger cooling capacities.
Our scenario analysis models two outcomes: a conservative pathway where incremental material improvements steadily improve module performance, and a disruptive pathway where thin‑film solutions materially boost system‑level COP within three to five years. For executives, the implications are clear — treat advanced materials as both an opportunity and a hedge. Active R&D partnerships, selective licensing or minority investments in material innovators can be decisive in capturing the premium value pool if the disruptive pathway materializes.
Competitive landscape — positioning and strategic playbooks
The competitive field contains legacy thermal specialists, diversified electronics and power providers, and focused solid‑state system integrators. The market structure allows multiple strategic postures: scale‑oriented manufacturers, system integrators targeting high‑value use cases (cold chain, data center, medical), and nimble component specialists aiming to sell IP or kits for OEM integration.
- Established thermoelectric manufacturers : Companies with long histories in module production benefit from manufacturing scale, quality control, and established OEM relationships. Their near‑term playbook focuses on cost reduction, incremental efficiency improvements, and expanding into adjacent systems (e.g., integrated thermal subsystems for electronics and medical devices).
- Systems integrators and refrigeration challengers : Newer entrants focused on complete refrigeration and liquid‑cooling systems are commercializing on differentiated system architectures and control algorithms. Their advantage is speed of systems engineering and the ability to sell turnkey solutions into verticals emphasizing reliability and servicing.
- Diversified electronics and power companies : These players can bundle solid‑state cooling with power and thermal management offerings, enabling OEMs to adopt integrated modules rather than discrete components, which simplifies procurement and shortens time‑to‑market for customers.
- Material and component innovators : Emerging thin‑film and nano‑engineered material developers represent optionality for incumbents; strategic partnerships or supply agreements will likely determine who captures the first‑mover benefit from improved module efficiency.
Across all profiles, winners will be those that align product roadmaps with verified system KPIs, secure critical material supply, and build go‑to‑market models tailored to the dynamics of their target verticals.
Practical contents of the PW Consulting report — what executives will use on day one
The full report is built as a decision support kit rather than an academic compendium. It includes:
- Executive playbook: prioritized action items for R&D, supply chain, sales and M&A over 12–36 months.
- Technology roadmaps: a comparative assessment of thermoelectric, magnetocaloric, electrocaloric and emerging thin‑film approaches, with timelines to commercial readiness under alternative R&D scenarios.
- Supply chain heat map: raw material sensitivity modeling (notably reliance on bismuth telluride), supplier concentration analysis, and suggested mitigation strategies including sourcing diversification and inventory policies.
- Commercialization blueprints: go‑to‑market templates for OEM partnerships, channel development for medical and data‑center customers, and service economics for maintenance and warranty models.
- Scenario‑based financial models: revenue and margin projections under multiple adoption curves, with configurable inputs so CFOs can stress‑test CapEx, payback and IRR across strategic choices.
- Regulatory and standards matrix: practical guidance on aligning product design with prevailing data‑center, laboratory and industrial safety and performance standards.
Each section pairs executive summaries with downloadable templates, ready‑to‑use checklists and decision trees to accelerate planning cycles in 2026.
Regulation, standards and material realities — constraints and accelerants
Market dynamics are shaped not only by technical performance but by regulatory and standards frameworks. Heightened regulatory scrutiny of HFC refrigerants and global commitments to reduce greenhouse gas emissions increase the attractiveness of refrigerant‑free, solid‑state approaches for certain applications. At the same time, compliance with laboratory and industrial safety standards remains a gating factor for adoption in regulated sectors.
From a materials standpoint, conventional devices have relied heavily on bismuth telluride. That creates both a supplier risk and an R&D opportunity. Firms that lock in diversified material sources or that invest in next‑generation materials stand to reduce cost volatility and improve competitiveness. Our report includes pragmatic steps to classify supplier risk, design supplier scorecards, and implement alternate supply pathways.
Commercialization levers and go‑to‑market timing
Successful commercialization will require a calibrated combination of product, channel and service innovations:
- Focus on differentiated verticals where solid‑state cooling’s unique attributes (compactness, lack of moving parts, refrigerant‑free operation, precise temperature control) translate into higher willingness‑to‑pay — examples include medical devices, cold‑chain micro‑refrigeration, and high‑density electronics cooling.
- Pair hardware platforms with value‑added control software and predictive maintenance to convert one‑time hardware sales into recurring revenue streams.
- Design pilot programs and validation protocols that de‑risk adoption for conservative buyers (standards testing, field reliability data, clear failover strategies to traditional systems).
Timing matters: firms ready to scale production and channel partnerships by 2026–2027 will be well positioned for the accelerating demand in the late‑2020s captured by our forecast scenarios.
What to expect in the competitive battle for the market
Our competitive analysis identifies several operational differentiators that will determine market share shifts: manufacturing cost per Watt of cooling, system‑level COP in field conditions, integration capability with power and control architectures, and after‑sales service networks. Companies that can tangibly demonstrate superior lifecycle costs and total cost of ownership (TCO) in target verticals will convert pilots into scaled programs.
We also see a strong role for partnerships: incumbents with deep module know‑how and OEM access, vertically integrated electronics firms, and pure‑play system integrators will form alliances or pursue M&A to assemble complementary capabilities rapidly. PW Consulting’s deal screening framework in the full report helps executives identify the most synergistic targets and construct defensible valuation assumptions.
Next steps — how to use the report for 2026 planning
For 2026 board cycles and annual planning, treat this report as both a horizon scanner and an implementation toolkit. Use the scenario financial models to stress‑test capital allocation choices. Deploy the supplier heat map to triage procurement actions. And adopt the commercialization playbooks to prioritize pilots that will deliver measurable, investable KPIs within 12–18 months.
PW Consulting’s Solid State Cooling Market report is intentionally structured to move teams from insight to action. The summary above highlights the strategic contours and decision levers; the full report contains the granular segment intelligence, market sizing by sub‑segment, and downloadable models that leaders need to finalize budgets and execution plans.
For executives preparing 2026 strategies — whether you are scaling production, scouting technology partners, or evaluating M&A — this report provides the disciplined, market‑tested guidance required to convert emerging opportunity into realized competitive advantage.
For detailed analysis of this topic, please visit the official page: Solid State Cooling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


