



PW Consulting: Global Lock Market Set to Hit USD 58,466 Million by 2032, Growing at a 6.15% CAGR (2026–2032)

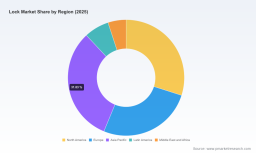
Lock Market 2026: Strategic Imperatives from PW Consulting’s Latest Market Intelligence
Executive summary
PW Consulting’s Lock Market report (base year 2025; historical 2020–2025; forecast 2026–2032) delivers a pragmatic intelligence package for executives planning resource allocation, product roadmaps, procurement strategies, and M&A activity in 2026. The global market is projected to expand at a steady compound annual growth rate (CAGR) of 6.15% through 2032, climbing from a 2025 base of roughly USD 38.5 billion to an expected market size in the high‑fifties billion USD range by the end of the forecast horizon. This growth trajectory masks important structural shifts—technology-led product substitution, cost pressure from raw material dynamics, and selective consolidation among security specialists—that will determine winners and laggards over the next 18–36 months.
Lock Market
Market outlook: what the headline numbers hide
The headline CAGR encapsulates a mixed reality. On one hand, continuing urbanization, residential retrofit demand, and commercial investment in access control are sustaining baseline demand. On the other hand, volatility in steel and metals, elevated tariffs introduced in 2025, and the rising complexity of digital access systems are redistributing margin pools and lengthening procurement lead times.
Lock Market
Importantly for decision-makers: aggregate growth does not guarantee profitable growth. The market remains relatively fragmented—three‑player concentration is low and adding two more top players still results in modest combined share—meaning scale advantages are uneven and differentiation is critical. At the same time, acquisitive moves by major players into high‑security and electronic niches are accelerating competitive realignment.
Lock Market
Key dynamics shaping 2026 choices
- Technology transition: The migration from purely mechanical solutions toward electronic and electromechanical systems is shifting value to software, cloud connectivity, and integration capabilities. Product roadmaps that fail to pair hardware reliability with secure firmware and lifecycle service models will lose price resilience.
- Supply‑chain and input cost pressure: Steel price swings and tariffs—most notably a material increase to Section 232 tariffs in mid‑2025 and tariff measures affecting North American supply chains—are amplifying input cost risk and supplier concentration in certain components.
- Moderate consolidation, targeted M&A: Large global access providers are selectively acquiring high‑security specialists and software-enabled startups to plug capability gaps. These strategic moves tighten competition in premium segments while leaving room for regional specialists.
- Regulatory and procurement complexity: Heightened procurement scrutiny in institutional and government channels (driven by concerns such as key control and firmware security) is raising certification and compliance costs—favoring providers with proven credentials.
Strategic implications for 2026 decision cycles
CEOs, heads of product, procurement chiefs, and corporate development teams should treat 2026 as a year to execute configuration choices that preserve optionality while protecting margins. The following implications should steer board-level discussions and budget allocations:
- Prioritize software‑ready hardware investments: Hardware players must accelerate programs that enable secure field‑upgradable firmware, standardized APIs, and interoperability with major access ecosystems. These investments protect resale value and create post‑sale service revenue.
- Re‑engineer procurement sourcing: Hedging strategies—longer‑dated supply contracts, dual‑sourcing for critical metal components, and near‑shoring for selected SKUs—reduce exposure to tariff shocks and freight dislocation.
- Segment go‑to‑market by value chain role: Differentiation across residential retrofit channels, commercial integrators, and institutional procurement requires distinct product bundles, pricing models, and certification pathways.
- Focus M&A on capability gaps: Buyers should prioritize targets that add patented key control, cryptographic expertise, or deep government credentials rather than broad bolt‑on volume plays.
Actionable playbook for 2026
The report equips decision-makers with a practical playbook. Below are prioritized actions companies can take within 6–18 months to materially improve competitive position.
- Cost & supply resilience
- Initiate a 12‑month supplier stress‑test across all critical metal, electronic, and IoT module suppliers; implement contingency contracts and minimum stock buffers for long‑lead items.
- Negotiate tariff‑adjusted terms and audit clauses tied to raw‑material indices to share upside and downside with strategic suppliers.
- Product & R&D
- Adopt a modular product architecture separating mechanical core, electronics, and cloud services to accelerate derivative production and simplify certification.
- Invest in over‑the‑air update capability and an embedded security certification roadmap (FIPS/common vulnerability management) to meet institutional buyer requirements.
- Commercial & pricing
- Move from pure unit pricing to outcome‑based contracts (availability SLAs, key‑control guarantees, lifecycle support) for commercial and institutional customers.
- Implement value communication strategies that quantify TCO reductions from smart access integrations—use conservative, auditable inputs for buyer confidence.
- M&A & partnerships
- Target high‑security niches and software firms for bolt‑on acquisition; prioritize cultural fit and route‑to‑market complementarity over headline revenue size.
- Establish co‑development agreements with system integrators and hospitality platforms to secure recurring revenue channels.
Competitive landscape: what to watch
The competitive map blends global platform players, legacy mechanical specialists, and software‑centric entrants. Leading incumbents maintain broad product portfolios spanning mechanical, electromechanical and electronic offerings; their advantages lie in scale, distribution networks, and brand credibility. Recent notable corporate moves reinforce the strategic thrust toward high‑security and software integration:
- ASSA ABLOY’s late‑2025 acquisition of a U.S. high‑security lock specialist, followed by integration activity completed in early 2026, exemplifies a play to consolidate high‑trust institutional segments and expand cryptographic and patented key‑control capabilities within a global distribution footprint.
- Major North American brands continue to leverage brand equity in residential channels while seeking product upgrades to remain relevant in connected‑home ecosystems.
- Regional manufacturers in Asia and emerging markets are maintaining competitive price positions and local content advantages—an important consideration for multinational procurement teams contemplating regional sourcing strategies.
Despite consolidation in targeted pockets, market concentration remains modest overall; this structure favors specialized entrants with strong technical differentiation and disciplined commercial execution.
Risk matrix and regulatory watch
Key risks for 2026 decision-makers include: raw material price shocks and tariff escalations, cyber vulnerabilities in connected locks, and procurement regulatory tightening in institutional markets. The report includes an up‑to‑date regulatory tracker and a scenario matrix that models the impact of different tariff and metal‑price regimes on gross margins and supplier lead times.
What’s inside the PW Consulting Lock Market report (practical contents)
To convert insight into action, the full report provides:
- Comprehensive market sizing and growth trajectories (base year 2025; forecast 2026–2032) with scenario variants tied to different tariff and technology adoption assumptions.
- Commercial playbooks and negotiation templates for raw‑material indexation and multi‑year supply agreements.
- Technology roadmaps and an evaluation framework for hardware/software integration, including a vendor assessment scorecard for firmware security, interoperability, and lifecycle support.
- Acquisition target screening criteria, valuation ranges by capability bucket, and integration checklists for high‑security and software deals.
- Regulatory and compliance digest covering institutional procurement standards, certification pathways, and an impact analysis of the 2025 tariff measures on cost structures.
- Dynamic dashboards and Excel models (segmentation, demand drivers and sensitivity analyses) that allow users to test bespoke price, volume and tariff scenarios relevant to supply, product mix, and geographies.
Note: This press summary intentionally omits detailed segment-level tables and unit‑level forecasts—those live datasets and interactive models are available within the full report and our client portal.
How executives should use this intelligence in 2026
Leaders should treat the report as both a diagnostic and executional toolkit. Recommended first steps:
- Run a 90‑day cross‑functional rapid review: procurement, product, legal, and strategy teams should map exposure to tariff and raw‑material scenarios and define countermeasures.
- Calibrate the 2026 product roadmap: prioritize modularization and security certification for SKUs exposed to institutional procurement.
- Prepare a prioritized M&A shortlist anchored to capability gaps, not revenue size; begin vendor conversations early to reduce deal cycle time.
Conclusion and next steps
The lock market in 2026 is an industry in transition: steady headline growth masks divergent value pools where technology, security credibility, and supply‑chain resilience command premium returns. PW Consulting’s Lock Market report converts macro forecasts into pragmatic decisions—supply strategies, product architectures, and acquisition screens—so executive teams can act decisively within constrained windows. For comprehensive datasets, interactive scenario models, and the full operational playbook, consult the full Lock Market report and accompanying client tools available through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Lock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


