



PW Consulting: Ion Chromatography Column Market Poised for 7.24% CAGR Through 2032

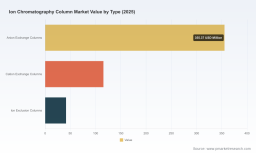
Ion Chromatography Column Market 2026: Strategic Preview for Enterprise Decision-Making
PW Consulting’s latest market study on the Ion Chromatography (IC) Column market is released as a strategic decision-support asset for boards, product leaders, and corporate development teams preparing their 2026 plans. The IC column market has demonstrated steady expansion—from approximately USD 365 million in 2020 to roughly USD 512.5 million in 2025—and our forecast shows momentum continuing into the coming decade, reaching an estimated USD 833.8 million by 2032 at a compound annual growth rate (CAGR) of 7.24% over the 2026–2032 forecast horizon. This brief synthesizes the report’s strategic value: what it enables executives to do in 2026, which competitive moves matter most, and how to convert market intelligence into measurable actions—while preserving the proprietary detail that makes the full study a must-read for implementers.
Ion Chromatography Column Market
Why the IC Column Market Matters for 2026 Strategy
Ion chromatography columns are a backbone technology in environmental testing, pharmaceutical quality control, food safety, and industrial process monitoring. Regulatory pressure (including evolving water and pharmacopoeial methodologies), the accelerating shift to automated and high-throughput platforms, and the recurring revenue dynamics of consumables are reshaping business models across OEMs, distributors, and laboratory service providers. For 2026 planning cycles, three structural forces should guide choices:
Ion Chromatography Column Market
- Regulatory codification and compliance demand: Recent compendial modernization recognizes IC in formal assay workflows, and IC systems and software must meet regulatory thresholds such as FDA/GLP and 21 CFR Part 11 for auditability.
- Platform automation and integration: Compact, automated instruments and integrated consumable bundles are shortening procurement cycles while raising the bar for vendor lock-in and aftermarket margins.
- Supply-chain resilience and specialization: Raw-material quality, column media innovation, and contract manufacturing footprints determine speed-to-market and cost competitiveness for column makers and system integrators alike.
What the PW Consulting Report Delivers — Practical, Decision-Ready Tools
This study is built as an applied toolkit, not merely a narrative. It is organized to support the full lifecycle of strategic decision-making in 2026—from boardroom scenarios to procurement tenders and product development sprints. Key deliverables include:
Ion Chromatography Column Market
- Market sizing and trend models: A transparent, auditable time series from 2020–2025 with scenario-based projections through 2032, including base, downside, and upside cases to stress-test budgets and revenue targets.
- Competitor benchmarking and playbooks: Comparative capability profiles for leading OEMs and specialist players—covering product breadth, channel strategies, regulatory credentials, and aftermarket approaches—paired with recommended competitive plays for incumbents and challengers.
- Regulatory and application matrix: An indexed reference of regulatory acceptance (e.g., compendial recognition and environmental method compliance) and its implications for product certification and market access strategies.
- Supply-chain and cost-to-serve maps: From resin suppliers and polymer backbones to contract column assemblers, highlighting single points of failure, margin pressures, and sourcing alternatives.
- Commercial templates and negotiation tools: Procurement scorecards, volume-discount models, and consumables-subscription frameworks designed for lab networks and service providers.
- M&A and partnership scouting: A disciplined framework for identifying bolt-on targets and partnership archetypes—plus anonymized candidate lists and valuation sensitivity checks for roll-up strategies in consumables and contract manufacturing.
- Technology roadmaps and R&D priorities: Prioritized innovation themes (media chemistry, lifetime optimization, guard-column strategies, and compatibility with next-gen eluents and detectors) tied to projected ROI.
Competitive Landscape — Who to Watch and What Their Moves Mean
The IC column market shows significant concentration at the top: the leading three firms capture the majority of industry value, and the top five command an even larger share. That concentration creates an environment where product launches, catalogue refreshes, and platform announcements materially re‑shape procurement and channel dynamics.
- Thermo Fisher Scientific — A broad portfolio and strong channel reach position it to continue bundling columns with systems and services, reinforcing aftermarket revenue streams through brand trust and global support.
- Metrohm AG — Longstanding regulatory alignment for water and environmental methods and an extensive column program make Metrohm a go-to for regulated laboratories; its catalog and compliance claims influence buyer specifications.
- Shimadzu Corporation — Continued investment in compact, automated IC platforms (most recently with a new, streamlined system introduced in early 2026) points to a future where instrument ease-of-use drives column attachment strategies and consumable sales.
- Agilent Technologies — As a broader LC/HPLC player, Agilent’s ability to cross-sell IC consumables into existing pharmaceutical and food labs creates expansion pathways distinct from niche IC specialists.
- Specialist and regional players (e.g., SHINE, Shodex, Tosoh, Bio‑Rad, GL Sciences) — These companies bring differentiated chemistry, local manufacturing scale, and price competitiveness. Their R&D patents and polymer media portfolios are key enablers of niche differentiation.
Recent industry moves—catalog releases and platform introductions from incumbents—underscore two clear trends: (1) instrument vendors are weaponizing integrated consumable ecosystems to reduce buyer churn, and (2) catalog and catalog-driven innovation cycles remain a primary mechanism for vendors to reassert relevance in regulated markets. For example, streamlined IC platforms and refreshed product catalogs announced over the past 12–18 months have already influenced lab procurement roadmaps for 2026.
Strategic Implications by Stakeholder
- C-suite/Corporate Development: Use our scenario models to set M&A buffers and to value recurring-consumable revenue streams. Consider defensive tuck-ins in high-margin consumables or contract-manufacturing assets to secure supply and margin control.
- Product & R&D Leaders: Prioritize compatibility with automated systems and invest in media chemistries that extend column life and reduce total cost per analysis—two features buyers will pay premiums for in 2026.
- Procurement & Supply Chain: Lock in tiered supply contracts and dual-source critical raw materials. Use the procurement scorecards in the report to re-bid major laboratory consortia and convert spot buys into subscription models.
- Sales & Marketing: Reframe value propositions around system-level efficiencies (time-to-result, regulatory fit, lifecycle cost), and deploy targeted account-based marketing to high-value regulated labs.
- Investors & PE Sponsors: Favor platforms with strong consumable attachment economics and clear regulatory moats; use our vendor scorecards and concentration analysis to identify consolidation targets with defensible margins.
How to Apply This Research in Your 2026 Planning Cycle
Practical application is straightforward. Start by running the three scenario projections against your 2026 revenue and cost assumptions. Overlay vendor- and region-agnostic procurement templates to quantify savings from supplier consolidation or subscription shifts. Use the regulatory matrix to prioritize product certification investments that unlock major institutional buyers. Finally, map your M&A thesis to the report’s financial sensitivity models to set acquisition price bands and integration timelines.
Because the full study includes detailed appendices—financial models, anonymized vendor scorecards, and a downloadable toolkit of negotiation templates—teams that pair the report with internal P&L workstreams will gain the fastest path from insight to measurable outcomes.
Closing — Why This Report Matters Now
2026 will be a year of consolidation and technological inflection for IC columns: automation will accelerate adoption, regulatory clarity will shift buyer specifications, and market concentration means a few strategic moves can materially change competitive dynamics. PW Consulting’s Ion Chromatography Column Market study provides both the high-level directional intelligence and the operational playbooks necessary to act decisively. For executives preparing budgets, investors evaluating targets, or product teams setting R&D priorities, the report converts market momentum into executable strategy.
For the comprehensive datasets, company scorecards, and executable templates referenced in this preview, access the full PW Consulting report. The full analysis contains the granular tables, models, and prioritized action plans required to operationalize 2026 strategy while protecting proprietary benchmarks and segmentation detail that we reserve for report subscribers.
For detailed analysis of this topic, please visit the official page: Ion Chromatography Column Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


