



PW Consulting Report: Fluorapatite Market Poised for 4.12% CAGR Through 2032

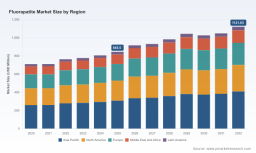
Fluorapatite Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
Executive snapshot
As global supply chains recalibrate and end-markets evolve, fluorapatite is re-emerging as a strategic industrial mineral with cross-cutting relevance — from fertilizers and industrial chemicals to high-value biomedical and specialty materials. PW Consulting’s latest Fluorapatite Market report (base year 2025; forecast period 2026–2032) synthesizes five years of historic performance with forward-looking scenario analysis, showing a market that expanded from roughly USD 710 million in 2020 to about USD 845.5 million in 2025 and is projected to grow at a steady compound annual growth rate (CAGR) of 4.12% through 2032. By the end of our forecast horizon the market is modeled to exceed USD 1.12 billion. For decision-makers preparing strategic plans in 2026, these topline dynamics flag both predictable continuity and new inflection points worth immediate attention.
Fluorapatite Market
Why 2026 is a pivotal planning year
-
Operational continuity vs. structural change: The modest but consistent CAGR masks a more nuanced reality — legacy fertilizer-centric demand remains foundational, while nascent applications (notably in biomedical formulations and specialty industrial chemistries) are creating higher-margin pathways. Boards and C-suite teams must decide whether to optimize existing value chains or to selectively invest in adjacencies.
Fluorapatite Market -
Supply-side recalibration: Recent permitting and mine development actions underscore that access to fluorapatite-bearing phosphate rock remains a live strategic variable. Domestic resource decisions and export dynamics will shape cost curves and supplier bargaining power over the coming decade.
Fluorapatite Market -
Regulatory and ESG pressure: Environmental constraints around mining, water use, and waste management are no longer peripheral risks; they are central to permitting, off-take agreements, and financing outcomes in 2026 and beyond.
What PW Consulting’s report delivers for 2026 decision-makers
Our brief is engineered as a practical playbook rather than a purely descriptive market study. Key deliverables that will change how leadership teams set 2026 priorities include:
-
Forward-looking scenario models calibrated to commodity cycles, alternative demand trajectories (including accelerated adoption in biomedical and specialty materials), and macroeconomic sensitivities. Models are provided in configurable formats to stress-test capital allocation under multiple macro cases.
-
Supplier and feedstock risk heatmaps that combine geological supply factors with permitting, logistics, and jurisdictional ESG exposures — enabling procurement and risk teams to prioritize strategic hedges and portfolio diversification actions.
-
An M&A and partnership playbook mapping inorganic entry points, integration pitfalls, and value-capture levers specifically tailored to fluorapatite value chains: upstream miners, mineral processors, wet-process phosphoric acid converters, and downstream specialty compounders.
-
Commercial go-to-market blueprints for manufacturers seeking to capture higher-value demand in biomedical and advanced materials, covering regulatory pathways, quality assurance benchmarks, and scale-up risk mitigation.
-
CapEx/OpEx optimization templates: practical unit-cost modelling, break-even analyses and phased investment roadmaps for brownfield upgrades and new processing lines to improve FAP (fluorapatite) extraction and beneficiation efficiencies.
Supply dynamics and raw material context
Fluorapatite’s industrial significance is rooted in phosphate rock. In the United States alone, marketable phosphate rock — overwhelmingly fluorapatite by mineral composition — was estimated at approximately 20 million tons in 2025. A combination of new mine approvals and brownfield upgrades in producer jurisdictions is starting to reshape near-term availability, but access remains uneven globally. Recent approvals for domestic mine development indicate that policymakers and regulators are seeking to sustain secure feedstock supply chains, while global exporters continue to influence regional cost dynamics.
For 2026 planning, procurement teams should treat feedstock access as a strategic lever. Actions include securing long-dated offtakes tied to conditional logistics clauses, investing in beneficiation capacity to upgrade lower-grade material, or co-investing with producers to secure priority access in tighter cycles.
Competitive landscape — who to watch
The fluorapatite market remains moderately concentrated. The top three producers account for roughly 42% of observable market capacity, while the top five account for close to 59% — a structure that yields both scale advantages and openings for niche differentiation. In practice that means large integrated fertilizer and phosphate groups will continue to set the baseline on cost and capacity, while specialized suppliers and vertically integrated chemical players can win pockets of value by offering technical differentiation.
-
Major integrated phosphate groups: Established firms with upstream phosphate rock assets and downstream fertilizer or chemical operations retain decisive leverage over volume and grade allocation. Their strategic priorities will include optimizing wet-process infrastructure, securing feedstock continuity, and selectively upgrading product lines for specialty customers.
-
Regional miners and national champions: State-backed or regionally dominant producers will play a pivotal role in shaping export availability and pricing corridors. Their investment decisions are often entwined with national food security and industrial policy.
-
Specialists and innovators: Emerging technology-driven firms scaling bioactive or high-purity fluorapatite for dental and biomedical markets are changing the margin calculus. The demo-scale success of such firms is a signal to incumbents: either partner early, acquire selectively, or risk margin erosion in higher-value segments.
Notable recent developments that inform 2026 strategy
-
Commercial-scale progress in bioactive fluorapatite manufacturing has advanced considerably. A notable scale-up and quality assurance milestone by a bio-focused firm in late 2025 demonstrates that path-to-commercialization timelines are compressing for high-purity applications. This accelerates the window for premium product commercialization and should prompt downstream players and investors to accelerate validation and regulatory planning.
-
On the resource side, a major permitting decision in 2025 approving a new phosphate rock mine underscores the continuing importance of domestic feedstock policies. Such approvals alter the risk calculus for supply continuity and should be factored into sourcing strategies and regional investment decisions in 2026.
Regulatory, ESG and technical risk matrix
Mining and processing of fluorapatite-bearing rock confront several convergent risks that materially affect project economics and timelines:
-
Environmental permitting and community impacts — habitat, water management and legacy land use issues are leading causes of delay and cost escalation.
-
Process-related environmental footprints — wet-process phosphoric acid plants, tailings management and fluorine handling require robust environmental controls and community engagement to sustain operations.
-
Quality and specification risks for higher-value applications — producing biomedical-grade or specialty industrial fluorapatite requires investment in purification, traceability systems, and regulatory compliance capabilities.
For executives updating 2026 roadmaps, integrating these risk vectors into capital allocation models and contracting terms (including force majeure and environmental covenants) is essential.
Investment and partnership priorities for 2026
Based on our analysis, leadership teams should prioritize a small set of high-impact moves in the coming planning cycle:
-
Secure flexible feedstock arrangements — mix short-term spot with medium-term offtakes and consider equity or JV positions in strategically located mines to de-risk access and capture upside.
-
Invest in product purity and certification capabilities — as biomedical and specialty chemical applications scale, premium pricing and margin sustainability will be driven by reproducible quality and regulatory clearance.
-
Pursue targeted collaborations with technology scale-ups — rather than full acquisitions, staged partnerships with emerging bioactive fluorapatite producers can provide optionality while limiting near-term capital exposure.
-
Tie ESG commitments to financing strategy — lenders and insurers are increasingly conditioning favorable terms on demonstrable environmental management and community engagement plans.
How PW Consulting’s report turns insight into action
Our deliverable is intentionally operational: it provides the quantitative scaffolding leaders need to convert strategic intent into executable 12–36 month plans. Clients receive adaptable financial models, supplier scorecards, and prioritized implementation roadmaps that translate the market’s modest growth profile and structural shifts into concrete opportunities and mitigants. Importantly, while this press summary highlights macro trends and strategic takeaways, the report contains the detailed, source-level analytics — including proprietary scenario outputs, supplier-by-risk matrices, and executable M&A playbooks — that executives will use directly in board-level deliberations and capital planning.
Final guidance for 2026 planning cycles
Fluorapatite’s market trajectory between 2026 and 2032 is characterised by measured growth underpinned by legacy fertilizer demand and punctuated by higher-growth niches driven by material science innovation. For leadership teams, the central dilemma in 2026 will be allocation: consolidate and defend low-margin volume channels or selectively invest to capture premium, higher-growth applications — ideally both, via strategic hedges and partnerships. Companies that align feedstock security, ESG-compliant operations, and targeted product differentiation will outperform in both stability and upside capture.
Next steps
PW Consulting’s Fluorapatite Market report equips decision-makers with the concrete tools required to operationalize these strategic choices in 2026. To access the full dataset, scenario workbooks, and actionable playbooks referenced here, visit PW Consulting’s market intelligence portal or contact our strategic advisory desk to arrange a tailored briefing for your executive team.
For detailed analysis of this topic, please visit the official page: Fluorapatite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


