



PW Consulting Forecast: Fog Computing to Skyrocket at 36% CAGR — From USD 10.85B in 2025 to USD 93.37B by 2032; Hardware Leads with USD 4.94B, North America Dominant, Market Remains Fragmented (CR3 18.5%)

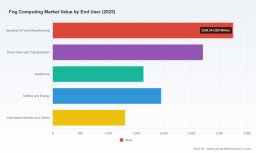
Fog Computing Market: Strategic Imperatives for 2026 — PW Consulting Market Outlook
As enterprises accelerate digital transformation beyond centralized clouds, fog computing is emerging as a mission-critical layer that reconciles the demands of real‑time intelligence, data governance and distributed operations. PW Consulting’s new Fog Computing Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) provides actionable intelligence designed to inform boardroom strategy, investment prioritization and deployment roadmaps in 2026 and beyond.
Fog Computing Market
Executive snapshot
The fog computing market has entered a phase of rapid expansion. After sustained multi‑year growth through 2025, global market value reached just over USD 10.8 billion in 2025 and is projected to expand to roughly USD 15.2 billion in 2026, continuing to escalate to the tens of billions through the 2030s. PW Consulting’s forecast models reflect a robust compound annual growth rate (CAGR) of 36.0% across the 2026–2032 horizon — a profile that demands strategic attention from CIOs, CTOs and corporate development teams planning spend, procurement and partner strategies for the next three years.
Fog Computing Market
Why this matters for enterprise decision‑makers in 2026
-
Latency, determinism and local data processing are no longer niche requirements. Industries from manufacturing to smart infrastructure are redefining where compute must live, making fog architectures essential to meet operational SLAs and deliver localized AI inferencing.
Fog Computing Market -
Data sovereignty and regulatory compliance complicate cloud-only approaches. Fog layers enable more granular control of data flows and retention policies — critical for regulated sectors and cross‑border operations.
-
Security expectations are escalating. Decentralized architectures expand the threat surface, and recent developments — including a 2025 patent milestone for quantum‑resistant fog node cybersecurity — underscore the need for future‑proof cryptography and anomaly detection at the edge.
-
Standards and governance are catching up. Institutional work by bodies such as NIST (fog conceptual models) and ongoing IEEE standardization activity for nomenclature and orchestration are creating clearer interoperability pathways; early engagement with these processes reduces vendor lock‑in risk.
-
Market structure matters. The supplier landscape remains fragmented — the upper tier of vendors does not dominate the space, leaving opportunities for vertical specialists, regional champions and platform innovators to capture share through partnerships and tailored solutions.
What the PW Consulting report delivers — practical, operational, and decision‑centric
-
Rigorous market sizing and methodology: transparent assumptions, scenario variants, and sensitivity testing to stress‑test your business case under alternative adoption curves.
-
Investment and ROI playbooks: step‑by‑step templates for building financial cases, calculating total cost of ownership for hybrid cloud–fog deployments, and prioritizing capex vs. opex in procurement cycles.
-
Use‑case prioritization matrices: an executable framework that maps latency, data gravity, regulatory needs, and operational criticality to candidate fog deployments, enabling rapid selection of pilots that maximize strategic value.
-
Security and compliance blueprints: practical controls, encryption roadmaps (including guidance on quantum‑resistant architectures), and vendor due‑diligence checklists to harden decentralized systems.
-
Deployment and operations playbook: reference architectures, orchestration patterns, lifecycle management practices and skills roadmaps for IT and OT convergence.
-
Vendor selection toolkit: an RFP template, scoring model and reference integration pathways to compare offerings without over‑relying on sales narratives.
-
M&A and partnership diagnostics: valuation benchmarks, integration risk matrices and thematic investment screens to inform corporate development activity in a rapidly consolidating ecosystem.
Competitive landscape — players and strategic postures to watch
The fog market is populated by a mix of hyperscalers, infrastructure specialists, semiconductor architects, industrial software firms and niche platform providers. Our analysis profiles the strategic positioning of leading actors and identifies the partnership archetypes enterprises should evaluate when building a fog stack:
-
Cisco Systems (San Jose, California) — an early proponent of the fog concept, offering network‑centric platforms and containerized execution environments at the fog/edge layer that appeal to industrial deployments requiring strong operational networking and security integration.
-
Dell Technologies (Round Rock, Texas) — focused on ruggedized servers and gateways optimized for distributed fog architectures; strengths lie in enterprise procurement channels and systems integration across IT and OT.
-
Microsoft (Redmond, Washington) — drives hybrid cloud–fog value through Azure Stack Edge and integrated AI/IoT services; compelling where cloud continuity, developer ecosystem and managed services matter.
-
ARM Holdings (Cambridge, UK) — supplies the energy‑efficient processor architectures foundational to many fog nodes and constrained devices, enabling power‑sensitive, large‑scale deployments.
-
FogHorn Systems (Sunnyvale, California) — specialist in on‑premises analytics and fog software platforms that convert sensor data into actionable real‑time intelligence for industrial automation.
-
GE Digital, Fujitsu, Schneider Electric — incumbents in industrial software and automation that embed fog capabilities within vertical applications such as asset performance management, smart manufacturing and energy optimization.
-
ADLINK Technology, Nebbiolo Technologies — hardware vendors delivering ruggedized modules and domain‑specific fog appliances for harsh or latency‑sensitive environments.
-
Crosser, IOTech — platform players providing open, lightweight orchestration and dataflow tools designed to bridge sensors, fog nodes and cloud analytics with minimal vendor lock‑in.
For enterprise buyers, the critical evaluation dimensions are interoperability, lifecycle support, ecosystem depth (industrial partners, ISVs), and evidence of field validation in comparable operational contexts.
Strategic recommendations for 2026
-
Embed fog thinking into IT strategy now: treat fog layers as a first‑class architectural domain within application roadmaps, not an afterthought once cloud constraints emerge.
-
Run focused pilots with clear KPIs: adopt a test‑learn‑scale approach using PW Consulting’s use‑case matrix to prioritize pilots that validate latency reduction, autonomy, and local decisioning.
-
Prioritize security and future‑proof cryptography: mandate cryptographic agility in contracts and consider quantum‑resistant pathways for long‑lived industrial deployments.
-
Negotiate for openness and portability: require adherence to emerging nomenclature and orchestration standards and insist on data export and portability provisions to prevent vendor lock‑in.
-
Build supplier ecosystems, not single vendors: given the market’s fragmentation, assemble partner coalitions that combine hyperscaler continuity, edge hardware resilience and domain‑specific analytics.
-
Upskill existing teams and hire for cross‑domain fluency: combine OT experience with cloud-native development skills and site‑reliability engineering focused on distributed compute fabrics.
Market concentration and M&A outlook
PW Consulting’s competitive benchmarking indicates a fragmented supplier base: the largest incumbents do not yet dominate the market, and even the top five suppliers control less than one‑third of market value. This composition creates fertile ground for strategic acquisitions — buyers will target vertical specialists, IP plays (especially in security and real‑time analytics) and hardware/software convergence assets. Expect partnership deals and bolt‑on acquisitions to accelerate in 2026 as incumbents seek to shorten time‑to‑market for integrated fog solutions.
Applying the report in practice — boardroom to shop‑floor
-
For executives: use the financial scenarios and risk matrices to align capex cycles with strategic objectives and regulatory calendars.
-
For product leaders: leverage the deployment blueprints to scope MVPs and scale transition corridors from pilot to production.
-
For procurement and legal: adopt the vendor selection toolkit and contract templates to secure interoperability guarantees and IP clauses that protect long‑term access to telemetry.
-
For corporate development teams: apply the M&A diagnostics to prioritize targets and model integration paths that preserve differentiated domain expertise.
How PW Consulting supports your 2026 decisions
PW Consulting combines deep market analytics with hands‑on implementation capabilities. Our advisory offering for fog computing includes bespoke scenario modeling, vendor diligence, pilot design and scaled rollout supervision, as well as workshops to align IT, OT and business stakeholders. The full report contains granular segmentation, proprietary market models, region‑ and use‑case breakouts, plus downloadable templates and financial models that we intentionally reserve for report subscribers and client engagements.
To move from strategic intent to operational impact in 2026, decision‑makers need both the macro view — reflected in strong growth and a high CAGR — and the micro playbooks that de‑risk deployment. PW Consulting’s Fog Computing Market report delivers both. For a complete copy of the report, detailed segment tables and our executable toolset, visit the PW Consulting research portal or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Fog Computing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


