



PW Consulting: Interactive Therapy Robot Market to Reach USD 5,232.3 Million by 2032, Accelerating at an 18.5% CAGR

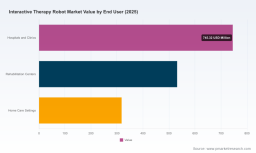
Interactive Therapy Robot Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
The Interactive Therapy Robot market is accelerating into a commercial phase that demands strategic clarity in 2026. PW Consulting’s new market study (base year 2025) documents a sustained expansion from early commercial traction into scale: the global market grew substantially through 2020–2025 and, with a compound annual growth rate (CAGR) of 18.5% across the 2026–2032 forecast window, is projected to multiply several-fold by the end of the period. For decision-makers—CEOs, clinical leaders, product chiefs, and payers—this creates a compressed window to convert pilots and clinical validations into reimbursable, scaled deployments. This brief highlights the report’s strategic value for 2026 planning while intentionally preserving the report’s detailed segment-level modeling to encourage direct access to our full analysis.
Interactive Therapy Robot Market
Why 2026 is an inflection year
-
Reimbursement architecture is shifting from theory to practice. The 2026 CMS annual update introduced new coding coverage for remote therapeutic monitoring and related device-driven therapeutic services. This changes the revenue calculus for interactive devices that can demonstrate therapy-adjacent outcomes and secure device data transmission pathways.
Interactive Therapy Robot Market -
Regulatory clarity is improving—but nuance matters. Some therapeutically positioned robots already occupy clear regulatory pathways (for example, devices classified under established medical device categories). At the same time, emotionally assistive robots that stop short of diagnostic or treatment claims can follow lower-risk pathways in many jurisdictions—if their labeling and clinical claims are carefully aligned with evidence. The report details risk-based regulatory mapping relevant to device claims, clinical protocols, and international market entry sequencing.
Interactive Therapy Robot Market -
Commercial proofs of concept are migrating from pilot to operations. Recent hospital and nursing home adoptions of AI-powered therapeutic robots have produced early operational evidence of reduced staff burden and higher patient engagement in targeted populations. Such deployments validate commercial propositions beyond the lab—but they also reveal new requirements in integration, interoperability, and clinical workflows.
Market dynamics and growth drivers
The market’s robust CAGR (18.5%) reflects the convergence of several durable drivers: demographic tailwinds in ageing populations, rising prevalence of chronic cognitive and neurodevelopmental conditions, increasing acceptance of non-pharmacologic interventions, improvements in conversational AI and human–robot interaction, and healthcare system imperatives to optimize labor and care utilization. Technology maturation is lowering unit costs while expanding functionality—making therapy robots increasingly viable not only in institutional settings but also in home and hybrid care models.
For strategic planning, three practical implications stand out: first, the relative speed of adoption will be governed by how quickly vendors convert clinical validation into reimbursement-ready evidence; second, procurement decisions will prioritize interoperability and data governance as much as device functionality; third, segmented go-to-market plays (clinical vs. consumer channels) will demand distinct commercial models and partnerships.
Competitive landscape: strategic profiles and what to watch
The ecosystem includes specialist therapeutic-device vendors, generalist social-robot companies, and AI-native entrants. The following profiles summarize the strategic positions and implications we analyze in the report.
-
PARO Robots U.S., Inc. / AIST — PARO is a market-defining therapeutic robot with a long clinical pedigree and regulatory recognition that has helped normalize device-based animal-assisted therapy in clinical settings. Its FDA classification underscores the importance of an evidence-aligned product claim. Strategic implication: incumbency provides a clinical moat, but sustained value requires continual evidence refresh and commercialization pathways tailored to payers.
-
Intuition Robotics (ElliQ) — ElliQ positions itself as an AI-powered companion optimized for home and assisted-living contexts, addressing loneliness and healthy aging. Its strengths are user-centered design and conversational engagement; commercialization hinges on partnerships with home-care providers and payers willing to fund preventive engagement models.
-
Expper Technologies (Robin) — Robin’s recent uptick in hospital and nursing-home deployments highlights the clinical market opportunity for child- and elder-focused engagement robots. Recent September 2025 deployment reports demonstrate real-world uptake in pediatrics and geriatrics, validating operational models and surfacing scale challenges around device lifecycle management and clinical workflow integration.
-
SoftBank Robotics (Pepper, NAO) — With broad robotics IP and enterprise deployment experience, SoftBank’s platforms are well positioned for scaled institutional rollouts. Their strength lies in platform versatility and partner ecosystems; strategic focus should be on certified clinical applications and developer certification programs.
-
Blue Frog Robotics (Buddy) — Buddy represents a consumer-leaning companion approach adaptable to therapy adjunct use-cases. The challenge is translating consumer affinity into clinically credible outcomes and payer-recognized value.
-
LuxAI (QTrobot) — QTrobot’s focus on developmental cohorts (e.g., children with autism) exemplifies the clinical niche strategy. Success depends on rigorous outcome trials, educational system buy-in, and pathway alignment with therapy providers.
-
Hanson Robotics (Sophia, Grace) — Hanson’s humanoid platforms bring high-fidelity social interaction potential, but commercialization in regulated clinical settings requires tight evidence and claims discipline given public perceptions and cost structures.
Across vendors, common strategic risks surface: evidence gaps, immature reimbursement pathways, procurement inertia in healthcare systems, security and privacy exposure, and the operational burden of device maintenance. Our report frames competitor moves against these risks and recommends tactical countermeasures for market entrants and incumbents alike.
What PW Consulting’s full Interactive Therapy Robot report delivers
PW Consulting’s market study is constructed as a practitioner’s toolkit for 2026 decision cycles. Key deliverables include:
- Market sizing and high-resolution forecasting (base year 2025; detailed projections through 2032) with scenario modeling to stress-test adoption tails and reimbursement uptake assumptions.
- Regulatory and reimbursement playbooks that map claims to evidence generation strategies and payer engagement calendars, including how to operationalize remote therapeutic monitoring pathways introduced in 2026.
- Go-to-market and commercialization frameworks for three archetypal routes: institutional (hospitals and clinics), specialized therapy centers, and home care / consumer channels.
- Clinical evidence design templates: pragmatic trial protocols, validated outcome sets for emotional and functional endpoints, and ROI measurement approaches tailored to hospital and payer priorities.
- Procurement and contracting tools: checklist templates for hospitals, managed-care contracting language, and pricing models (including subscription and outcomes-based variants).
- Technology and vendor due-diligence matrices that prioritize interoperability, cybersecurity, and maintenance economics.
- Competitive benchmarking and partnership maps—strategic implications and potential M&A scenarios.
The report intentionally omits here the granular segment tables and proprietary scenario matrices; these are available in the full document and regional annexes to support investment-grade decisions.
Strategic recommendations for 2026 decision-makers
Our recommendations are organized to be immediately actionable over 6–18 month horizons.
-
Prioritize reimbursement pathway creation now. Engage early with payers and regulatory bodies to align trial endpoints with payment criteria. Devices that can demonstrate measurable therapy-adjacent outcomes and integrated data transmission will be advantaged by the new remote therapeutic monitoring codes and similar coverage mechanisms.
-
Design evidence programs for procurement buyers, not just regulators. Combine randomized pragmatic designs with operational KPIs (staff time saved, therapy adherence, readmission impacts). Equip pilots with the data architecture to feed contractable outcomes.
-
Modularize product-to-service delivery. Separate core interaction software and hardware lifecycle services from clinical content so buyers can scale incrementally and manage total cost of ownership.
-
Build interoperability and security by design. Health systems will insist on secure device APIs, standardized EHR connectors, and auditable data governance—plan for certification and integration budgets early.
-
Adopt hybrid commercialization routes. Pair institutional pilots with home-care engagements to build longitudinal outcome evidence and expand payer use cases from episodic therapy to chronic-care support.
-
Seek strategic partnerships rather than solo scale. Clinical partners, home-care operators, therapy networks, and established medical device distributors can compress time-to-revenue and address procurement barriers.
-
Prepare for M&A and consolidation activity. As scale economics emerge, expect transaction activity where clinical-validated device platforms are combined with service-oriented operators; build an M&A playbook focused on integration of clinical and operational capabilities.
Closing: commercial selection as a discipline
Interactive therapy robots are moving from novelty to a practical adjunct in therapeutic portfolios. For organizations deciding in 2026, the choice is not simply “which platform” but “which commercialization discipline.” The winners will be those that align clinical evidence, payer engagement, and operational integration into a single, executable plan. PW Consulting’s full report supplies the quantified scenarios, procurement templates, and regulatory roadmaps necessary to convert interest into reimbursable deployments and defensible commercial scale.
For executives preparing budgets, pilots, or M&A pipelines in 2026, PW Consulting’s Interactive Therapy Robot market study is designed to be the playbook and the scoreboard. Contact PW Consulting to access the full report and the accompanying implementation toolkit.
— PW Consulting, Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Interactive Therapy Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


