



PW Consulting: Label Release Paper Market to Rise from USD 8.45B (base year 2025) to USD 11.19B by 2032 at 4.1% CAGR — Asia‑Pacific, Glassine Paper and Logistics & E‑commerce Lead Growth

Label Release Paper Market 2026: Strategic Imperatives from PW Consulting’s Market Release Paper
Executive overview
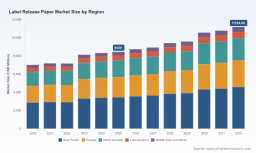
As companies prepare capital allocation, sourcing, and product roadmaps for 2026, the label release paper market presents a quietly expanding yet strategically complex landscape. PW Consulting’s latest Label Release Paper Market report (base year 2025, forecast 2026–2032) projects continued growth underpinned by a 4.1% CAGR across the forecast window. The market reached approximately USD 8.45 billion in 2025 and is forecast to progress steadily into the early 2030s, reflecting the combined pressures of packaging demand, sustainability regulation, and material innovation.
Label Release Paper Market
This paper introduces the analytical frames and practical tools that senior executives — from raw-material suppliers and liner manufacturers to converters, brand owners, and private equity investors — must use to translate macro growth into defensible, near-term decisions. In keeping with our “trailer” approach, we outline strategic conclusions and the report’s operational utility, while reserving the granular segment and regional tables for the full report available via our release page.
Label Release Paper Market
Why this market matters for 2026 decision-making
-
Regulatory inflection points are accelerating cost and design decisions. Extended Producer Responsibility (EPR) schemes implemented across several U.S. states and similar policy moves globally are reshaping total cost of ownership for labelstock and release liners.
Label Release Paper Market -
Sustainability is now a procurement imperative. Innovations that enable “recyclable with paper” performance for silicone-coated, fibre-based liners are moving from pilot to commercial launches, changing conversion economics and end-of-life logistics.
-
Supply-chain resilience matters. Raw material mix (glassine, SCK, CCK, kraft variants and poly-coated papers) and processing choices (PE lamination, silicone application, grammage choices) create discrete sourcing risks and margin levers that require active management in 2026.
Key report findings (high level)
-
Market trajectory: After a consolidated recovery through the early 2020s, the label release paper market shows steady expansion at a mid-single-digit CAGR (4.1% forecast 2026–2032). This trajectory supports targeted capex for capacity extension and selective premium product introductions.
-
Competitive dynamics: The market exhibits moderate concentration. A handful of global players hold a meaningful share of capacity and technology, while numerous regional specialists and new entrants fill niche and cost-driven roles. Recent product launches underscore the technological and sustainability arms race among incumbents and challengers alike.
-
Sustainability and recyclability are no longer optional. Doublesided silicone-coated fibre liners achieving recognized recyclability ratings are now commercially demonstrated, and investments to reduce basis weights and eliminate problematic laminates are accelerating.
What the report delivers — practical, transaction-ready content
Beyond headline growth metrics, PW Consulting’s Label Release Paper Market report is built for execution. Key deliverables include:
-
A transparent market-sizing methodology and reconciled historical series (2020–2025) plus baseline and upside forecasts for 2026–2032 — essential for budgeting and scenario planning.
-
Supplier and technology scorecards: comparative assessments of manufacturing footprint, substrate technology (glassine, supercalendered kraft, clay-coated kraft and poly-coated options), silicone processes, and product sustainability credentials.
-
Regulatory and EPR impact modelling: a practical module to quantify compliance cost exposure and mitigation timelines under multiple jurisdictional scenarios.
-
Procurement playbooks and sourcing risk heatmaps, including raw material substitution pathways, PE lamination trade-offs, and grammage optimization cases that materially affect conversion yields.
-
Commercial benchmarking, pricing sensitivity tools, and an M&A heatmap highlighting consolidation targets, value levers, and integration risk areas.
-
Implementation templates — from capex calculators to sustainability roadmaps — engineered for 90–180 day decision cycles.
Competitive landscape: what the leading suppliers are doing
Our strategic assessment synthesizes public disclosures, product launches, and on-the-ground market intelligence to profile incumbents and specialities shaping the market.
-
Mondi PLC (Austria): Leveraging integrated packaging and fibre assets to position paper-based release liners as sustainable alternatives to film. Expect continued emphasis on lifecycle messaging and captive channel wins with global packaging customers.
-
Loparex (U.S.): Specialist with deep capabilities in engineered papers and films; strength lies in technical customization and service models for converters requiring tight dimensional and silicone performance tolerances.
-
Ahlstrom (Finland): Rapid mover on recyclability — the recent Acti-V RRF Natural launch demonstrates a successful transition from lab to market for double-sided silicone-coated, paper-recyclable liners. This elevates Ahlstrom’s value proposition for brands under EPR pressure.
-
UPM Raflatac (Finland): Broad product range across paper and film liners, with distribution depth in labelstock channels; poised to convert strength in self-adhesive label markets into liner innovations tied to global brand customers’ sustainability programs.
-
Sappi (South Africa): Specialty paper capabilities and geographic reach make Sappi a key contender where high-quality glassine and specialty papers are required.
-
LINTEC Corporation (Japan) and 3M (U.S.): Both combine materials science, adhesive chemistry and liner technology, enabling differentiated propositions for industrial and high-performance label segments.
-
Fox River Associates (U.S.): Niche specialist in siliconized papers and film liners for industrial customers; customization and service are core strengths.
-
Shangrao Jinrong New Material (China): Regional manufacturer growing capacity and volume; relevant for cost-competitive supply corridors and local content strategies.
Recent product and regulatory signals to monitor
-
Ahlstrom’s Acti-V RRF Natural (Feb 2026) — commercialization of a double-sided silicone-coated liner that is recyclable with paper under recognized test methods. This development changes the trade-off calculus between performance and end-of-life compliance.
-
New low-grammage glassine liners (e.g., Nov 2025 product introductions) indicate a parallel route to sustainability: lowering basis weights to reduce material intensity while retaining necessary barrier properties.
-
EPR expansion across U.S. states and international jurisdictions is shifting total landed costs and compelling brand owners to demand traceability and better recyclability metrics from converters and liner suppliers.
-
Operationally, common industry responses include increased use of PE lamination to prevent silicone soak (noting the trade-offs this creates for recyclability), and grammage optimization across applications where performance tolerances permit lighter constructions.
Strategic implications and 2026 imperatives
For business leaders planning 2026 actions, the following priorities should guide resource allocation:
-
Integrate EPR into costing and product design. Treat EPR as a permanent input to pricing models and NPV calculations; prioritize liner technologies that reduce end-of-life costs.
-
Pivot from “sustainability marketing” to engineering-for-recyclability. Invest in validated recyclability test methods and third-party claims to avoid greenwashing exposures and to secure procurement contracts with large CPGs.
-
Targeted capex over broad expansion. Given the moderate market concentration, selectively expand capacity in high-growth niche segments (e.g., recyclable silicone-coated fibre liners) rather than blanket capacity builds that risk overexposure to commodity cycles.
-
Diversify raw-material routes and secure PE laminate alternatives. Identify strategic partnerships with pulp and specialty paper suppliers, and evaluate internalizing key coatings where margin and differentiation can be secured.
-
Accelerate product-service bundles. Converters who offer end-of-life takeback, recyclability documentation, and SKU rationalization provide compelling procurement efficiencies to brand customers under EPR rules.
-
Monitor consolidation and M&A targets. The competitive structure rewards both scale in global distribution and localized technical service; use our M&A heatmap to identify bolt-on targets and integration risks.
How PW Consulting helps
PW Consulting’s release offers not only market numbers but the operational playbooks that make those numbers actionable. Clients gain access to:
-
Customized scenario workshops that map EPR, raw material, and pricing shocks to P&L and capex choices.
-
Supplier due diligence templates, commercial negotiation playbooks, and a supplier scorecard tailored to liner technologies and sustainability credentials.
-
Transaction support — from target screening to integration plans — for buyers seeking consolidation plays or vertical integration into coated substrates and silicone application.
Next steps and accessing the full intelligence
This release highlights the strategic vectors that will define winners and laggards in 2026. The full PW Consulting Label Release Paper Market report contains the detailed regional, type, and application breakdowns, valuation models, and supplier-level scorecards that executives need to finalize budgets and procurement strategies. For executives looking to convert insight into action, access to the full dataset and implementation modules is essential.
To obtain the complete report, detailed segment tables, and custom advisory offerings, please visit the PW Consulting release page where the full intelligence package and client engagement options are available.
For detailed analysis of this topic, please visit the official page: Label Release Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


