



PW Consulting: Anti-Fingerprint Coatings Market Poised for a 6.45% CAGR Through 2032, Led by Asia‑Pacific Growth

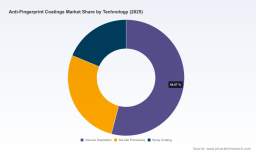
Anti-Fingerprint Coatings Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive Snapshot
PW Consulting’s latest market study on Anti-Fingerprint (AFP) Coatings—anchored on a 2025 base year with historical analysis from 2020–2025 and a forecast horizon of 2026–2032—clarifies the commercial trajectory and strategic levers executives must prioritize in 2026. The global market is projected to continue expanding at a compound annual growth rate (CAGR) of 6.45% through the forecast period, validating both short-term recovery dynamics and sustained mid-term demand across electronics, automotive, architectural, and medical end markets. By 2026 the market is poised to surpass the billion-dollar threshold in USD Million terms, and the PW model projects steady growth to the end of the forecast window.
Anti Fingerprint Coatings Market
Why this report matters for 2026 decision-making
-
Timing and investment prioritization: With a predictable mid-single-digit CAGR and clear technology substitution dynamics underway, procurement and R&D leaders can better time pilot-to-scale investment, balancing near-term product launches with longer-term reformulation needs driven by regulation and sustainability targets.
Anti Fingerprint Coatings Market -
Supplier selection and risk management: Market concentration metrics reveal a market where a handful of vendors exert notable influence on standards, formulation availability, and pricing. Our CR3 and CR5 analysis indicates a moderately concentrated supplier landscape—insightful for negotiations, dual-sourcing strategies, and M&A reconnaissance.
Anti Fingerprint Coatings Market -
Regulatory-driven product roadmaps: Regulatory momentum—most prominently the EU REACH phase-outs of legacy PFAS chemistries—makes 2026 a pivotal year for reformulation. Companies that proactively validate PFAS-free alternatives, or that have PFAS-free portfolios already, will gain a material advantage in qualification cycles for automotive and consumer electronics OEMs.
Core market dynamics (what we modeled)
Our modeling integrates demand-side adoption curves across primary applications, technology-specific capacity and cost trajectories, supply-chain exposure to key functional chemistries (fluoropolymers, PFPE, silanes, silica, and silicones), and regulatory transition scenarios. The output reconciles top-down market sizing with bottom-up revenues from manufacturing, surface treatment services, and specialty chemical sales—producing scenario bands that reflect variable adoption speed of PFAS-free alternatives and shifts in end-user specification.
Practical enterprise intelligence inside the report
-
Actionable supplier playbooks: Comparative supplier heatmaps, qualification lead-time benchmarks, and contract levers for securing supply of high-performance, PFAS-free chemistries.
-
Technology adoption roadmaps: Implementation guides for Vacuum Deposition, Sol-Gel Processing, and Spray Coating routes—covering capex scale-up, equipment selection, throughput economics, and expected performance trade-offs under real-world conditions.
-
Regulatory compliance trajectories: A scenario matrix mapping likely geographic regulatory changes to specific chemistry risks and reformulation timelines, enabling prioritized product requalification plans by region and industry.
-
Commercial and pricing intelligence: Proprietary indices tracking list- and transaction-level pricing trends, margin sensitivity by technology, and revenue pools by channel (manufacturers, Tier‑1 suppliers, coating-as-a-service providers).
-
M&A and partnership scouting: A prioritized list of acquisition and JV targets matched to strategic needs—capacity, chemistry IP, geographic presence, and application focus—plus modeled valuation multiples under differing integration synergies.
Competitive landscape — who matters and why
The AFP coatings arena combines specialty chemical innovators, surface engineering specialists, and global coatings conglomerates. Our competitive assessment focuses on technology differentiation, formulation IP, go-to-market motion, and recent strategic moves.
-
Aculon (San Diego, USA) : Aculon’s core competency is liquid-applied nano AFP chemistries tailored for easy application across metals, glass, and polymers. Their strength lies in low-barrier adoption for retrofit and aftermarket applications—an attractive value proposition for OEMs seeking short qualification cycles and minimal capital outlay.
-
Ionbond (Olten, Switzerland — IHI Group) : Ionbond combines physical vapor deposition (PVD) expertise with an emphasis on PFAS-free formulations for high-touch surfaces. Their offering is notable for marrying aesthetics, hygiene, and durability—attributes sought by appliance and premium consumer-goods manufacturers moving away from fluorinated chemistries.
-
Momentive (Waterford, USA) : With sprayable PFAS-free hydrophobic/oleophobic technologies that cover glass, metal, and plastics, Momentive targets customers requiring scalable, spray-line compatible solutions—important for high-mix electronics and industrial applications.
-
Henkel (Düsseldorf, Germany) : Henkel’s Loctite AF series and InvisiPrint offerings underscore their strategy: leverage strong OEM relationships in automotive and industrial segments while accelerating PFAS/fluorine-free alternatives. Recent 2026 product rollouts for automotive displays illustrate their pivot and provide a benchmark for Tier‑1 qualification expectations.
-
PPG Industries (Pittsburgh, USA) : PPG integrates AFP solutions into a broader performance coatings portfolio, enabling cross-selling into industrial and display OEMs. Their scale and distribution network are decisive advantages for projects requiring global roll‑out and extensive color/finish control.
-
Daikin Industries (Osaka, Japan) and AGC Inc. (Tokyo, Japan) : Both Japanese incumbents bring deep fluoropolymer know-how and durable chemistry platforms historically favored in high-performance displays. Their core challenge—and opportunity—is reformulating legacy offerings to meet emerging PFAS regulations without sacrificing longevity.
-
Rimex Metals (London/US) and Diamond Coatings (UK) : These specialist providers address high-touch architectural and metal interior markets with tailored finishes. Their competitive edge is substrate-specific expertise and design-centric finishes that combine anti-fingerprint functionality with aesthetic requirements.
Regulation, raw materials, and the PFAS inflection
Regulatory pressure—exemplified by REACH restrictions in the EU—has catalyzed a market-wide pivot from legacy PFAS-rich oleophobic top coats toward PFAS-free and silicone-based chemistries. This is not merely compliance theater: it reshapes supply chains, testing protocols, and performance expectations. Our analysis highlights three pragmatic implications for 2026:
-
Reformulation cost and qualification timelines will drive tiered adoption: product classes with long qualification cycles (automotive displays, medical devices) will need multi-year transition plans; consumer electronics can adopt faster via aftermarket and first-party application partnerships.
-
Material substitution creates transient raw material bottlenecks: shift in demand to silicones, silanes, and certain non-fluorinated fluoropolymer substitutes may concentrate sourcing risk; procurement must pre-qualify alternative suppliers and inventory strategies.
-
Performance parity versus legacy chemistries will be the gatekeeper for premium ASPs: vendors that can demonstrate durability, oleophobicity, and tactile fidelity without PFAS will capture higher-margin segments and secure preferred-supplier status.
Strategic recommendations for corporate leaders in 2026
-
Fast-track PFAS-free pilots: Prioritize pilots with vendors that already offer validated PFAS-free chemistries—especially for product lines slated for 2027+ launches. Use controlled A/B testing to quantify wear and tactile metrics under representative usage.
-
Design supply partnerships, not just contracts: Engage coating suppliers early in product design cycles to optimize substrate selection and surface finish tolerances; co-development reduces rework and accelerates cost-effective scale-up.
-
Embed regulatory scenario planning: Integrate the report’s regulatory scenario matrix into procurement and regulatory affairs dashboards to prioritize SKUs for reformulation based on anticipated market exposure.
-
M&A and bolt-on acquisition playbook: Targeted acquisitions of specialist AFP formulators or surface treatment service providers can accelerate access to PFAS-free IP and shorten qualification time for OEMs—particularly attractive for mid-sized manufacturers aiming to jump from localized capability to global supply.
-
Operationalize concentration risk mitigation: Use the market concentration insights to inform dual-sourcing strategies and longer-term supplier development programs—especially where single-vendor formulations could create downstream lock-in.
What PW Consulting’s full deliverable provides
This release is a strategic preview. The full PW Consulting Anti-Fingerprint Coatings Market Report contains the granular datasets, proprietary segmentation, and vendor benchmarking tables needed to operationalize the recommendations above. Subscribers receive: full regional and application revenue breakdowns, technology-specific cost curves, detailed company dossiers with SWOTs and contact strategies, M&A valuation scenarios, and turnkey templates for supplier scorecards and RFPs.
Next steps for executives
As 2026 unfolds, AFP coatings are shifting from a largely technical performance conversation to a strategic battleground defined by regulatory compliance, sustainable reformulation, and supplier integration. PW Consulting’s analysis equips product, procurement, and corporate development leaders with the scenario-based intelligence needed to prioritize pilots, secure supply, and make disciplined investment choices. For teams preparing annual budgets or product roadmaps this year, the window to secure advantageous supplier terms and to embed PFAS-free roadmaps is narrow—and decisive.
To access the complete dataset, segmentation tables, and the operational toolkits referenced in this preview, consult the full PW Consulting report. The detailed figures and actionable templates therein are intended for executive teams planning market entry, reformulation, or M&A activity in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Anti Fingerprint Coatings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


