



PW Consulting Forecast: Train Locomotive Suspension Market to Expand at 4.62% CAGR, Surpassing USD 1.262 Billion by 2032

Train Locomotive Suspension Market 2026 Outlook: Strategic Imperatives for Industrial Leaders
Executive Snapshot
PW Consulting’s latest market study — the Train Locomotive Suspension Market Report (base year 2025, forecast 2026–2032) — delivers a practice-oriented playbook for executives shaping product, procurement, and investment decisions through 2026 and beyond. The global market has demonstrated steady expansion from an estimated USD 735.12 Million in 2020 to USD 920.45 Million in 2025 and, under current assumptions, is projected to grow at a compound annual growth rate (CAGR) of 4.62% over the 2026–2032 forecast window, reaching roughly USD 1.26 Billion by 2032 (USD Million). Our research combines time-series market sizing, supplier-level capability mapping, regulatory and materials risk assessment, and scenario-led strategic options tailored for OEMs, Tier-1 suppliers, and asset owners.
Train Locomotive Suspension Market
Why this report matters to 2026 decision-makers
-
Actionable translation of macro momentum into boardroom decisions — The study converts market growth trajectories and concentration metrics (CR3 ~34.2%; CR5 ~47.85%) into three strategic choices: defend, diversify, or consolidate. These choices reflect realistic trade-offs for firms of different scale and margin profiles in 2026.
Train Locomotive Suspension Market -
Focus on operational levers with immediate ROI — Beyond demand forecasting, the report emphasizes near-term levers such as lifecycle services, refurbishment pathways, and specification upgrades that unlock value within typical 12–36 month investment cycles.
Train Locomotive Suspension Market -
Integration of regulatory and materials dynamics — With heightened scrutiny from safety authorities and persistent raw-material volatility, the report embeds compliance and input-cost scenarios into product roadmaps and sourcing strategies.
What the report contains (practical, use-case driven)
-
Robust market sizing and scenario models: time-series estimates for 2020–2025 and a probabilistic forecast for 2026–2032 that allow sensitivity testing under alternative inflation, commodity, and demand scenarios.
-
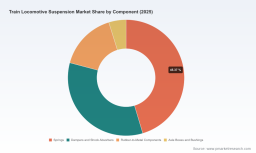
Segment structure and delta analysis: segmentation by region, component, and locomotive type, with a concise interpretation of which segments are structurally attractive and which require tactical defense. (Note: detailed segment-level tables and granular values are reserved for report subscribers.)
-
Competitive capability map: comparative assessment of incumbent technology stacks, manufacturing footprint, aftermarket capacity, and R&D pipelines across leading suppliers, enabling quick benchmarking and target-setting for partnerships or M&A.
-
Procurement playbook: supplier risk heatmaps, alternative-material sourcing options, price pass-through clauses, and tactical hedging instruments calibrated for common lead-times and contract cycles in rail programs.
-
Product and engineering roadmaps: prioritized R&D themes (e.g., elastomer composite longevity, sealed hydraulic dampers, modular bogie interfaces) with estimated implementation timelines and tech-readiness checkpoints for 2026 planning.
-
Aftermarket and service strategies: monetization models for refurbishment, predictive maintenance, and long-term service agreements designed to offset OEM cyclicality and to capitalize on fleet modernization programs.
-
Regulatory compliance matrix: requirements mapping (including key standards and inspection regimes) with operational impact and certification timelines to support procurement and product validation schedules.
-
Executive playbook and decision trees: step-by-step guidance for determining whether to invest, partner, or divest across prioritized markets and technologies.
Competitive landscape: what to watch in 2026
Our benchmarking identifies a mix of diversified industrial incumbents and specialized niche suppliers shaping the suspension value chain. Leading players combine engineering depth, long lifecycle product programs, and aftermarket capabilities — a profile that favors firms able to deliver certified, durable hardware plus long-term service agreements.
-
Technology-integrated incumbents: Companies with broad portfolios in springs, air-suspension systems, and rubber-metal composite assemblies maintain advantages in OEM qualification and system integration. Their strength is reinforced by established refurbishment programs that protect margin over long asset lives.
-
Specialist damper and shock manufacturers: Dedicated hydraulics and friction-control suppliers offer differentiated ride-quality solutions and rebuildable assemblies. Their value proposition is higher unit-level engineering intensity and potential for lucrative aftermarket contracts tied to ride-performance upgrades.
-
Spring specialists and regional fabricators: Precision spring manufacturers and local suppliers remain critical to heavy-haul and regional fleets, particularly where customization, short lead-times, or local content rules influence procurement.
Representative firms covered in the report include market-leading and specialist names across Europe, North America, and Asia-Pacific. For executives preparing 2026 sourcing strategies, the report’s supplier profiles highlight where proprietary IP, refurbishment capability, and service networks concentrate, and where partnership or near-shore manufacturing could materially shorten delivery cycles.
Market dynamics and macro risks
-
Fleet modernization and retrofit demand — Major locomotive contracts and modernization programs (including sizable multi-year deals announced in 2025) are driving near-term demand for upgraded suspension and bogie systems. Suppliers should anticipate procurement windows aligned with locomotive delivery and mid-life overhaul schedules.
-
Alternative-fuel program uncertainty — Pauses or funding shifts in hydrogen or other alternative-fuel rolling-stock programs can create asymmetric demand shocks for suspension components tailored to new architecture. Firms with balanced portfolios across conventional and alternative platforms will be better insulated.
-
Regulatory tightening and certification timelines — Safety authorities have reaffirmed inspection and validation requirements for suspension and bogie systems. Compliance-driven design changes and extended testing protocols will require capital and calendar adjustments in 2026.
-
Raw-material and supply-chain volatility — High-grade steel, elastomers, and hydraulic fluids remain cost drivers; price and availability fluctuations can compress margins or lengthen lead-times. The report quantifies probable cost-pass-through thresholds and recommends tactical and strategic mitigants.
Strategic implications and recommended actions for 2026
-
For OEMs: Prioritize modularity and serviceability. Design decisions made in 2026 should reduce lifecycle retrofit costs and enable standardized service modules that third-party maintainers can support — a practical lever to lengthen revenue tails from the installed base.
-
For Tier-1 suppliers: Invest selectively in high-durability elastomer composites and sealed damper technologies that extend maintenance intervals. Coupling technical upgrades with performance-based warranties will win procurement evaluations where total cost of ownership dominates.
-
For private-equity and M&A teams: Target scale-additive acquisitions that increase aftermarket reach or secure specialized technologies (e.g., long-life hydraulic dampers, OEM-quality air-spring refurbishment). The market concentration metrics indicate room for value creation through consolidation in specific subsegments.
-
For procurement and supply-chain leaders: Implement multi-sourcing strategies for critical inputs and embed commodity-price contingency clauses in contracts. Near-shore manufacturing or strategic inventory buffers for elastomers and high-grade steels can reduce exposure to delivery disruptions.
-
For R&D and product teams: Shortlist technologies that respond to both regulatory requirements and operator pain points — noise, ride comfort, and lifecycle cost. Rapid validation pathways and early engagement with certification bodies should be built into product roadmaps to avoid rework delays.
Case-in-point evidence from recent developments
Large-scale rolling-stock contracts and modernization agreements announced in 2025 illustrate the real-world demand drivers for suspension upgrades and services. Simultaneously, strategic pauses in alternative propulsion projects highlight the need for portfolio resilience. PW Consulting’s report translates these signals into timing implications for kit deliveries, aftermarket revenue phasing, and supplier capacity planning — all calibrated to 2026 procurement cycles.
How executive teams should use this analysis
-
Board-level strategy sessions: Use our decision trees to set a clear 12–24 month posture (accelerate technology investment, pursue bolt-on acquisitions, or monetize aftermarket assets) tied to explicit financial thresholds.
-
Commercial and bid teams: Apply the report’s win-the-bid playbook to structure offers that balance capex, service-level commitments, and certification deliverables — an advantage in long-duration locomotive contracts.
-
Supply-chain operations: Implement the procurement playbook to reduce single-source exposure and to align contractual incentives with supplier capacity expansions or regional content requirements.
Next steps — where to get the full intelligence
This briefing is designed to preview the depth and practical utility of the full PW Consulting Train Locomotive Suspension Market Report. In order to preserve the commercial value of granular segment tables, supplier scorecards, and model inputs — which form the basis for operational decisions — we reserve those datasets for subscribers and clients. The full report contains downloadable scenario models, supplier shortlists, and executable implementation checklists tailored to 2026 procurement and investment calendars.
Contact and access
Senior executives and strategy teams looking to incorporate these findings into 2026 planning cycles are invited to download the full report or request a bespoke briefing with PW Consulting’s rail practice. Our analysts will walk through the scenario models, validate assumptions against your fleet or product portfolio, and co-develop 12–36 month roadmaps aligned with your strategic priorities.
For detailed analysis of this topic, please visit the official page: Train Locomotive Suspension Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


