



PW Consulting: Hydrogen Cooling Synchronous Condenser Market Poised to Grow at a 5.86% CAGR Through 2032

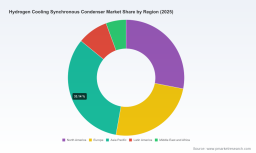
Hydrogen-Cooled Synchronous Condenser Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting’s latest market research report on the Hydrogen Cooling Synchronous Condenser Market positions 2026 as a decisive inflection point for utilities, original equipment manufacturers (OEMs), investors and system integrators navigating the transition to renewable-dominant grids. Built on a 2020–2025 historical baseline with a forward-looking forecast to 2032, the study combines quantitative market sizing, scenario-driven technology assessments, vendor benchmarking and actionable procurement playbooks to inform capital and operational choices in the year ahead.
Hydrogen Cooling Synchronous Condenser Market
Why 2026 Matters: Market Trajectory and Strategic Implications
The market for synchronous condensers incorporating hydrogen cooling has shown steady expansion through the mid-2020s and enters 2026 with clear momentum. From the early-2020s baseline, aggregate market value climbed materially by 2025, and our forecast indicates continued growth through the end of the 2026–2032 horizon at a compound annual growth rate (CAGR) of approximately 5.86%. In dollar terms, the market trajectory underlines a multi-year ramp that will meaningfully influence procurement cycles, manufacturing capacity planning and aftermarket service strategies for incumbent and emerging suppliers alike.
Hydrogen Cooling Synchronous Condenser Market
For corporate strategists and utility planners, this trajectory translates into three practical realities for 2026 decisions:
Hydrogen Cooling Synchronous Condenser Market
- Procurement windows are compressing as grid operators accelerate system-strength projects; lead times for hydrogen-capable rotating machinery must be baked into multi-year project timelines.
- Manufacturing and supply-chain scale-up is required to capture share; firms that de-risk hydrogen handling, sealing and purity supply chains stand to gain negotiating leverage in upcoming tenders.
- Risk-adjusted capital allocation should incorporate hydrogen-specific O&M profiles and safety compliance costs—factors that materially affect lifecycle economics compared to air- or TEWAC-cooled alternatives.
What the Report Contains: Practical, Executable Intelligence
PW Consulting’s report is structured around decision-centric outputs designed to be used at the boardroom and project-execution levels. Key deliverables include:
- Market sizing and validated forecasts (base year 2025; forecast horizon 2026–2032) with scenario analyses that stress-test volumes and revenue outcomes against decarbonization pace, policy changes and technology substitution.
- Technology deep dives comparing cooling architectures (with special emphasis on hydrogen-cooled systems), system-level thermal performance, failure modes, and lifecycle maintenance considerations.
- Practical procurement playbooks and specification templates tailored to transmission operators and independent power producers, including risk controls for hydrogen handling, seal maintenance and purity monitoring.
- Vendor benchmarking including capabilities mapping, delivery footprints, EPC archetypes and aftermarket service models—presented to enable “shortlist-to-RFP” conversion within six months.
- Financial modelling tools and sensitivity matrices that integrate capex, opex, spare-part provisioning and reliability assumptions—designed to yield transparent payback and IRR implications under multiple grid evolution scenarios.
- Case studies and lessons-learned from recent global projects, illustrating deployment challenges, construction sequencing and commissioning protocols in high-renewables environments.
Competitive Landscape: Who Matters and Why
The hydrogen-cooled synchronous condenser market exhibits a concentrated leader set, with the top three to five suppliers accounting for a substantial share of industry revenue. This concentration creates both opportunities and constraints for market participants: established manufacturers enjoy scale and legacy expertise in large rotating machinery, while specialized suppliers and regional players compete on responsiveness and local content.
Notable market participants profiled in the report include long-standing rotating machinery manufacturers and power-electronics integrators that have direct or transferable experience with hydrogen-cooled systems. These firms bring complementary strengths:
- Historical expertise in hydrogen-cooled large machines and global project delivery (e.g., firms with legacy hydrogen-cooled generator portfolios).
- Turnkey capabilities that pair synchronous condenser hardware with system controls, reactive-power management and inertia emulation solutions.
- Regional manufacturing and service networks that reduce logistical friction on large station-class equipment.
Recent procurement and contractual developments underscore market dynamics that corporate leaders should note. In the past 18 months, multiple major awards and EPC appointments demonstrate active demand for synchronous condensers to shore up grid strength as thermal synchronous plants retire and renewables scale. These transactions validate the technology choice in renewal programs and highlight the importance of delivery certainty and local content in award evaluations.
Industry Dynamics: Technology, Regulation and Supply-Chain Realities
Hydrogen cooling is favored in large-scale utility rotating machinery for its high thermal conductivity and low density—qualities that enable higher continuous ratings and favorable thermal performance compared to air-cooled alternatives. However, hydrogen introduces distinct engineering, safety and operational disciplines:
- Hydrogen handling requires robust sealing systems, purity control regimes and leak-detection infrastructure; failure modes differ from air-cooled systems and can affect maintenance periodicity and spare-part strategies.
- Regulatory and procurement frameworks vary: some transmission operators explicitly prefer non-hydrogen-cooled solutions to avoid the complexity and lifecycle costs associated with hydrogen management; others specify hydrogen cooling to achieve higher unit ratings and efficiency.
- Policy programs that enable high-capacity renewable integration—such as state-level Renewable Energy Zones—are accelerating demand in certain markets and shaping tender specifications around system strength deliverables (inertia, short-circuit power, dynamic reactive support).
For strategists, the interplay of these dynamics implies that technology choice is not purely technical—tender language, regulatory risk, and operating-environment factors will often drive whether hydrogen-cooled synchronous condensers are the optimal solution for a particular grid project.
Strategic Recommendations for 2026
Our analysis yields a set of prioritized actions for stakeholders planning near-term commitments in 2026:
- Utilities and system operators: Accelerate early engagement with suppliers to lock delivery windows and define hydrogen-specific acceptance tests. Introduce explicit lifecycle clauses in tenders that cover hydrogen seal maintenance, purity monitoring and emergency procedures.
- OEMs and EPCs: Parallelize capacity expansion with targeted investments in sealing technology, sensorized hydrogen monitoring and local service hubs. Prioritize modular designs that permit retrofitting of cooling architectures where regulatory or site constraints emerge.
- Investors and financial sponsors: Stress-test project models with hydrogen-specific O&M assumptions and scenario-based downside analyses that reflect alternative cooling architectures. Consider partnering with service providers to capture aftermarket margin streams tied to hydrogen management.
- Policy-makers and regulators: Provide clarity on safety standards, inspection cadences and allowable leakage thresholds to reduce tender-to-contract uncertainty and accelerate project bankability.
Risk Map: What Keeps Buyers and Sellers Up at Night
The report’s risk matrix synthesizes the material threats that could derail projects or compress returns:
- Operational risk from hydrogen leakage or seal degradation leading to unplanned outages or extended maintenance windows.
- Procurement risk stemming from ambiguous tender specifications or late-stage shifts away from hydrogen cooling in favor of air-cooled alternatives.
- Supply-chain risk for critical components (specialized seals, purity monitoring instrumentation) that have limited global suppliers.
- Regulatory risk where differing national and regional codes create fragmentation and increase compliance costs for multinational vendors.
Each risk is accompanied in the full report by mitigation strategies, contract clauses, and sample inspection protocols designed to be directly incorporated into procurement documents.
Execution Playbook: From Shortlist to Commissioning
One of the report’s most operationally valuable sections is a step-by-step execution playbook tailored for 2026 projects. It covers:
- Pre-RFP design checks and site-suitability assessments, including hydrogen-safety zoning and ventilation modelling.
- Bid evaluation scorecards that weight delivery certainty, hydrogen risk controls, and aftermarket support.
- Factory-acceptance-test (FAT) templates and commissioning sequences that prioritize hydrogen-system integrity and protection settings tuning for inertial response.
- Aftermarket service schedules and digital monitoring architectures to minimize unplanned downtime and extend interval lengths between invasive maintenance.
These templates are intentionally prescriptive so that procurement and project teams can reduce bid-to-operation timelines while preserving risk transfer and performance guarantees.
Conclusion: Positioning for the 2026 Inflection
As the synchronous condenser market shifts from pilot-phase deployments to mainstream utility adoption, 2026 will reward organizations that integrate technical rigor with commercial foresight. The market’s upward trend—reflected in our validated historical series and 2026–2032 forecast at a mid-single-digit CAGR—creates opportunity windows for suppliers able to prove hydrogen-handling competence and for buyers who structure tenders to monetize capability while controlling operational exposure.
PW Consulting’s Hydrogen Cooling Synchronous Condenser Market report is designed to be an executable bridge between strategy and operations—equipping executives with the market context, vendor intelligence and contractual instruments needed to make confident, de-risked decisions in 2026. To access the full dataset, proprietary segment analysis, and downloadable procurement templates, please visit the PW Consulting report landing page and request the complete report package.
For detailed analysis of this topic, please visit the official page: Hydrogen Cooling Synchronous Condenser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


