



PW Consulting: Power over Ethernet (PoE) Chipset Market Poised to Grow at a 14.05% CAGR, Driving Next-Gen Networking Adoption

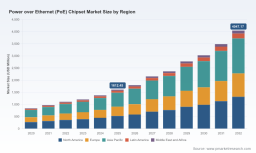
Power Over Ethernet (PoE) Chipset Market: Strategic Imperatives for 2026 — PW Consulting Preview
As enterprises accelerate edge compute deployments, modernize building infrastructure, and scale AI-driven networking, PoE chipsets have emerged as a practical, high-leverage technology for delivering power and data over a single Ethernet cable. PW Consulting’s upcoming PoE Chipset Market report (base year 2025, historical scope 2020–2025, forecast 2026–2032) synthesizes primary research, vendor interviews, and supply-chain stress-testing to deliver an actionable roadmap for procurement, product planning, and capital allocation in 2026.
Power Over Ethernet Poe Chipset Market
Market Trajectory at a Glance
Our firm-level modeling shows sustained expansion of the global PoE chipset market. After recovering from early-decade volatility, total industry revenues climbed to approximately USD 1.61 billion in 2025 and are projected to reach roughly USD 1.79 billion in 2026, with a compounded annual growth rate (CAGR) of 14.05% through the forecast window. By 2032 the market is modeled to exceed USD 4.0 billion — a near-tripling over the decade driven by higher-power PoE classes, enterprise networking refresh cycles, and cross-domain adoption spanning IP video, lighting, industrial automation, and next-generation Wi‑Fi and IoT endpoints.
Power Over Ethernet Poe Chipset Market
Why This Matters for 2026 Strategic Decisions
- Timing investments: The forecasted acceleration in 2026 means device OEMs and system integrators can no longer treat PoE as a marginal option; it should be central to product roadmaps and channel incentives for the next three years.
- Technology selection: With IEEE 802.3bt and higher-power variants enabling previously impractical use-cases (from advanced PTZ cameras to PoE lighting), architecture decisions made in 2026 will determine compatibility and upgrade paths through 2032.
- Supply chain posture: Extended semiconductor lead times and component competition from AI and EV sectors make 2026 the year to institute multi-tier sourcing, safety stocks, and design-for-availability strategies.
- Vendor negotiation and consolidation risk: Market concentration metrics indicate a non-trivial portion of revenues are controlled by leading chipset vendors — a structural factor buyers should fold into contract cadence and contingency planning.
What the Report Contains — Practically Applicable Deliverables
PW Consulting’s report is designed as a decision-support toolkit for executives, product managers, CIOs, and procurement teams. The deliverables include:
Power Over Ethernet Poe Chipset Market
- Top-line market forecast and scenario analyses (base, upside, and downside) for 2026–2032 with sensitivity to lead-time disruption and standard adoption rates.
- Vendor scorecards and an actionable vendor-selection matrix that balances technical performance (efficiency, thermal profile, power limits) with commercial levers (pricing bands, support, roadmap commitments).
- Supply-chain stress tests and mitigation playbooks that quantify the impact of 30–42 week lead times on BOM timing and propose replenishment policies and dual-sourcing templates.
- TCO and ROI calculators tailored to common enterprise use-cases (campus Wi‑Fi, large-scale camera deployments, smart lighting retrofits, and industrial edge controllers).
- Integration checklists and thermal/EMC design guidance for 802.3bt and higher-power designs, including recommendations on DC-DC conversion strategies and heat management to preserve device reliability.
- Regulatory and standards map aligning ENERGY STAR, IEEE evolutions, and national semiconductor policies with product compliance milestones.
- Commercial playbooks for channel partners, including bundling strategies, certification pathways, and ENERGY STAR positioning for midspan and switch-integrated PoE offerings.
Competitive Landscape — Who Matters and Why
The PoE chipset market is populated by a mix of broad-based semiconductor titans and targeted specialists. The competitive dynamic is shaped by the need for highly reliable power-management analog, embedded detection algorithms, and efficient DC-DC conversion at growing power levels. Key competitors analyzed in our report include:
- Texas Instruments Incorporated (Dallas, USA) — a long-standing supplier of PSE and PD controllers with proven series implementations that support the full suite of IEEE PoE standards. TI’s depth in analog power and system-level reference designs makes it a strategic option for customers prioritizing integration and ecosystem support.
- Analog Devices Inc. (Wilmington, USA) — offers integrated PSE/PD controllers including high-efficiency DC-DC capabilities and LTPoE++ support up to higher wattages. Their strength lies in tightly integrated analog front-ends and robust detection schemes suited to industrial and enterprise segments.
- Microchip Technology Inc. (Chandler, USA) — notable for end-to-end PoE solutions and recent product launches geared to intelligent multi-port PSE management and ENERGY STAR‑compliant midspan devices. Microchip’s combined silicon and software approach is attractive for OEMs seeking turnkey subsystems.
- STMicroelectronics N.V. (Geneva, Switzerland) — supplies system-in-package solutions for high-power PD implementations and mid-power controllers, with an emphasis on thermal efficiency and power density.
- onsemi (Scottsdale, USA), Silicon Labs (Austin, USA), Broadcom (San Jose, USA), NXP (Eindhoven), Monolithic Power Systems (Kirkland), Semtech (Camarillo), and Kinetic Technologies (San Jose) — each brings differentiated competencies, from highly cost-optimized PD controllers for IoT to enterprise-grade switching silicon that embeds PoE management. Broadcom’s recent announcements linking PoE functionality into AI-scale switching platforms are particularly noteworthy for large campus and data-center edge strategies.
Collectively, the top three firms account for a meaningful share of market value, while the top five concentrate well over half the market — a structural reality that shapes pricing leverage, roadmap influence, and certification requirements. PW Consulting’s vendor matrix scores these firms across 12 criteria including technical performance, roadmap clarity, supply resilience, and partner ecosystem depth.
Regulatory, Supply, and Technology Dynamics to Watch in 2026
- Standards evolution: IEEE 802.3bt (and higher-power extensions) has unlocked new applications by supporting higher wattage and Autoclass power reporting. Buyers must lock in standard compatibility now to avoid costly reworks later.
- Efficiency and thermal budgets: Advances in DC-DC conversion now routinely deliver efficiencies approaching industry-leading thresholds; however, thermal constraints remain the first-order design limiter for many PDs and compact PSEs.
- Component lead-time pressure: A broader semiconductor demand surge — amplified by AI and EV applications — pushed lead times for key analog and power components into multi-month ranges in early 2026. Design teams should plan for qualified alternates and prioritized allocation agreements.
- Geopolitical and policy drivers: National semiconductor strategies and shifting trade policies continue to reconfigure sourcing footprints. Regional diversification and local assembly options are now valid risk-mitigation levers for mission-critical deployments.
Actionable Recommendations for 2026
- Adopt a two-track sourcing model: Combine strategic long-term agreements with a spot-market contingency to reduce fill-rate risk while managing cost.
- Prioritize standards-compatible platforms: Invest in 802.3bt-compliant PSE/PD silicon for greenfield projects and ensure firmware upgradeability for evolving Autoclass and power reporting features.
- Embed thermal and efficiency KPIs in procurement: Specify conversion efficiency and thermal derating thresholds in RFPs to avoid downstream reliability costs.
- Model TCO over 5–7 years: Account for energy savings, reduced cabling and labor, and maintenance differentials when comparing PoE-enabled architectures to traditional power distribution.
- Monitor vendor roadmaps and concentration risk: Use PW Consulting’s vendor scorecard to identify partners with demonstrated supply robustness and product continuity commitments.
What PW Consulting’s Report Does Not Reveal Here
This preview purposefully surfaces the high-level market trajectory, competitive contours, and the operational levers that will matter in 2026. To preserve the strategic value of the proprietary analysis — including regional and application segmentation breakdowns, detailed vendor market shares, unit shipment forecasts, and downloadable procurement templates — full datasets and interactive models are available exclusively in the complete report.
Final Note: How to Use This Intelligence in 2026
For executives and product leaders making 2026 decisions, the imperative is clear: move from ad hoc PoE pilots to structured deployment strategies that align technical choices with commercial resilience. The PoE chipset market’s projected growth and concentration dynamics create both opportunity and risk — opportunity for vendors and integrators who can deliver reliable, efficient, and standards-compliant silicon; risk for buyers who delay sourcing and integration choices into 2027 and beyond.
PW Consulting’s full PoE Chipset Market report equips decision-makers with the data, vendor assessments, and playbooks necessary to operationalize this strategy. Use the preview insights above to prioritize immediate actions (sourcing, standards alignment, thermal design constraints) and consult the full report for the granular segmentation, scenario-specific ROI tools, and vendor scorecards that will dictate winners and losers through 2032.
For detailed analysis of this topic, please visit the official page: Power Over Ethernet Poe Chipset Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


