



PW Consulting: Medical Device Calibration Market Poised to Expand at a 9.25% CAGR During 2026–2032

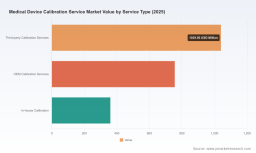
Medical Device Calibration Service Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s new market research brief on the Medical Device Calibration Service market synthesizes regulatory, operational, and competitive intelligence to inform capital allocation and go-to-market decisions in 2026. The market has transitioned from a niche technical service to a mission-critical component of clinical continuity and regulatory defensibility. Our analysis shows the market expanding from roughly USD 1.39 billion in 2020 to about USD 2.16 billion in 2025, and we forecast it to reach approximately USD 4.01 billion by 2032, reflecting a compound annual growth rate (CAGR) of 9.25% over the 2026–2032 forecast window. Market concentration remains low — the top three providers account for under one-fifth of revenue and the top five below one-third — underscoring fragmentation and opportunity for scale-driven consolidation.
Medical Device Calibration Service Market
Why this market matters for 2026 strategy
- Regulatory compliance is now a board-level exposure: Requirements such as ISO/IEC 17025 accreditation for laboratories, ISO 13485 for device quality systems, and FDA obligations (including 21 CFR Part 820.72 and programs like ASCA) are raising the technical bar for calibration evidence used in design, production and premarket submissions.
- Operational resilience and clinical uptime are monetized: Hospitals and OEMs treat calibration as a service that reduces clinical risk and prevents revenue losses from equipment downtime. This has created new pricing and contract models beyond time-and-materials.
- Technology integration is shifting value capture: Predictive maintenance, digital asset management, and remote calibration capabilities change the unit economics of service and create differentiation for providers who can combine field service with software and data analytics.
Market dynamics driving decisions in 2026
- Regulatory tightening and harmonization. Accreditation and traceability to national standards are now prerequisites for defensible measurement data in regulated submissions. The FDA’s ASCA pathway is enabling accredited labs to support premarket evidence, while 21 CFR Part 820.72 continues to obligate device manufacturers to maintain traceable calibration programs. These regulatory facts are shaping supplier selection criteria and elevating ISO/IEC 17025 as a de facto ticket-to-play.
- Infrastructure expansion in growth markets. Public and academic investments in national metrology and mobile calibration facilities are accelerating capacity in emerging geographies. New apex-level facilities and mobile labs expand market accessibility for hospitals and OEMs, reducing the logistical premium for reliable field calibration in regional markets.
- Service model evolution. Third-party providers, OEM service arms and internal hospital biomedical departments are reconfiguring their value propositions: bundled managed services, guaranteed uptime contracts, and asset-as-a-service offerings are displacing transactional calibration engagements.
- Fragmentation enables M&A and roll-up strategies. With a CR3 below 20% and CR5 under 30%, strategic acquirers can capture scale benefits through consolidation, regional coverage, and technical center-of-excellence plays. Recent bolt-on acquisitions and lab aggregations validate this thesis.
Competitive landscape — what the leaders are doing
The competitive set includes international calibration specialists, OEM service divisions, and regional biomedical service firms. Across this landscape we see three convergent plays:
Medical Device Calibration Service Market
- Scale and accreditation: Global providers are investing in ISO/IEC 17025-accredited laboratory networks and traceable measurement systems to win regulated customers and ASCA-eligible work.
- Coverage and speed: Regional roll-ups and acquisitions are being used to densify field-service footprints, shorten lead times, and support hospital networks with guaranteed response SLAs.
- Product-service integration: OEM-focused players leverage their product knowledge to offer prioritized service and lower mean-time-to-repair for their installed base, while independent providers emphasize multi-brand capability and impartiality.
Representative company positioning:
Medical Device Calibration Service Market
- Trescal (France): A full-service international calibration provider with ISO 17025 capabilities and a clear emphasis on traceability and regulatory compliance for life science and clinical equipment. Their multi-country lab-and-field model positions them to serve global OEMs and hospital systems seeking uniformity of practice.
- Transcat, Inc. (United States): Aggressively expanding through laboratory acquisitions to densify regional coverage for healthcare customers. Their recent lab roll-ups are consistent with a regional consolidation strategy that shortens response times and builds testing capacity adjacent to OEM and hospital clusters.
- Tektronix and Fluke Biomedical (United States): Both blend instrumentation expertise with service. Their strength is in multi-brand calibration and the ability to couple test instruments with accredited workflows — attractive for facilities that demand technical rigor and minimal clinical disruption.
- Specialist regional players (e.g., JM Test Systems, Calyx Met, Biomedical Technologies Inc. and others): These providers deliver focused capabilities — from diagnostic imaging calibration to on-site biomedical support — and often compete on accredited traceability and personalized service for hospitals and labs.
Recent developments that recalibrate 2026 plans
- Laboratory acquisitions and roll-ups continue to accelerate — exemplified by multi-site acquisitions in mature markets to build regional test capacity and field networks.
- Public investments in calibration infrastructure and mobile labs in markets such as India expand addressable demand and lower the cost of entry for regulated testing and field service.
- Strategic acquisitions of calibration boutiques by larger service providers and equipment service companies indicate a shift from ad-hoc engagements to packaged compliance solutions.
What PW Consulting’s report delivers — practical assets for 2026 action
This is not an academic exercise. Our report provides tools that operational and commercial leaders can use immediately:
- Go-to-market playbooks tailored for OEMs, third-party service providers and hospital systems, including contract language templates for uptime guarantees, sample SLAs, and escalation paths.
- Regulatory compliance checklists and accreditation roadmaps that map ISO/IEC 17025 and ISO 13485 obligations into discrete operational tasks and audit evidence packages.
- Financial models—CapEx/Opex breakouts, ROI scenarios for insourcing vs. outsourcing, and valuation heuristics for M&A target screening.
- Service portfolio optimization frameworks to prioritize high-impact device classes and clinical use-cases (note: granular device and regional splits are intentionally omitted here — full segmentation available in the paid dataset).
- Operational playbooks for field-force structuring, calibration interval optimization, asset tagging and digital integration strategies for CMMS and predictive analytics.
- Vendor scorecards and due-diligence templates, including accreditation, traceability, SLA performance, and sample audit questionnaires for procurement teams.
Strategic recommendations for 2026 decision cycles
- For OEMs: Convert calibration from a compliance checkbox into a differentiator — bundle accredited calibration services into extended warranty and service contracts to capture recurring revenue and reduce aftermarket leakage.
- For service providers: Prioritize investments in accreditation, digital asset management and regional lab capacity. Pursue bolt-on acquisitions to close coverage gaps and capture scale-sensitive accounts.
- For hospitals and health systems: Reassess the economics of centralized biomedical shops versus accredited third-party partnerships, with particular focus on workload seasonality, regulatory evidence needs, and supply-chain resilience.
- For investors and PE sponsors: Seek platform plays that combine accredited labs, field-service networks, and software-enabled asset-management capabilities; target subsegments where clinical criticality supports premium pricing and contracted recurring revenue.
Data rigor and methodological notes
PW Consulting’s estimates are built on a bottom-up inventory of device populations, calibration frequency benchmarks, accreditation prevalence and service pricing norms, reconciled with provider revenue disclosures and recent M&A activity. The base year is 2025; the forecast period spans 2026–2032 using a 9.25% CAGR assumption. We also quantify market concentration and competitive positioning to support M&A diligence — note that high-granularity regional and device-level splits are part of the paid dataset and are intentionally not reproduced in this preview.
How to use this research in 2026 planning
- Prioritize compliance-sensitive product lines for service bundling and ASCA-ready testing partnerships.
- Run a rapid triage of your calibration footprint against the accreditation map in the report to identify single points of failure in regulatory evidence.
- Use the vendor scorecards to streamline RFPs and shorten procurement cycles by focusing on accreditation, turnaround, and digital integration capabilities.
- Leverage the financial playbooks to model buy-versus-build decisions for both labs and software components of a modern calibration service.
Conclusion — a tactical edge for 2026
Calibration is no longer a back-office technical function: it is a convergence point for regulatory risk management, clinical uptime, and service monetization. With the market expanding at a double-digit growth trajectory into the early 2030s and a fragmented supplier base, organizations that invest selectively in accreditation, regional capacity, and digital integration will capture outsized share and margin. PW Consulting’s full report equips executives with the pathway to convert calibration from cost center to strategic asset.
Next steps
For the full dataset, regional and device-level segmentation, vendor benchmarking matrices, and downloadable operational templates referenced here, consult the PW Consulting report landing page. This release intentionally omits detailed split-values to safeguard the strategic granularity contained in the paid report — an approach designed to protect actionable intelligence and maximize utility for subscribing clients.
For detailed analysis of this topic, please visit the official page: Medical Device Calibration Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


