



PW Consulting Forecast: Retail Omni‑Channel Commerce Platform Market Set to Grow at a Robust 18.5% CAGR During 2026–2032

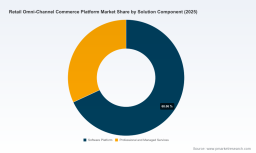
Retail Omni‑Channel Commerce Platform Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As retailers move from tactical channel experiments to programmatic omni‑channel transformation, boardrooms and IT leadership confront a complex decision set in 2026: which platform architecture, deployment model, and partner ecosystem will deliver profitable growth while remaining resilient to rising infrastructure costs and tightening privacy regimes? PW Consulting’s latest Retail Omni‑Channel Commerce Platform Market report (base year 2025) answers that question with an operationally focused roadmap grounded in robust market sizing and scenario analysis. The headline: the market is expanding rapidly — growing at a compound annual growth rate (CAGR) of 18.5% and moving from a mid‑double‑digit billion USD scale in 2025 into the mid‑tens of billions by the end of the forecast horizon — underscoring the urgency for strategic platform decisions this year.
Retail Omni Channel Commerce Platform Market
Why this report matters for 2026 decision‑making
-
Acceleration, not disruption: Investments in unified commerce are maturing from pilot initiatives into enterprise programs. With strong market momentum projected through the forecast period, retailers and brands must shift from vendor evaluation to program governance, vendor orchestration, and measurable operational KPIs.
Retail Omni Channel Commerce Platform Market -
Infrastructure and cost pressure: Cloud adoption and higher performance expectations are driving significant demand in adjacent infrastructure markets. Global data center dynamics and rising construction and colocation costs are increasing the operating baseline for cloud‑native omni‑channel deployments — a factor that materially affects TCO and sourcing choices.
Retail Omni Channel Commerce Platform Market -
Regulatory and data sovereignty friction: A widening patchwork of privacy laws and cross‑border controls (including new U.S. state statutes and heightened international scrutiny) is constraining unified customer data architectures. These constraints turn what was once a technical integration problem into a strategic architecture tradeoff with commercialization consequences.
What the report contains — practical, executable content
-
Concise market sizing and forward scenarios: a defensible macro baseline for 2025 and modeled pathways through the forecast period, enabling spend planning and addressable‑market calculations for platform investments.
-
Vendor evaluation framework: a weighted, procurement‑ready scorecard that balances functional fit (order management, POS, inventory synchronization, composability), non‑functional requirements (scalability, uptime SLAs, data residency), and commercial levers (license models, professional services, ecosystem support).
-
Architecture playbooks: practical blueprints for monolith‑to‑composable migration, headless storefront implementations, hybrid cloud/on‑prem orchestration, and secure customer data fabrics that respect emerging privacy constraints.
-
TCO and runbook models: configurable templates to estimate total cost across CapEx and OpEx, including sensitivity to data center pricing, cloud egress, and managed service premiums.
-
RFP and vendor negotiation playbooks: ready‑to‑use questions, red flags, and pricing negotiation levers tailored for enterprise omnichannel procurements.
-
Operational metrics and adoption roadmaps: recommended KPI ladders (conversion, fulfillment cost per order, inventory days of supply, associate productivity), phased rollouts, and pilot success criteria to de‑risk large‑scale deployments.
-
Compliance checklists: mapped requirements against recent privacy laws and cross‑border restrictions, with prescriptive mitigations for data minimization, consent orchestration, and recordkeeping.
Competitive landscape: who matters and why
The vendor landscape is populated by cloud‑native newcomers and incumbent enterprise suites. Our analysis highlights strategic differentiation factors that matter most to enterprise buyers in 2026.
-
Shopify Inc. — strong momentum for rapid DTC and headless scenarios via its enterprise Shopify Plus and Hydrogen/Oxygen offerings. Ideal for brands seeking a fast, developer-friendly path to unified online‑to‑offline experiences, particularly where speed to market and ecosystem integrations are prioritized.
-
Salesforce, Inc. — Commerce Cloud’s strength is its deep CRM and marketing ecosystem, with AI personalization capabilities that appeal to retailers prioritizing customer lifecycle orchestration and cross‑cloud data unification.
-
Adobe Inc. — positions itself as the Experience‑first commerce provider, combining flexible commerce engines with content and personalization tooling for experience‑driven retailers focusing on conversion uplift through content.
-
Oracle & SAP — both remain the pragmatic choice for very large retailers seeking proven scale in inventory optimization, POS, and backend process unification; selection typically follows enterprise ERP and supply chain considerations.
-
BigCommerce, VTEX, Lightspeed, NCR — offer differentiated strengths across DTC, marketplace, mid‑market to specialty retail, and POS integration. These vendors often appeal to retailers seeking specific channel or regional focus with faster implementations.
-
Composable and MACH specialists (commercetools, Elastic Path, Hygraph) — provide the modularity and API‑first design buyers need for complex, multi‑market architectures; they are increasingly the tactical choice for retailers prioritizing future agility over out‑of‑the‑box functionality.
-
Supply chain and order management players (Manhattan Associates, Infor) — differentiate on fulfillment, OMS, and store‑level execution — critical when cost‑to‑serve and fulfillment SLAs determine profitability of omnichannel channels.
-
Enterprise integrators (IBM, Microsoft Dynamics) — offer platform breadth and enterprise support, particularly attractive to organizations where commerce is embedded into broader ERP, CRM, and data estates.
Recent industry moves illustrate accelerating ecosystem consolidation and interoperability: native integrations for multi‑region commerce platforms, expanded channel feed partnerships, and headless integration tool updates have all appeared in the opening months of 2026. These developments reduce point‑integration friction but also increase the number of viable pairing permutations buyers must evaluate.
Strategic recommendations for 2026 programs
-
Make data architecture a board‑level decision: Privacy laws and data sovereignty rules mean you cannot treat customer data as a fungible IT artifact. Define permitted flows, residency constraints, and a minimal data model before vendor selection.
-
Adopt a ‘composable first’ procurement stance if you face multi‑market or rapid SKU growth: Composability increases option value for future channels and marketplaces, even if the first‑wave implementation appears more costly on day one.
-
Model TCO against infrastructure scenarios: Incorporate rising data center and colocation costs into multi‑year TCO sensitivity; validate cloud pricing assumptions against realistic throughput and storage growth trajectories.
-
Operationalize AI with guardrails: Automation for picks, price optimization, and associate assist can deliver step changes in efficiency, but must be integrated with privacy and consent policies to avoid regulatory friction.
-
Design for phased modernization: Use pilot stores or geographies to validate OMS, inventory orchestration, and returns handling before full‑scale cutovers. Preserve rollback paths and vendor escape clauses to limit vendor lock‑in.
-
Prioritize partner ecosystems and managed services: In higher‑cost cloud and regulated environments, managed services and local delivery partners can control run costs and accelerate compliance implementation.
How to use the report
Consider this market brief your strategic trailer: it outlines the stakes, shows the playbook, and presents the practical tools procurement, IT, and commercial teams need to make defensible choices in 2026. The full report contains the segment‑level analysis, vendor scoring matrices, downloadable templates, and a decision support workbook that operationalizes the recommendations above. We intentionally withheld detailed segment allocations and granular vendor rankings from this public brief to preserve the integrity of our proprietary benchmarking and to provide a single destination for complete, download‑ready insights.
If your organization is planning a commerce platform procurement, migration, or a governance overhaul this year, the report will compress months of work into a structured program with measurable milestones and financial guardrails — enabling you to move from vendor‑centric conversations to outcome‑driven decisions.
Closing
The omni‑channel commerce market in 2026 presents both an opportunity and an execution challenge: rapid market expansion and platform innovation create a favorable investment backdrop, while infrastructure costs and evolving regulation raise the bar for disciplined architecture and governance. PW Consulting’s Retail Omni‑Channel Commerce Platform Market report equips leaders with the market perspective, vendor intelligence, and practical playbooks needed to turn platform investments into sustainable commercial advantage. For access to the complete analysis, segment detail, and execution templates, please visit PW Consulting’s research portal to download the full report and supporting assets.
For detailed analysis of this topic, please visit the official page: Retail Omni Channel Commerce Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


