



PW Consulting Forecast: Ablation Systems Market Set to Grow at a 9.25% CAGR Through 2032

Ablation Systems Market Outlook 2026: Strategic Imperatives for Decision‑Makers
Executive Snapshot
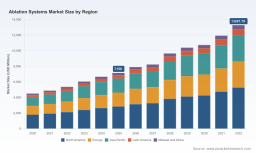
PW Consulting’s Ablation Systems Market Research (base year 2025; historical 2020–2025; forecast 2026–2032) positions the global ablation market as a high‑growth, innovation‑led opportunity for device manufacturers, hospital systems, private equity investors, and reimbursement stakeholders. Our proprietary model estimates the market at USD 7,150 Million in 2025, rising to a projected USD 7,901 Million in 2026 and reaching more than USD 13,280 Million by 2032 — a compound annual growth rate (CAGR) of 9.25% across the forecast window. Market concentration is meaningful but far from monopolistic: the top three vendors account for roughly 42% of market value while the top five control approximately 58% — an environment that rewards both scale and focused differentiation.
Ablation Systems Market Research
Key Takeaways for 2026 Strategy
- Scale and specialization are simultaneous advantages: incumbents with broad electrophysiology and surgical portfolios retain negotiating power, but nimble entrants that own a clinical niche can secure premium reimbursement and access pathways.
- Regulatory progress in 2024–2026 has accelerated adoption of next‑generation energy modalities (including pulsed field and cryo innovations), compressing time‑to‑value for first movers and raising the bar for clinical evidence.
- Reimbursement and inpatient payment rule changes are already reshaping hospital economic calculus for combined procedures; commercial and public payers will be decisive gatekeepers in 2026 procurement cycles.
- Clinical workflow integration — mapping systems, robotics, and ablation platforms — is emerging as a decisive procurement criterion beyond unit price.
Market Trajectory: What the Numbers Imply (without the spoilers)
PW Consulting’s granular forecasting demonstrates a clear, sustained expansion of total addressable spend through 2032 driven by: rising incidence and diagnosis of arrhythmia and tumor indications; broader clinical acceptance of novel energy sources; and the diffusion of minimally invasive approaches into older, higher‑risk patient cohorts. The aggregate figures above encapsulate both volume growth and ASP (average selling price) dynamics. While we do not disclose segment‑level dollar breakdowns in this release, our modeling explicitly reconciles historical sales patterns (2020–2025) with clinical adoption curves to produce the 9.25% CAGR. This is not a steady single‑line expansion — the forecast embeds discrete inflection points tied to regulatory clears, reimbursement updates, and landmark clinical readouts that will materially affect adoption timing in 2026–2028.
Ablation Systems Market Research
Strategic Implications for Corporate and Investor Decision‑Making in 2026
- R&D Prioritization: Align near‑term investment toward technologies that facilitate systems integration (mapping + ablation + imaging) and reduce procedure time and complications. Our scenario modelling shows these attributes disproportionately improve hospital uptake and payer acceptance.
- M&A and Partnership Playbook: With CR5 at ~58%, acquisitive expansion remains a fast track to scale. However, targeted tuck‑ins that add differentiated technology (e.g., PFA, focal cryo, robotics) or access to specific clinical channels (oncology, urology, women’s health) can deliver multiple‑year revenue acceleration without competing head‑on with incumbents.
- Commercial Strategy: Prioritize evidence generation that maps directly to reimbursement levers. Value dossiers that quantify reduced length of stay, adjunct procedure consolidation, and downstream cost avoidance are the strongest determinants of hospital purchasing decisions under recent MS‑DRG updates.
- Market Access: Anticipate and influence payer policy. Providers and device developers that proactively sponsor health‑economics analyses and early‑stage registry data will face fewer access barriers when national or local coverage determinations are revisited.
Competitive Landscape — Who Matters and Why
The ablation space is occupied by a mix of diversified medtech leaders and focused specialists. Each cohort plays a distinct role in shaping 2026 dynamics:
Ablation Systems Market Research
- Large integrated players (examples include Medtronic, Boston Scientific, Abbott, Johnson & Johnson MedTech/Biosense Webster): leverage cross‑portfolio capabilities — mapping systems, catheters, and energy platforms — to offer bundled value propositions. Their competitive edge lies in installed base, capital equipment channels, and ability to fund large randomized or registry studies that de‑risk payer adoption.
- Surgical and niche specialists (examples include AtriCure, AngioDynamics, IceCure): retain leadership where procedural workflow and clinical specialty focus (e.g., surgical AF ablation, IRE for oncology, cryo for localized breast lesions) matter most. These companies can command premium pricing for clearly differentiated clinical outcomes and less crowded reimbursement pathways.
- Technology innovators and robotics (examples include Stereotaxis, Kardium, EDAP TMS): drive new procedural models — robotics, magnetic navigation, HIFU — that target subsegments where conventional approaches are limited or risky. Regulatory milestones for these technologies are high impact catalysts for adoption.
- Adjacents and procedural consumable suppliers (examples include Olympus, CONMED, Merit, Terumo): benefit from distribution breadth and procedure cross‑sell across GI, urology and surgical suites; their role is often to enable adoption of ablation through existing clinician relationships.
Recent corporate events underscore competitive momentum. Notable regulatory wins in late 2024–2026 — including approvals and clearances for dual‑energy systems, pulsed field platforms, cryo devices, robotic ablation catheters, and transurethral thermal systems — have already shifted competitive advantages. PW Consulting’s profiles assess each company across clinical pipeline strength, commercial footprint, manufacturing scale, and evidence strategy; the full report quantifies these dimensions into investment‑grade vendor scorecards that purchasers and investors use to prioritize targets.
Regulatory and Reimbursement Dynamics: The Practical Impact
Regulatory clearances in 2024–2026 have been pivotal. Examples include approvals for dual‑energy and pulsed field platforms and FDA marketing authorization for targeted cryoablation in defined oncology populations. On the reimbursement front, CMS and IPPS updates (including a new concomitant MS‑DRG for left atrial appendage closure and ablation procedures, and FY2026 inpatient payment adjustments) materially alter hospital budgeting and procedure mix decisions.
- What this means for manufacturers: regulatory wins now require parallel payer strategies. A cleared device without a mapped economic case may remain underutilized.
- What this means for hospitals: when inpatient payment policy favors combined procedures, systems capable of delivering consolidated, single‑session care gain operational priority.
- Clinical adoption inflection points: Our sequencing analysis links specific regulatory events to adoption milestones; device developers should plan evidence generation and supply chain scale‑up to coincide with these windows.
What the PW Consulting Report Delivers (Practical, Actionable Content)
- Proprietary market model (USD Million) covering 2020–2032 with scenario toggles for adoption speed, ASP sensitivity, and technology substitution — delivered in Excel for direct integration into corporate planning.
- Vendor competitive scorecards combining clinical pipeline, commercial reach, manufacturing capacity, and M&A appetite — with acquisition probability bands for 2026–2028.
- Go‑to‑market playbooks tailored to four buyer archetypes (large academic centers, regional hospitals, ambulatory surgical sites, and oncology networks) including pricing strategies and clinical champion engagement templates.
- Regulatory and reimbursement tracker with recommended payer engagement timelines keyed to product launch milestones.
- Clinical evidence compendium and recommended study designs (real‑world registries, pragmatic randomized trials, health‑economic models) that align with the thresholds payers currently require.
- M&A heat maps and due diligence checklists that integrate clinical, regulatory, manufacturing, and commercial risk signals.
To preserve the utility of the research for commercial partners and licensees, this release intentionally omits granular segment dollar tables and regional/application percentage splits — those critical inputs are included in the licensed report and the downloadable dataset.
How Strategic Buyers and Hospital Systems Should Use the Report in 2026
- Capital Planning: Use our forecast scenarios to time capital investments in mapping and ablation suites so that procurement coincides with payer coverage windows.
- Vendor Negotiations: Leverage our vendor scorecards to structure multi‑year contracts with performance and access guarantees tied to clinical outcomes.
- Clinical Pathway Design: Adopt the report’s evidence templates to close gaps between regulatory clearance and reimbursement acceptance, reducing lag time to routine use.
- Investor Due Diligence: Use the M&A heat maps and sensitivity analyses to calibrate valuations and integration risk for targets in PFA, cryo, HIFU, and robotics.
Conclusion — Why 2026 Is a Pivotal Year
2026 represents an inflection point where regulatory approvals, payer policy updates, and accumulated clinical evidence converge to accelerate market growth. With a forecast that more than doubles market value from 2025 levels by 2032 under our central scenario, the commercial and clinical stakes are high. PW Consulting’s Ablation Systems Market Research provides the practical analytics, scenario tools, and go‑to‑market playbooks that senior executives and investors need to convert regulatory wins into durable market share and superior returns — while avoiding the common pitfalls of timing, reimbursement misalignment, and under‑capitalized scaleups.
Next Steps
For decision‑grade access to the full dataset (including the detailed segmentation tables, regional and application breakdowns, vendor scorecards, and the downloadable financial model), consult the PW Consulting report page. The full deliverable is calibrated for use in 2026 budgeting cycles and strategic reviews.
For detailed analysis of this topic, please visit the official page: Ablation Systems Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


