



PW Consulting: Gas Pressure Regulators Market to Rise from USD 3,755.2 Million in 2025 to USD 5,326.37 Million by 2032 at a 5.12% CAGR

Gas Pressure Regulators for Oil & Gas Market — Strategic Briefing from PW Consulting
PW Consulting’s new market research brief on Gas Pressure Regulators for the Oil & Gas sector is released to inform and equip executive teams making critical 2026 strategic decisions. The study synthesizes historical performance (2020–2025), near-term sizing, and an actionable forecast (2026–2032) to translate technical product dynamics into clear commercial choices. Readers will find a concise, commercially focused roadmap: where to invest, who to partner with, and which regulatory and supply risks to hedge — while the granular segmentation matrices and downloadable decision tools are reserved for the full report.
Gas Pressure Regulators For Oil Gas Market
Executive snapshot: growth, scale and competitive shape
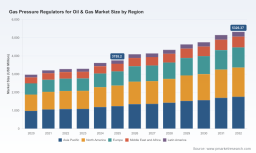
Our baseline analysis shows the market for gas pressure regulators serving oil and gas applications expanded from USD 2,967.07 Million in 2020 to USD 3,755.2 Million in 2025. We forecast the market to reach USD 4,092.34 Million in 2026, and project a compound annual growth rate (CAGR) of 5.12% across the 2026–2032 forecast window. These topline trends underscore a steady, technology-driven demand profile that rewards supplier reliability, product differentiation for harsh-service environments, and integrated digital capabilities.
Gas Pressure Regulators For Oil Gas Market
Market concentration is moderate. The top three suppliers account for roughly 28% of revenue, and the top five for approximately 42%. That structure creates meaningful opportunity for focused consolidation, targeted partnerships, and regional specialization strategies — especially for mid-sized suppliers and new entrants with niche technical strengths.
Gas Pressure Regulators For Oil Gas Market
Why this report matters for 2026 decision cycles
- Capital allocation and portfolio prioritization: Operators and OEMs can quantify where to direct CapEx for pipeline upgrades, distribution modernization, and substitution toward hydrogen/blend‑capable designs.
- Procurement and supplier strategy: The research converts product-level risk (material, testing and certification lead times) into contracting levers managers can use to reduce total cost of ownership.
- R&D and product roadmaps: Insights on performance drivers — noise reduction, no-bleed designs, pilot vs. self-operated trade-offs, and digital monitoring — help product teams prioritize features that unlock premium pricing.
- M&A and partnership screening: Buyers and corporate development teams get a short list of high-leverage niches (e.g., high‑pressure subsea, hydrogen‑compatible valves) where bolt-on deals or JV models accelerate entry.
Key trends shaping demand and supplier economics
- Energy transition and fuel mix evolution: Near-term demand remains anchored to natural gas transmission and distribution, but design requirements are shifting. Regulators must increasingly demonstrate compatibility with hydrogen blends, biogas, and tight emission targets — a technical premium that separates commodity from strategic suppliers.
- Material and supply chain pressure: Stainless steel (notably 316-grade) remains the dominant material choice for corrosion and sour-service resistance. Volatility in metal supply and regional price divergence are persistent margin levers; procurement teams must model multi‑sourcing and inventory buffers.
- Regulatory and standards landscape: Compliance regimes such as IOGP guidance for pressure regulators, NACE MR0175/ISO 15156 for sour-service alloys, and ISO 23555-2 for transmission/distribution regulators are now integral to product certification. Manufacturers without aligned conformity assessment processes face longer qualification cycles and restricted market access.
- Digitalization and aftermarket services: Remote-monitoring features, predictive maintenance algorithms, and integrated safety controls are becoming differentiators. Suppliers that bundle hardware with analytics-enabled service contracts capture aftermarket revenue and reduce customer switching.
- Harsh-environment and subsea demand: Exhibitions in 2025–2026 confirmed rising interest in high-pressure and subsea-capable regulators. Recent industry showcases (ADIPEC 2025 and OTC 2026) highlighted advances in materials, control architectures, and testing methods tailored to these use cases.
What the PW Consulting report delivers (practical, deployable content)
- Independent market sizing and a transparent forecast model (2026–2032) expressed in USD Million, with scenario toggles for slower/faster energy transition pathways.
- Segmentation by type, application and region with anonymized demand profiles to avoid disclosure of customer‑level sensitivities while preserving directionally accurate decision inputs.
- Supplier benchmarking and product feature matrices that map technical capabilities (e.g., pilot vs self‑operated trade-offs, noise-reduction technologies, no-bleed designs) to commercial outcomes.
- Supply chain and raw material risk maps plus recommended procurement mitigations and inventory strategies tailored to 2026 lead times.
- Regulatory compliance checklist and implementation roadmaps for IOGP, NACE/ISO sour-service requirements and ISO pressure regulator standards.
- Practical tools: TCO templates, RFP question banks for technical procurement, and a M&A screening scorecard focusing on technology fit, certification status, and aftermarket potential.
- Use-case playbooks for operators, OEMs and EPC contractors covering distribution upgrades, city-gate modernization, subsea transmission and hydrogen pilot projects.
Competitive landscape — who matters and why
The sector is populated by global incumbents, specialist engineering houses, and regional manufacturers. A concise read on core players covered in the study:
- Emerson (Fisher/TESCOM/Tartarini) — Strengths: broad product portfolio including noise reduction and no-bleed designs, deep service networks and strong safety credentials. Best positioned where regulatory compliance and reliability are non-negotiable.
- Swagelok Company — Strengths: precision control across diverse flow rates, rigorous testing and corrosion-resistant materials. Competitive where high-purity, instrumentation-grade control is required.
- Honeywell — Strengths: systems integration and smart monitoring capabilities; offers pressure regulators coupled with electronic control and safety accessories. Attractive to customers moving toward integrated automation stacks.
- BelGAS (Marsh Bellofram) — Strengths: long-standing product lines for natural gas and propane regulators; strong in legacy distribution applications and farm tap solutions.
- Pietro Fiorentini / FIORENTINI USA — Strengths: focused expertise in metering and pressure regulation across transmission and distribution; differentiated by localized service and system-level solutions.
- Pressure Tech Ltd — Strengths: specialized high-pressure and subsea models; competitive in hydrogen, diving and niche industrial applications where bespoke design is required.
- Cavagna Group, RegO, Maxitrol — Strengths: breadth in LPG, natural gas and industrial applications; often compete on cost, logistics and aftermarket distribution strength.
Our benchmarking section ranks these suppliers not only by product features and global reach but also by certification readiness, lead-time resilience and aftermarket service depth — criteria that matter most in procurement decisions for 2026 deployments.
Strategic implications and recommended actions for 2026
- Prioritize certification and sour-service readiness: Ensure design and procurement teams require conformity evidence to IOGP, NACE/ISO, and relevant ISO regulator standards as pre-qualification. This avoids costly re-tests and market entry delays.
- De-risk material and supplier exposure: Build dual-sourcing strategies for critical stainless-steel components and qualify alternate alloys or coatings for sour-service where appropriate.
- Invest in digital enablement: Pilot smart monitoring retrofits on critical regulator fleets to reduce unplanned outages and capture aftermarket service revenues through subscription models.
- Run hydrogen readiness pilots: Begin targeted pilots for hydrogen-blend compatibility in controlled distribution corridors; capture learnings to inform product roadmap and customer propositions.
- Use M&A selectively: Pursue bolt-ons that add hydrogen-compatible design IP, subsea experience, or established service networks rather than broad horizontal consolidation.
- Short-cycle procurement playbook: Implement staged contracting — award parts supply to multiple qualified vendors, then consolidate to a primary supplier as performance and certification are proven in 12–18 months.
How to act and where to get the full dataset
This briefing is a strategic trailer: it lays out the evidence-based actions procurement, product and strategy teams should take in 2026. The full PW Consulting report contains the granular segmentation, downloadable forecasting models, supplier scorecards with anonymized financials, and the tactical procurement templates referenced above. Access to those deliverables will materially shorten your decision cycle and reduce execution risk.
For a tailored executive briefing, scenario walk-throughs using your fleet data, or a confidential vendor pre-qualification workshop, PW Consulting’s energy practice is available to advise and to operationalize the report’s tools into procurement tenders, R&D prioritization and M&A diligence.
PW Consulting — converting technical complexity in gas pressure regulation into executable commercial advantage for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Gas Pressure Regulators For Oil Gas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


