



PW Consulting: Antirusting (Anti‑Rust) Agents Market Poised for 5.28% CAGR, New Insights Reveal

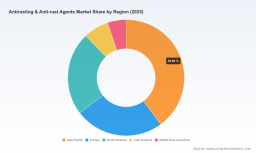
Antirusting Anti Rust Agents Market — 2026 Strategic Outlook from PW Consulting
PW Consulting’s latest market research brief on Antirusting Anti Rust Agents provides a focused, decision-grade vantage point for corporate leaders planning for 2026. The global market reached an estimated USD 5,460 million in 2025 and is modeled to expand at a compound annual growth rate (CAGR) of 5.28% over the 2026–2032 forecast window, approaching roughly USD 7,827 million by 2032. This release articulates the implications of that trajectory for procurement, product strategy, regulatory compliance and M&A, while preserving the detailed segment-level revenue matrices for subscribers and clients who require full, auditable datasets.
Antirusting Anti Rust Agents Market
Why this report matters for 2026 decision-makers
2026 will be a pivotal year for companies operating in corrosion protection and related chemistries. Macro growth is steady but nuanced: durable industrial demand continues to underpin the market while regulatory and raw-material pressures reshape cost, composition and go-to-market calculus. Executives need a roadmap that translates top-line growth into product roadmaps, supply-chain hedges and disciplined inorganic-growth screening. PW Consulting’s report converts raw market sizing into operational playbooks — enabling procurement teams to stress-test supplier contracts, enabling R&D leaders to prioritize low-risk formulations, and enabling strategy teams to pinpoint consolidation targets that improve scale in critical subsegments.
Antirusting Anti Rust Agents Market
Key takeaways (select highlights)
-
Measured, resilient growth: The market’s projected mid-single-digit CAGR reflects a blend of replacement and new-build demand across heavy industry, transportation and infrastructure. Growth is broad-based rather than concentrated in a single cyclical segment.
Antirusting Anti Rust Agents Market -
Moderate concentration, active opportunity set: The market exhibits modest concentration at the top — a meaningful number of specialist players coexist with large chemical multinationals. That structure creates attractive opportunities for targeted consolidation and technology partnerships to capture scale benefits.
-
Formulation shift and sustainability premium: Demand is migrating toward lower-VOC and water-compatible chemistries, accelerated by customer sustainability mandates and region-specific regulations. Vapor phase inhibitors and silane-based pretreatments are gaining traction as complementary approaches, particularly where hazardous-substance restrictions apply.
-
Regulatory and disclosure headwinds: Evolving EU and U.S. rules on certain phosphate uses and PFAS disclosure are already shaping product roadmaps and supplier qualification processes. Proactive compliance and substitution strategies are therefore essential to avoid business disruption.
-
Input-cost sensitivity is real: Oil-linked feedstocks and key amines have shown price volatility; firms without robust raw-material hedging or formulation flexibility risk margin erosion in short cycles.
Competitive landscape: how the leaders are positioning
The Antirusting Anti Rust Agents market blends global chemical majors with specialty-house innovators. Our report profiles the strategic posture of the principal players and synthesizes capability gaps that are meaningful to acquirers, joint-venture partners and procurement teams.
-
BASF SE (Ludwigshafen, Germany) — Leveraging broad industrial coatings and additive expertise, BASF’s inhibitor platforms are integrated into larger process-chemicals portfolios. Their scale allows cross-selling into adjacent feedstocks and pretreatment chemistries.
-
Henkel AG & Co. KGaA (Düsseldorf, Germany) — Henkel is actively expanding low-VOC rust preventive offerings and demonstrated this at industry shows with an emphasis on manufacturing line compatibility and environmental compliance.
-
Akzo Nobel N.V. (Amsterdam, Netherlands) — Akzo’s strength is in surface coatings and primers; anti-corrosive agents are folded into comprehensive protective systems for marine and heavy-industry customers.
-
The Lubrizol Corporation (Wickliffe, Ohio, USA) — A key developer of additives and industrial lubricant inhibitors, Lubrizol focuses on performance chemistries tailored to metalworking fluids and high-temperature applications.
-
Clariant AG (Muttenz, Switzerland) — Clariant’s synthetic and oil-based rust-preventive lines target machining and storage markets where long-term film properties matter.
-
Cortec Corporation (St. Paul, Minnesota, USA) — A specialty house for VpCI (Vapor phase Corrosion Inhibitor) technologies, Cortec is notable for packaging and storage protection innovations and recent water-based product introductions.
-
Quaker Houghton (Conshohocken, Pennsylvania, USA) — Integrating rust preventives into process fluids is a differentiator for Quaker Houghton; recent certification updates bolster their environmental and operational credentials.
-
Other specialist players — Regional and niche-focused companies (e.g., McGean, Daubert Chemical, Petrofer, Evonik, Lanxess) offer differentiated chemistries and channel relationships that are attractive targets for buyers seeking product-line extension or regional scale.
Our competitive analysis synthesizes R&D pipelines, manufacturing footprint risk, patent positions, and commercial go-to-market models. We score each firm on technical depth, regulatory readiness and M&A fit — an approach that speeds target shortlisting in active processes.
Market dynamics and downside scenarios
-
Raw-material pressure: Brent crude movements and feedstock pricing materially influence margins for oil-soluble inhibitors; key intermediates such as amines have shown volatile spot-price behavior.
-
Regulatory tightening: Restrictions under regional chemical regulations and new disclosure rules for fluorinated substances create reformulation risk and potential phase-outs for legacy products.
-
Trade policy and tariffs: Trade actions that impose duties on specific organic chemicals can increase landed costs for formulators who depend on cross-border raw-material sourcing.
-
Substitution and digitalization: Advances in coating technologies, combined with more stringent asset-maintenance analytics, are changing where and how rust protection is applied — shifting some value from consumables to system-level solutions.
To help clients stress-test exposure, our report includes scenario models that combine input-cost shocks, regulatory timelines and end-market demand cycles. These allow CFOs and strategy teams to quantify margin and cash-flow impacts under plausible 12–36 month disruptions.
What the report delivers: practical, operational tools
Beyond narrative insight, PW Consulting’s deliverables are explicitly built for action. The package includes:
-
Transparent market-sizing methodology and growth drivers, with audited historicals and three forecast scenarios (conservative, base, upside).
-
Supplier and technology heat maps highlighting manufacturing location risk, formulation exclusivities and patent cliffs.
-
Regulatory-compliance matrix tying regional rules to formulation implications and time-to-substitute estimates.
-
Raw-material sensitivity analysis and hedging playbooks that translate commodity moves into unit-margin impacts.
-
Go-to-market frameworks for product segmentation, pricing archetypes and channel optimization for B2B buyers.
-
M&A target-scoring templates and integration risk checklists designed for private-equity sponsors and corporate development teams.
-
Commercial diligence appendices: customer interview summaries, procurement scorecards and sample RFP language for supply contracts.
How executives should use this intelligence in 2026
-
Procurement leaders — Use the raw-material sensitivity and supplier heat maps to renegotiate contracts, diversify feedstock sources, and implement tiered pricing triggers tied to commodity indices.
-
Product and R&D heads — Prioritize low-VOC and water-compatible formulations where market pull and regulatory timelines overlap; accelerate bench-to-commercial timelines for silane- and VpCI-based options in priority verticals.
-
Strategy and corporate development — Apply our M&A scoring to shortlist targets that add complementary chemistries or regional footprint; use the integration checklists to quantify synergy capture prospects.
-
Compliance and sustainability teams — Align reformulation roadmaps with anticipated REACH and U.S. reporting requirements; proactively engage customers with transition guidance to protect long-term revenues.
About the withheld detail — why a deeper download is essential
In keeping with a “trailer” approach, this release surfaces the analytic architecture and executive implications but intentionally omits the granular segment-by-region revenue tables and the detailed application-level breakdowns that many commercial decisions require. The report contains those datasets, including downloadable spreadsheets, audited supplier lists, and deal-ready valuation comparables. For teams evaluating procurement contracts, bidding on supply agreements, or pursuing M&A, access to the full annexes is a practical necessity — the high-level insights here indicate where to look; the subscriber materials show precisely how much.
Next steps and how to access full intelligence
PW Consulting is making a limited number of executive briefings available in Q1–Q2 2026 to discuss bespoke scenarios, supplier risk workshops and M&A target screening based on the full dataset. For access to the complete report, supporting spreadsheets and an invitation to a private briefing, please consult the PW Consulting markets portal. We recommend early engagement: with evolving regulatory timelines and raw-material volatility, the decisions made in the next six to twelve months will materially affect competitive positioning through the end of the decade.
PW Consulting’s Antirusting Anti Rust Agents Market study bridges market-scale forecasting with execution-level tools — enabling leaders to convert market growth into defensible margin and sustainable product portfolios while navigating the increasingly complex regulatory and commodity landscape.
For detailed analysis of this topic, please visit the official page: Antirusting Anti Rust Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


