



PW Consulting Predicts Material Handling Robotics Market to Soar at 15.01% CAGR, Driving Next‑Gen Warehouse Automation

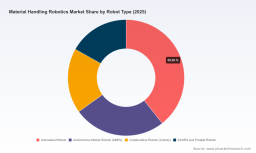
Material Handling Robotics Market 2026: A Strategic Preview for Executive Decision‑Making
PW Consulting’s latest Material Handling Robotics Market Research provides senior executives, operations leaders, and investment committees with the strategic intelligence required to make high‑stakes automation decisions in 2026. This release is a curated preview designed to convey the report’s analytical depth, practical utility, and near‑term implications — while preserving the detailed segment intelligence that makes the full report a must‑read for teams preparing capital allocation, pilot programs, or M&A activity this year.
Material Handling Robotics Market Research
Big Picture: Why 2026 Is a Pivotal Year
The robotics-driven automation market for material handling has moved from episodic investment into sustained adoption. PW Consulting’s base‑year assessment (2025) places total market size well into the multi‑billion USD range, and our seven‑year forecast shows persistent expansion through 2032 at a compounded annual growth rate of 15.01%. In practical terms, organizations that align strategy and budget cycles to this growth trajectory can capture outsized productivity gains, reduce exposure to labor volatility, and secure long‑term cost efficiencies.
Material Handling Robotics Market Research
- Growth trajectory: Substantial year‑on‑year expansion through the 2026–2032 forecast window underscores both the scale and urgency of decisions facing manufacturers, logistics providers, and 3PLs.
- Market structure: The market exhibits a moderate level of concentration (CR3 ≈ 38.5%, CR5 ≈ 52.1%), meaning leading global suppliers remain highly influential, but room exists for specialized and regional challengers — particularly in software, system integration, and AMR niches.
- Decision cadence: 2026 is the inflection point for organizations moving from demonstrator pilots to multi‑site rollouts; this report is built to inform both tactical deployments and portfolio strategies.
Core Dynamics Shaping 2026 Decisions
- Labor and productivity pressures: Persistent skilled labor shortages and wage inflation are accelerating ROI timelines for automation investments. The immediate consequence is shorter payback expectations and higher tolerance for upfront capital when paired with measurable throughput gains.
- E‑commerce and fulfillment complexity: Continued e‑commerce expansion raises demand for flexible, goods‑to‑person and goods‑to‑robot flows, favoring modular AMR and integrated robotic solutions that can adapt to SKU proliferation.
- Regulatory and interoperability expectations: Industry 4.0 policies and safety standards are crystallizing interoperability requirements, pushing suppliers to offer modular, standards‑based solutions and certified safety toolchains.
- Input cost sensitivity: High‑grade steel and advanced polymers remain meaningful contributors to production cost—our supply‑side sensitivity analysis shows these inputs account for roughly a quarter to a third of manufacturing cost in automated handling equipment, making procurement strategy and supplier diversification important risk levers.
What the Report Contains — Practical Tools for 2026 Execution
This report is intentionally operational. Beyond headline forecasts, PW Consulting delivers tools and playbooks designed to be used in boardrooms and on factory floors:
Material Handling Robotics Market Research
- Proprietary market forecasting model with scenario ranges to stress‑test capital plans under differing macro and demand assumptions for 2026 decision cycles.
- Vendor benchmarking framework and procurement scorecards that evaluate technology fit, total cost of ownership, service economics, and software openness.
- Deployment playbooks: phased pilot templates, KPI definitions, and scale‑up roadmaps that translate proof‑of‑concept outcomes into enterprise rollouts.
- TCO and ROI calculators tailored to AMRs, articulated robots, cobots, and integrated systems — enabling side‑by‑side comparisons under realistic labor and throughput assumptions.
- Risk and resilience matrices addressing supply‑chain disruption, raw material inflation, and component lead times — with mitigation guidance for procurement and inventory strategy.
- Regulatory compliance checklists and safety integration guidelines that align with cross‑jurisdictional standards and industry best practices.
- Case studies and vendor negotiation playbooks that capture lessons from large scale implementations across manufacturing and logistics.
Competitive Landscape: Strategic Profiles and Market Moves
The Material Handling Robotics ecosystem blends established industrial OEMs with software‑centric AMR pioneers and systems integrators. Executives must evaluate partners across three dimensions: product breadth, solutionization capability (hardware + software + service), and go‑to‑market agility. Below are distilled strategic notes on core players covered in the report.
- FANUC Corporation (Japan) — A stalwart in articulated robotics and palletizing systems. FANUC’s strengths remain mechanical reliability and global service footprint; strategic differentiation will come from expanding digital services and lifecycle monetization.
- ABB Robotics (Switzerland) — Focused on flexible automation and integrated intralogistics. ABB’s advantage is system integration capability across warehousing and production; look for increased emphasis on software platforms to bind solutions.
- KUKA AG (Germany) — Provider of robotic arms and AMR lines. KUKA’s competitive posture centers on integrated internal transport and production automation, with product roadmap moves aimed at tighter fleet orchestration.
- Yaskawa Electric (Motoman, Japan) — Optimized industrial robots for high‑speed material handling. Expect continued focus on throughput performance and specialized end‑effectors for complex picking tasks.
- Kawasaki Heavy Industries (Japan) — Heavy payload robotic systems and automated loading solutions. Kawasaki’s position is strong in high payload applications and heavy industry transitions to automation.
- Daifuku Co., Ltd. (Japan) — Integrated intralogistics systems combining conveyors, AGVs/AMRs, and robotics. Daifuku’s systems strength makes them a preferred partner for turnkey warehouse modernization.
- SSI SCHAEFER (Germany) — Known for highly integrated picking, sorting, and storage automation; excels in large‑scale fulfillment systems backed by strong project execution capabilities.
- Dematic (KION Group, Germany/USA) — Offers AS/RS, AGV/AMR fleets and robotic sortation; strategic moves include closer software integration and service-led offerings for long‑tail customers.
- Stäubli International (Switzerland) — High‑precision robots for cleanroom and industrial contexts; positioned strongly in pharmaceutical and electronics handling where precision and certification matter.
- Jungheinrich AG (Germany) — Combines traditional material handling equipment with automated guided vehicles; diversified channel and aftermarket presence are competitive strengths.
- Honeywell Intelligrated (USA) — Integrated solutions for distribution centers combining conveyors, sortation, and robotics; emphasizes software orchestration and lifecycle services.
- Toyota Material Handling (Japan) — AGVs and integrated robotic solutions paired with strong logistics vehicle platforms; supply chain trust and service networks remain compelling.
- Geek+ (China) — AMR and goods‑to‑person systems with rapid ROI propositions; competitive in high‑velocity e‑commerce deployments and markets prioritizing speed to scale.
- OTTO Motors / Clearpath (Canada) — Focused on industrial AMRs for production logistics; strength lies in vehicle autonomy, safety stacks, and fleet orchestration.
- Seegrid Corporation (USA) — Vision‑guided AMRs that reduce infrastructure burden; attractive to manufacturers seeking flexible, non‑fixed transport automation.
Recent industry activity underscores these trends. MODEX 2026 showcased new AMR and robotic innovations from major OEMs and challengers alike, while product updates from AMR specialists highlighted smarter autonomy and safety improvements — signals that 2026 will emphasize software‑driven differentiation and rapid field upgrades.
Strategic Playbook: Five Priority Actions for 2026
- Prioritize modularity: Opt for architectures that allow incremental expansion of robotic fleets and integration points — this reduces obsolescence risk and supports future interoperability.
- Design pilots with scale in mind: Embed quantifiable KPIs and success thresholds into pilots so that positive outcomes can translate rapidly into enterprise rollouts.
- Assess suppliers on software and service economics: Beyond unit cost, evaluate vendor roadmaps for fleet orchestration software, OTA updates, and lifecycle service economics.
- Mitigate input‑cost risk: Build procurement hedges and multi‑sourcing strategies for critical components and raw materials that influence equipment cost and lead times.
- Invest in change management: Pair technology deployments with workforce reskilling and safety training; this protects productivity during transition and accelerates adoption.
Why PW Consulting’s Report Is Tactical for 2026
Executives need more than high‑level forecasts; they need implementable decisions that reduce execution risk. PW Consulting’s Material Handling Robotics report combines rigorous macro forecasting (with a clear base year and multi‑scenario outlook) and hands‑on playbooks designed for 2026 procurement cycles, CAPEX requests, and operational transformation programs.
This preview outlines the report’s strategic value without disclosing the granular segmentation data that drives vendor selection and site‑level decisions. The full report contains the detailed regional and application splits, supplier share dynamics, and downloadable financial models that organizations use to finalize 2026 budgets and supplier contracts.
Next Steps
For boards, COOs, and supply chain leaders preparing for 2026, the recommended next step is a focused read‑out session of the full PW Consulting report. That session will translate the report’s near‑term forecasts, vendor benchmarks, and deployment templates into a prioritized action plan tailored to your asset base, revenue model, and risk appetite.
PW Consulting stands ready to lead tailored workshops, provide vendor selection support, and run live ROI modeling for pilot and multi‑site rollout programs. The strategic window for action is now — informed choices in 2026 will define operational cost structures and service capabilities for the decade ahead.
For detailed analysis of this topic, please visit the official page: Material Handling Robotics Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


