



PW Consulting Forecast: Thermoplastic Conductive Additives Market to Expand at a Robust 9.42% CAGR Through 2032

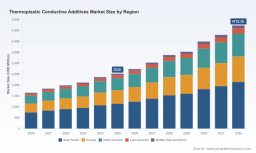
Thermoplastic Conductive Additives Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market research on Thermoplastic Conductive Additives delivers a focused, decision-ready perspective for executives planning investments, partnerships, and product roadmaps in 2026. This preview summarizes the report’s strategic value, highlights the macro trajectory behind our modelling, and maps the competitive dynamics that will shape supplier and buyer strategies through the 2026–2032 forecast window.
Thermoplastic Conductive Additives Market
Market trajectory at a glance
Our model shows the thermoplastic conductive additives market accelerating steadily through the first half of the decade. After expanding from USD 1,648.5 Million in 2020 to USD 2,520.0 Million in 2025 (base year), the market is forecast to continue growing at a compound annual growth rate (CAGR) of 9.42% over the 2026–2032 horizon. By our projections, the market reaches an inflection point in the late 2020s as demand for electrically and thermally conductive thermoplastics scales across higher-value applications and as next-generation nanomaterials gain broader commercial traction.
Thermoplastic Conductive Additives Market
Why this matters for 2026 strategy
-
Timing of investment: The 9.42% CAGR implies a near-term window in 2026–2028 where capacity additions and supply contracts can capture disproportionate share expansion. Firms that align capacity, product portfolios, and go-to-market investment in 2026 will be best positioned to leverage the compound growth into the early 2030s.
Thermoplastic Conductive Additives Market -
Risk management for feedstocks: Feedstock dynamics (notably carbon black volatility and nanotube capacity ramps) will materially affect margins and product availability. Our analysis quantifies exposure by formulation type and recommends hedging and vertical integration scenarios tailored to different risk appetites.
-
Regulatory inflection: A scheduled evaluation of carbon black in Europe in 2027 introduces regulatory risk that manufacturers must model into 2026 procurement and product roadmaps. Contingency strategies — alternative additive mixes, substitution pathways, and regulatory engagement plans — should be initiated in 2026.
What the PW Consulting report provides — practical, transaction-ready outputs
The report is structured to support three immediate use cases for corporate leaders and investors in 2026: (1) allocate R&D and capex efficiently; (2) optimize supply chains and commercial partnerships; and (3) plan M&A or joint-venture moves with clear valuation sensitivities. To support these objectives, the report contains:
-
Market-sizing and scenario modelling: Base-case and alternative scenarios to stress-test demand assumptions under different adoption and raw-material-price pathways.
-
Product and application adoption maps: Trajectories for thermal vs. electrical conductive solutions across key end-markets, with technology migration timelines and cost-in-use templates to evaluate substitution economics.
-
Supply-chain diagnostic and raw-material analytics: Cost stacks for common formulations; sensitivity matrices to carbon black, CNTs, and graphene pricing; and supplier risk heatmaps for each supply node.
-
Regulatory and standards playbook: Actionable steps tied to the upcoming European evaluation processes and emergent compliance norms for nanomaterials.
-
Competitive landscaping and partner shortlists: Benchmarked technology profiles, scale maps, and go-to-market capabilities for leading compounders, additive producers, and specialty resin houses.
-
Commercial playbooks: Pricing strategies, channel design, and co-development templates tailored for compounders, OEMs, and material suppliers seeking to accelerate adoption in high-growth niches.
-
M&A and investment guidance: Valuation ranges driven by revenue and margin multiple sensitivities, plus diligence checklists and integration playbooks for bolt-on acquisitions or strategic alliances.
Note: This public preview intentionally omits detailed sub-segment allocations and proprietary numeric splits — those are available in the full report and are essential to tactical contracting, pricing, and plant-location decisions.
Competitive landscape — who matters and why
The market displays moderate concentration dynamics, with the top three and five players accounting for a substantial portion of the market. This structure creates both opportunities for challengers and risks for incumbents. Below we summarize the practical positions of key players that PW Consulting tracks closely.
-
Cabot Corporation (Boston, MA) — A global leader in carbon black-based conductive solutions, Cabot’s CABELEC portfolio is structured around high-volume static-dissipative and conductive compounds. Strengths: scale of carbon-black know-how, integrated supply capability, and tailored concentrates for wire & cable and industrial markets.
-
Avient Corporation (Avon Lake, OH) — Avient’s offerings span thermally conductive and electrically conductive masterbatches and compounds. Strengths: strong formulation capabilities in engineering resins, and established relationships with OEMs requiring thermal management and ESD protection.
-
RTP Company (Winona, MN) — Niche expertise in conductive compounds across a wide conductivity range, from dissipative to shielding solutions. Strengths: customization at scale, close co-development with injection-molding customers.
-
SGL Carbon (Wiesbaden, Germany) — Focused on expanded graphite powders to deliver high thermal conductivity while managing processability. Strengths: graphite specialization and strong positioning in thermal management segments.
-
LATI S.p.A. (Vedano Olona, Italy) — Offers a diverse portfolio of conductive compounds leveraging graphite, carbon black, nanotubes, and metal fibers. Strengths: broad compound portfolio across many polymer matrices.
-
Americhem (Cuyahoga Falls, OH) — Known for thermally conductive InTherm compounds for EVs, lighting and medical devices. Strengths: market focus on thermal solutions and application-engineering capabilities.
-
SABIC (Riyadh, Saudi Arabia) — Major resin house providing compounded conductive thermoplastic solutions and specialty resins. Strengths: material breadth and global distribution scale.
-
Imerys S.A. (Paris, France) — Supplies carbon-based conductive additives and fillers for polymers. Strengths: legacy minerals expertise and diversified filler portfolio.
-
OCSiAl (Luxembourg) — Specialist in single-walled carbon nanotube concentrates (TUBALL) optimized for low-loading conductivity. Strengths: disruptive low-load technology with limited mechanical property trade-offs.
-
LEHVOSS Group (Hamburg, Germany) — Produces conductive thermoplastic compounds using carbon fibers, CNTs and graphite, reaching high thermal conductivities for demanding thermal-management applications.
-
Teknor Apex (Pawtucket, RI) — Formulates engineering thermoplastics with a broad range of modifiers for custom performance.
-
Bekaert (Zwevegem, Belgium) — Supplies metal-fiber fillers (e.g., stainless steel fibers) for conductive blends used in shielding and antistatic applications.
PW Consulting’s competitive assessments go beyond product catalogues; we model manufacturing footprints, IP barriers, distribution reach, and co-development pipelines to identify which firms are best positioned to capture growth in each strategic scenario.
Supply-side dynamics and market “noise” that influence 2026 choices
Strategic decisions for 2026 must incorporate several supply-side signals that will directly affect costs and availability:
-
Raw-material price volatility: North American carbon black pricing reached approximately USD 2.03/kg in early 2026, with upward movement tied to feedstock demand and logistics. Buyers and compounders should model multi-year supply contracts and blended sourcing to mitigate margin erosion.
-
Feedstock availability and competing demand: The broader carbon black market remains large and primarily driven by tire manufacturing; this creates periodic squeeze events for additive-grade carbon black. Companies with flexible formulations or access to alternative conductive fillers will have a resilience advantage.
-
Nanomaterials ramp: The carbon nanotubes market is entering a capacity expansion phase, with market sizing estimates pointing to meaningful commercial scale by 2026. Low-loading nanotube concentrates offer performance advantages, but supply chain and quality control issues remain key gating factors for rapid adoption.
-
Regulatory scrutiny: The pending regulatory evaluation of carbon black in Europe (scheduled for 2027) is a material planning consideration that should accelerate 2026 contingency planning, especially for manufacturers and compounders with European exposure.
-
Industry moves: Recent capacity expansions and partner programs in graphene and nanomaterials — including announced production increases and compounding partner initiatives — are widening the set of practical formulation choices for 2026 product development.
Recommended 2026 playbook (executive summary)
-
Immediate (Q1–Q2 2026): Undertake supply-security audits and sign rolling purchase agreements for critical feedstocks. Run formulation cost-sensitivity scenarios across carbon black, CNTs, and graphene mixes.
-
Medium term (H2 2026): Launch co-development pilots with low-loading nanotube or graphene concentrate suppliers, prioritizing applications where reduced mechanical compromise and higher conductivity unlock value (thermal management, EMI shielding, and advanced consumer devices).
-
Strategic (end of 2026): Evaluate bolt-on acquisition targets among regional compounders to secure local capacity and customer relationships; deploy targeted capex where the model shows a >12–15% IRR under base-case pricing and supply assumptions.
-
Regulatory & sustainability: Develop compliance playbooks and alternative-formulation registries to rapidly respond to any 2027 regulatory action on carbon black in Europe, and articulate the ESG narrative tied to material substitutions and lifecycle benefits.
Next steps — where to get the full intelligence
This briefing is designed as a strategic “preview” to inform 2026 planning. The full PW Consulting Thermoplastic Conductive Additives Market report contains the detailed segmentation matrices, proprietary unit-cost models, and supplier-by-supplier scorecards that underpin the high-level guidance above. These detailed outputs are intentionally gated to preserve the tactical value for clients and transaction teams.
For firms preparing 2026 budgets, R&D plans, or M&A pipelines, the full dataset and scenario tools are essential to translate this strategic preview into executable decisions — from plant location selection to contract negotiation and product launch sequencing.
Contact PW Consulting to request access to the full report, bespoke scenario runs, or a workshop to convert these insights into a 90–180 day action plan tailored to your organization.
For detailed analysis of this topic, please visit the official page: Thermoplastic Conductive Additives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


